European Session Crude Oil Report — 26 Oct 2026
QuoteReporter
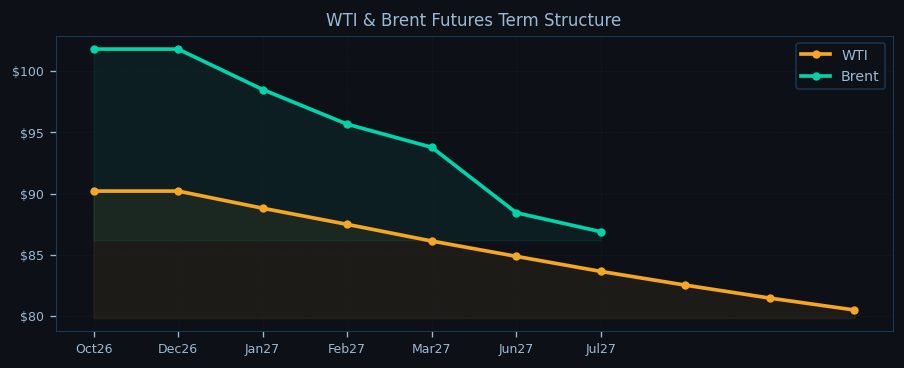
Crude oil markets edge cautiously higher in European trading as Brent tests the $103 handle while WTI struggles to hold above $90, with the Brent-WTI spread widening to $12.16 as European refiners face tighter North Sea supply. The complex builds on Brent’s modest 0.75% overnight gains from Asia where Shanghai crude futures found support at technical levels, though WTI remains pressured by its oversold RSI at 22.5 against weakening US physical market indicators. The term structure steepens its backwardation with Brent’s front-to-Jul27 spread now at -14.6%, signaling persistent near-term tightness despite recession fears.
Technicals paint a divergent picture as Brent holds above its EMA21 at $101.63 (+1.4%) while WTI trades $2 below its equivalent average at $92.90. The RSI divergence is stark - Brent’s 38.9 reading suggests room for recovery versus WTI’s capitulation-level 22.5. Key pivot points loom at $89.46 for WTI (current $90.86) and $96.17 for Brent ($103.02), with the latter’s upside testing the first resistance at $117.04. The Brent-WTI spread widens to its highest since June as European crude differentials firm on disrupted North Sea loadings, forcing regional refiners to absorb higher transport costs for US barrels.

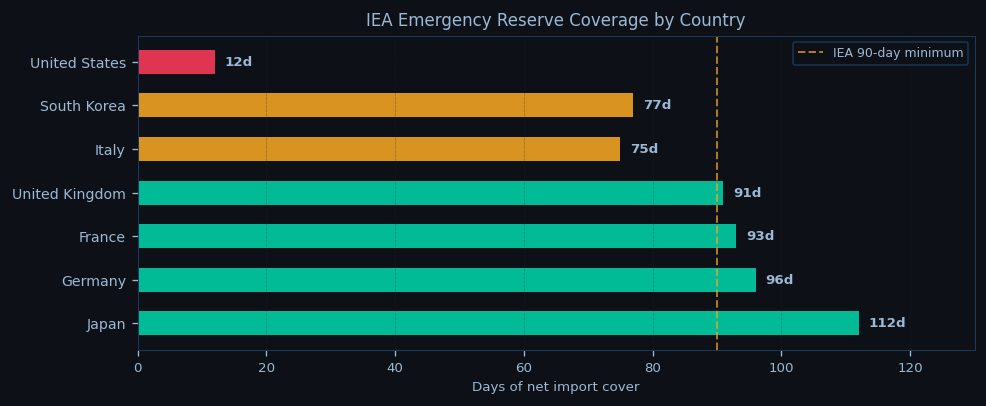
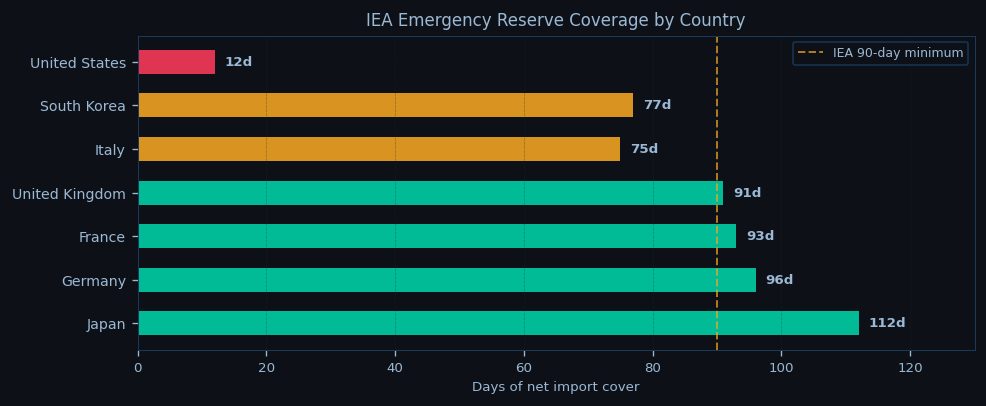
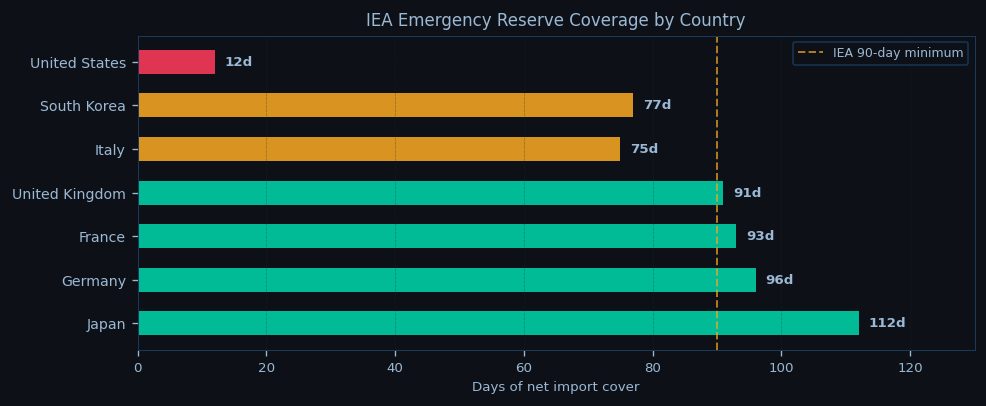
Geopolitical tensions keep Hormuz risk premiums elevated with IRGC naval activity disrupting tanker movements, while Houthi threats in Bab-el-Mandeb divert VLCCs around Africa - adding $1.50/bbl to freight costs. OPEC+ discipline remains firm with the group maintaining 0.6 mb/d deficit against call, though Russian Urals discounts deepen to $18/bbl under Brent as EU sanctions tighten. US crude stocks hover near operational minimums with Cushing at 24.3 mb and SPR draws slowing at 39.7% capacity, though refinery runs at 92.5% suggest demand resilience.
The backwardation steepens notably in Brent as prompt barrels command premium amid supply concerns, with Oct26 at $101.80 versus Jul27 at $86.89. WTI’s curve shows similar but less pronounced stress at -10.8% for same period. This structure pressures shorts as prompt cover becomes costly, particularly for European players facing Brent’s steeper contango. US production stabilizes at 13.95 mb/d but faces pipeline constraints in Permian, limiting WTI’s upside.
Session focus turns to the NYMEX open with traders watching whether WTI can defend $90 as Brent tests $103 resistance. The spread dynamics favor Brent amid Atlantic basin tightness, though recession fears linger with both contracts down ~4% weekly. Key levels to watch are WTI’s PP at $89.46 and Brent’s S1 at $82.16 - a break below could accelerate selling. For now, the market balances geopolitical risk against macroeconomic headwinds, with backwardation and Middle East tensions providing floor under prices.

Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.
Related Articles
- US Session Crude Oil Report — 23 Oct 2026 — WTI crude is trading at $90.86 in early New York trading, holding just above the pivotal $89.46 support as Brent tests…
- European Session Crude Oil Report — 23 Oct 2026 — Crude oil markets remain under pressure in the European session as WTI hovers near $90.86, down 0.27% on the day, while…
- Asian Session Crude Oil Report — 23 Oct 2026 — WTI crude is trading at $90.86 in early Asian hours, holding near overnight lows as the contract extends its seven-day…
- US Session Crude Oil Report — 22 Oct 2026 — WTI crude is trading at $90.86 in early New York trade, testing the lower bounds of its weekly range as the contract…
- Philippines Earthquake Disrupts Nickel Supply — Earthquake Disrupts Nickel Supply in the Philippines On October 21, 2026, a magnitude 5.2 earthquake struck 68 km…