European Session Crude Oil Report — 23 Oct 2026
QuoteReporter
Crude oil markets remain under pressure in the European session as WTI hovers near $90.86, down 0.27% on the day, while Brent trades at $103.02 with modest gains of 0.75%. The Asian overnight range saw both benchmarks test multi-week lows before stabilizing, with WTI finding temporary support at $89.80 and Brent defending $101.50. Momentum remains bearish as WTI’s RSI at 22.5 flirts with oversold territory, while Brent’s 38.9 RSI suggests weaker but still downward-leaning sentiment. The Brent-WTI spread holds at $12.16, a level that continues to incentivize European refiners to favor Atlantic Basin grades over US exports.
Technically, WTI struggles below all key moving averages, with the EMA9 at $92.34 acting as immediate resistance. The contract tests the pivot point at $89.46, a breach of which opens the path toward $72.17 support. Brent shows marginally more resilience, trading just below its EMA9 at $103.07, though the 21-day and 50-day EMAs at $101.63 and $97.21 respectively suggest potential consolidation zones. Both benchmarks remain entrenched in backwardation, with WTI’s Oct26-Jul27 spread at -10.8% and Brent’s at -14.6%, reflecting persistent near-term supply concerns despite the broader sell-off.

Geopolitical tensions continue to underpin crude’s risk premium, particularly around the Strait of Hormuz where IRGC naval activity disrupts tanker movements, threatening 20M bbl/d of flows. The Bab-el-Mandeb chokepoint remains on watch as Houthi attacks force VLCCs to divert via the Cape of Good Hope, adding 7 days to voyage times. These disruptions offset otherwise stable flows through the Suez Canal and Malacca Strait. Meanwhile, OPEC+ maintains its production cuts through December 2026, with the group’s output trailing call-on-OPEC by 0.6 mb/d. Saudi Arabia adheres strictly to quotas, though Iraq and Russia continue to produce slightly above targets.
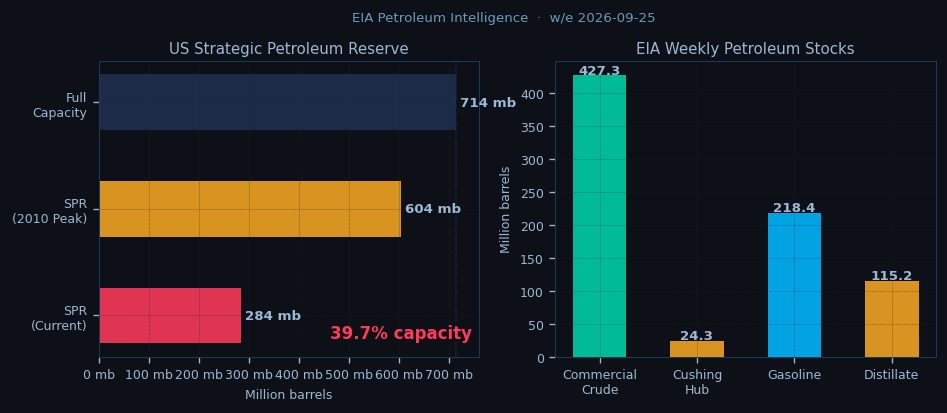
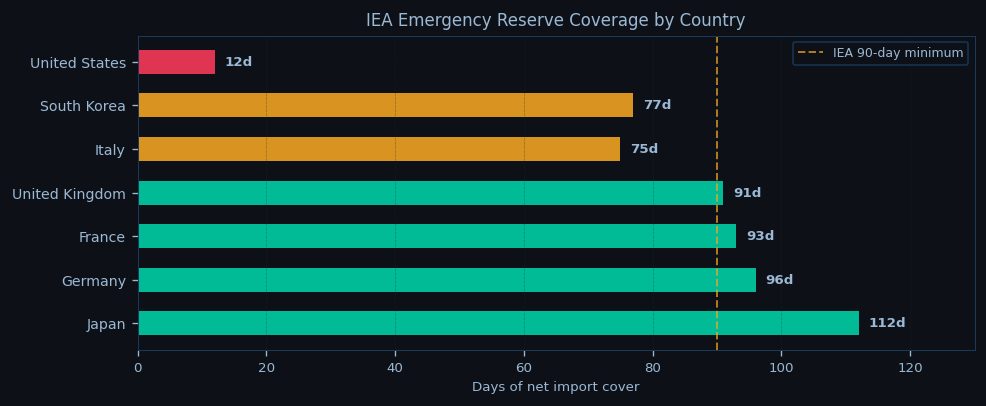
The EIA’s latest report shows US commercial crude inventories at 427.3 mb, a minor 0.9 mb build, while the SPR holds at 283.8 mb (39.7% capacity). Domestic production edges up to 13.95 mb/d, with refinery runs at 92.5% utilization—a sign of healthy demand. Cushing stocks at 24.3 mb remain tight, exacerbating WTI’s backwardation. Market participants now await the NYMEX open at 14:30 CET for directional cues, with traders closely monitoring whether the European session’s tentative stabilization can hold.
For the session ahead, WTI’s ability to reclaim $91.50 would signal short-covering potential, while failure to hold $89.46 risks a slide toward $82. Brent faces resistance at $104.20 (yesterday’s high), with support at $101.50. The Brent-WTI spread may widen further if European refinery demand persists, though arbitrage economics cap significant expansion beyond $13. With the geopolitical floor still intact and technicals oversold, the market looks for equilibrium ahead of the US session—where another test of recent lows remains possible unless fresh bullish catalysts emerge.

Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.
Related Articles
- Asian Session Crude Oil Report — 23 Oct 2026 — WTI crude is trading at $90.86 in early Asian hours, holding near overnight lows as the contract extends its seven-day…
- US Session Crude Oil Report — 22 Oct 2026 — WTI crude is trading at $90.86 in early New York trade, testing the lower bounds of its weekly range as the contract…
- Philippines Earthquake Disrupts Nickel Supply — Earthquake Disrupts Nickel Supply in the Philippines On October 21, 2026, a magnitude 5.2 earthquake struck 68 km…
- European Session Crude Oil Report — 22 Oct 2026 — Crude oil markets trade mixed in the European session as Brent holds above $103 while WTI struggles below $91, with the…
- US Session Crude Oil Report — 21 Oct 2026 — WTI crude hovers near $90.86 in early New York trade, testing the lower bounds of its weekly range as bearish momentum…