Bank credit expands $57.1B as C&I loans surge 10% YoY, offsetting sluggish real estate growth
MarketsFN Data Team
The H.8 — Assets and Liabilities of Commercial Banks in the United States — is a weekly statistical release from the Federal Reserve, published every Friday at 4:15 PM ET. It covers the combined balance sheet of all US-chartered commercial banks, covering roughly $19+ trillion in total assets. Because bank credit underpins most economic activity — business investment, home purchases, consumer spending — the H.8 is one of the most closely watched leading indicators of economic health.
Total bank credit ($19.95T today) includes two major components: loans and leases (direct lending to businesses and households) and securities (government bonds, MBS, and other fixed-income holdings). Of the two, loans are the more economically significant — they create new purchasing power. Securities holdings fluctuate with the Fed's QE/QT cycles and banks' liquidity management decisions, not with private sector borrowing demand.
C&I loans ($2.96T, 28% of total) are commercial and industrial loans — credit to businesses for working capital, equipment, and operations. They are a leading indicator of corporate confidence. Real estate loans ($5.84T, 54%) cover mortgages and commercial property. Consumer loans ($1.93T, 18%) include credit cards, auto loans, and student debt — a direct read on household financial health.
The credit/deposit ratio compares total bank credit extended to total deposits held. A ratio above 100% means banks are lending out (or investing in securities) more than they hold in deposits — they must fund the gap via wholesale markets or equity. Currently at 100.9%, this metric signals whether the banking system is in a phase of credit expansion (ratio rising), contraction (falling), or deposit flight (deposits falling faster than credit).
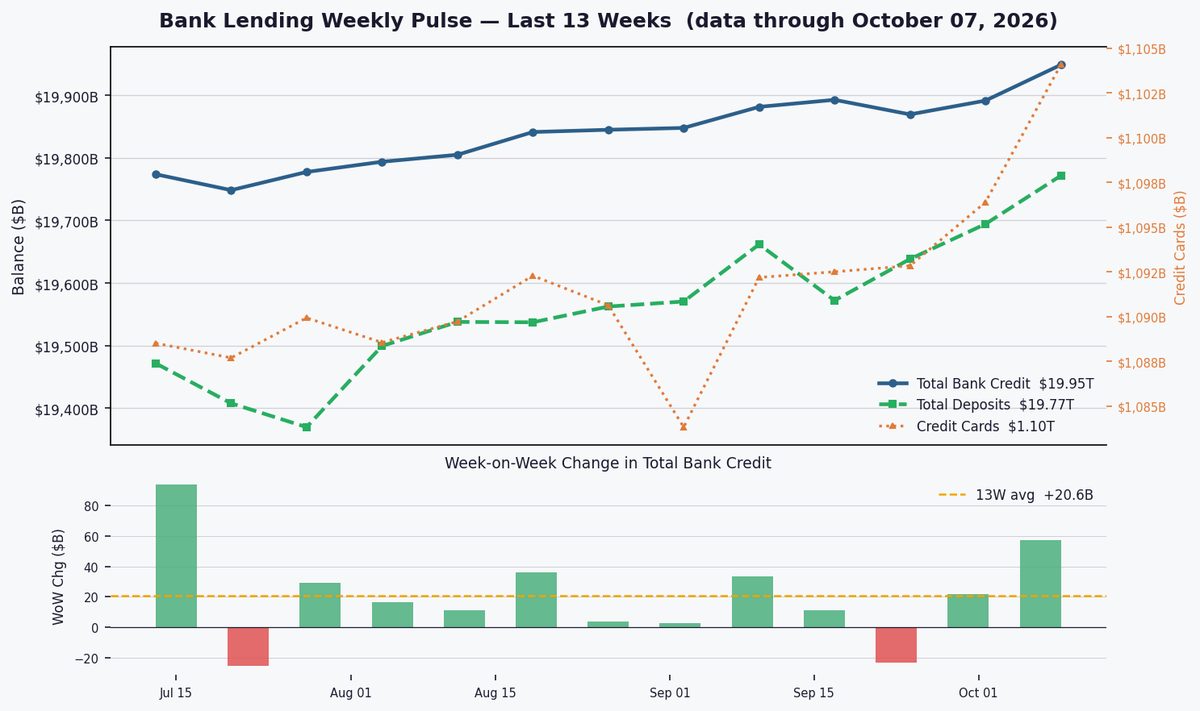
Total bank credit rose to $19.95T (+$57.1B WoW) with a 100.9% credit/deposit ratio, signaling sustained lending appetite despite Fed Funds at 3.75% as businesses drive expansion.
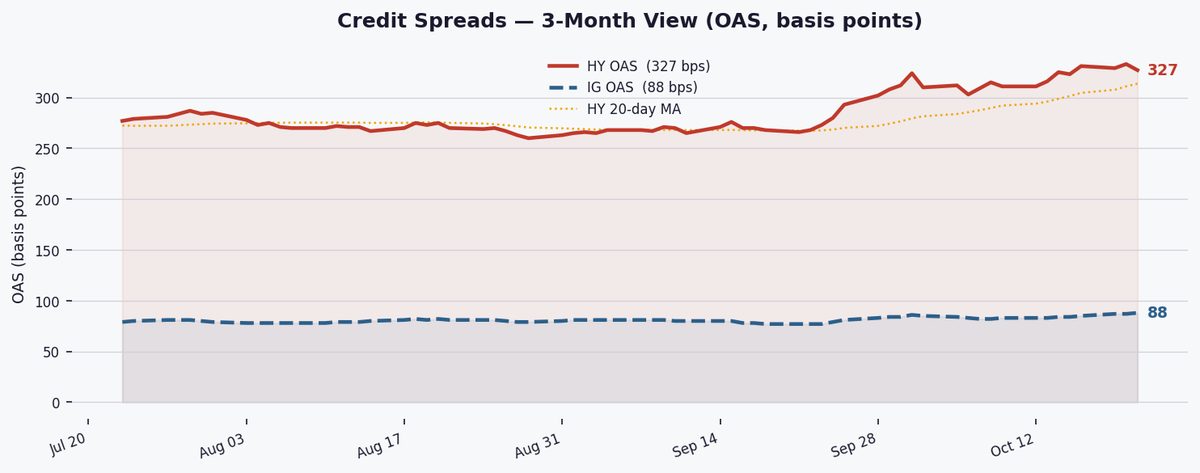
The $57.1B weekly bank credit expansion outpaced the 13-week average of $20.6B, reflecting looser credit conditions as deposit funding grew $77.3B. Credit card loans rose $7.7B (4.7% YoY), marking the 4th consecutive acceleration — a potential early stress signal despite robust consumer spending. The deposit influx eases funding pressures but masks divergent sectoral demand.
C&I loans remain the growth engine at 10.0% YoY ($2.96T), while real estate lending stalls at +2.7% ($5.84T) amid high rates. The 28/54/18 loan mix shows businesses borrowing for operations, not expansion. Consumer loans at +5.0% ($1.93T) and credit cards at +4.7% suggest moderate stress, though not yet alarming given 6.9% deposit growth.

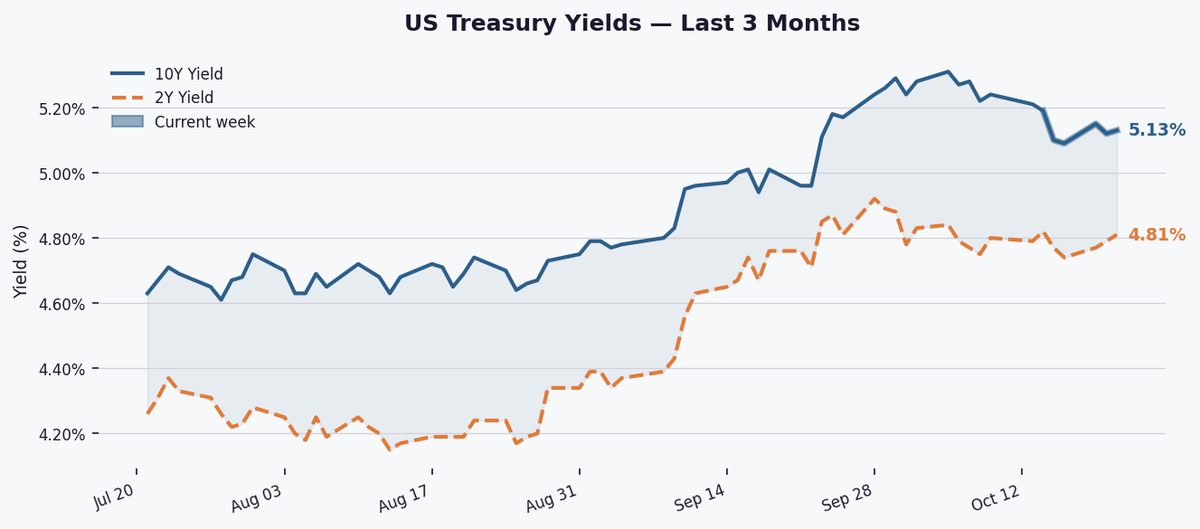
The 100.9% credit/deposit ratio slightly exceeds the 4Y average (100.6%), indicating manageable funding pressure. With Fed Funds at 3.75%, banks balance deposit costs against loan yields. Current conditions favor measured expansion, but another 25bp hike could tip the ratio into restrictive territory as deposit betas lag.
Full Statistics Dashboard
| Metric | Latest Value | Change / Context | Frequency |
|---|---|---|---|
| Data through | October 07, 2026 | Weekly H.8 | |
| Total bank credit | $19.95T | ▲ $57.1B WoW +5.8% YoY | Weekly |
| Total deposits | $19.77T | ▲ $77.3B WoW +6.9% YoY | Weekly |
| Credit cards | $1.10T | ▲ $7.7B WoW +4.7% YoY | Weekly |
| Credit / deposit ratio | 100.9% | 4Y avg: 100.6% | Weekly |
| C&I loans | $2.96T | 27.6% of loans +10.0% YoY | Monthly |
| Real estate loans | $5.84T | 54.5% of loans +2.7% YoY | Monthly |
| Consumer loans | $1.93T | 18.0% of loans +5.0% YoY | Monthly |
| Fed Funds Rate | 3.75% | Monthly | |
| Lending signal | EXPANDING | 13W avg WoW: +$20.6B |
Weekly series through October 07, 2026 (H.8 weekly, SA). Monthly categories through September 2026 — published in same H.8 release with ~6-week lag.
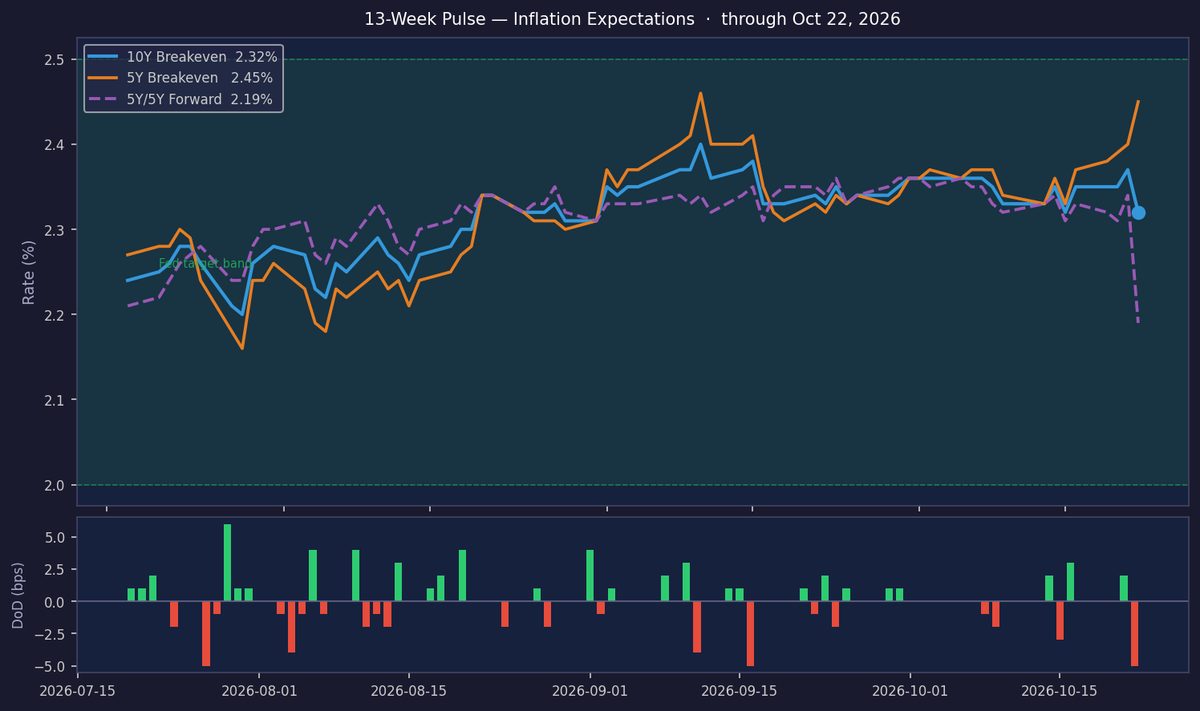
Watch September CPI (Oct 12) for Fed policy clues — hot inflation could choke C&I demand. Credit card growth above 5% YoY risks delinquencies if employment softens. A sustained >$50B weekly credit expansion would confirm accelerating conditions, while sub-$10B prints may signal tightening.