HY spreads tighten 6bps to 327bps as risk appetite edges up amid normal regime
MarketsFN Data Team
The Option-Adjusted Spread measures the yield premium a corporate bond pays over a risk-free government bond of the same maturity — after stripping out the value of any embedded options (like call provisions). It isolates pure credit risk compensation. A wider OAS means bond investors demand more yield for holding corporate debt, signalling rising perceived risk. A tighter OAS means confidence in issuers is high and credit conditions are loose.
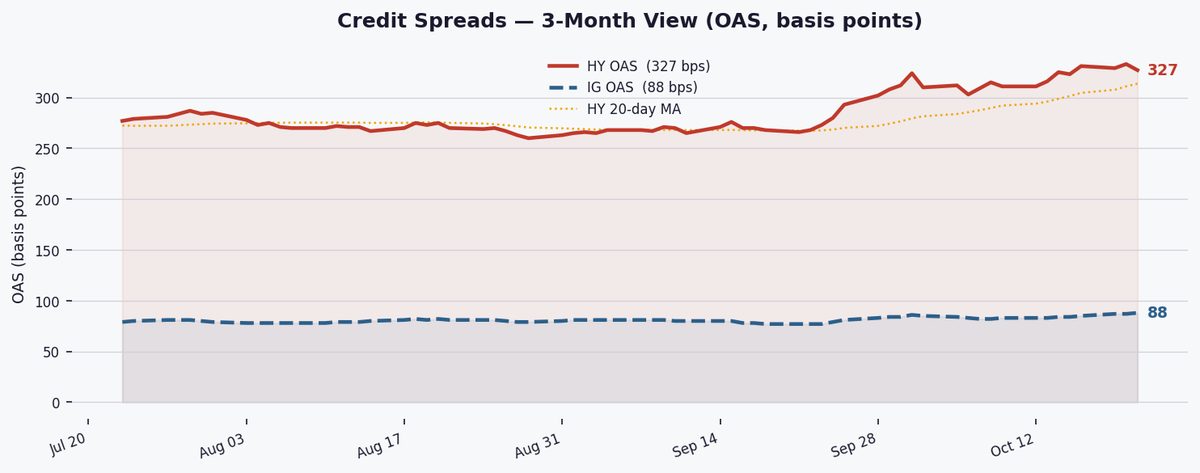
Investment Grade (IG) bonds are rated BBB−/Baa3 or above by S&P/Moody's. They represent large, financially stable companies. IG OAS is currently 88 bps. High Yield (HY) bonds are rated below BBB−/Baa3 — also called "junk bonds" — issued by companies with higher debt loads or less stable cash flows. HY OAS is 327 bps. The HY–IG gap of 239 bps is the market's price for taking extra risk.
When spreads widen (rise), investors are demanding more compensation for credit risk — often because recession fears are rising, corporate earnings are deteriorating, or liquidity is tightening. When spreads tighten (fall), risk appetite is strong: investors are willing to accept less yield premium, usually because the economic outlook is improving. Credit spreads often lead equity markets by days or weeks — they are a leading indicator of financial stress.
Historically, HY OAS has spiked before or during every US recession: ~600 bps in 2001, ~1,900 bps in 2008 (peak), ~900 bps in March 2020. The current HY OAS of 327 bps sits at the 78th percentile of the past 10 years — meaning spreads have been wider than today only 22% of the time. A sustained move above 600 bps would historically mark the threshold of serious credit stress.
High-yield spreads narrowed 6bps to 327bps today, remaining in a NORMAL regime but still widening week-on-week (+2bps), signaling cautious investor optimism with HY yields at 8.17%—enough to attract selective risk-taking but not yet a clear all-clear signal.
High-yield spreads sit at 327bps, in the 78th percentile of 10-year ranges, suggesting valuations are historically wide but off extremes. Today’s 6bp tightening contrasts with a 2bp weekly widening, while the 20-day MA (314bps) pulling further from the 60-day MA (285bps) hints at near-term widening pressure. The NORMAL regime still favors selective HY exposure, but the 10-year median (302bps) shows room for further normalization.
Investment-grade spreads edged 1bp wider to 88bps (56th percentile), lagging HY’s rally and pushing the HY-IG differential to 239bps vs its 220bps 4-year average. The gap suggests modest but not aggressive risk appetite—investors aren’t fleeing IG safety, but HY’s 8.17% yield is drawing incremental demand.
HY yields at 8.17% offer a 304bp premium over 10Y Treasuries (5.13%), while Moody’s Baa-Aaa spread of 47bp reflects moderate quality stress. These levels pressure leveraged borrowers, especially with SOFR at 3.88%, but the HY yield’s historical percentile suggests refinancing isn’t yet prohibitive for most issuers.

Full Statistics Dashboard
| Metric | Current | Change | Historical Rank |
|---|---|---|---|
| HY OAS (ICE BofA) | 327 bps | ▼ 6 bps DoD ▲ 2 bps WoW | 78th pct |
| IG OAS (ICE BofA) | 88 bps | ▲ 1 bps DoD ▲ 4 bps WoW | 56th pct |
| HY−IG Differential | 239 bps | 4Y avg: 220 bps ▲ 19 bps vs avg | |
| HY Effective Yield | 8.17% | over 10Y: +304 bps | |
| IG Effective Yield | 5.92% | ||
| Moody's Baa Yield | 6.57% | Baa−Aaa: 47 bps | |
| Moody's Aaa Yield | 6.10% | ||
| 10Y Treasury | 5.13% | ||
| SOFR | 3.880% | vs 3M T-Bill: ▼ 37 bps bps | |
| HY OAS Regime | NORMAL | Direction: WIDENING (20d MA 314 vs 60d MA 285 bps) | |
| 10Y HY Range | 259–461 bps | median 302 bps |
The SOFR-T-Bill spread at -37bp shows money markets remain relaxed, with repo rates below T-bill yields. This benign funding backdrop is supporting credit spreads, though it isn’t driving aggressive tightening—banks aren’t facing liquidity strains that would amplify HY/IG volatility.

Watch next week’s GDP and Fed speakers for shifts in growth expectations; a sustained HY OAS move above 340bps could signal a shift from NORMAL to WIDER, while a break below 300bps would suggest reversion to the decade median (302bps).