10Y Inflation Holds Steady at Fed Target 2.35%
MarketsFN Data Team
What is a breakeven rate?
The breakeven inflation rate equals the yield gap between a conventional Treasury and a TIPS of the same maturity. If the 10Y nominal yields 4.50% and the 10Y TIPS yields 2.00%, the 10Y breakeven is 2.50% — the level of average CPI at which an investor is indifferent between the two bonds. A higher breakeven signals stronger market inflation expectations.
Why three horizons?
The 5Y breakeven is most sensitive to near-term CPI prints and Fed policy. The 10Y breakeven blends short and long-run expectations. The 5Y/5Y forward looks only at years 5–10, stripping out near-term noise — it is the purest read on whether long-run inflation is anchored. The Fed watches the forward rate most closely.
The Fed's 2% target in breakeven terms
The Federal Reserve targets 2% PCE inflation, not CPI. Because CPI runs roughly 0.3–0.5 pp above PCE (different basket weights and housing costs), breakevens in the 2.2–2.5% range are broadly consistent with the Fed achieving its mandate. Breakevens above 2.5% signal markets doubting that 2% will be delivered; below 2.0% signals deflation or stagnation risk.
Real yields and monetary conditions
The 10Y TIPS yield is the "real" risk-free rate — what investors earn above and beyond inflation. Positive real yields make saving more attractive than spending or risk-taking: a tightening drag on the economy. Negative real yields (common in 2020–2022) were highly stimulative, driving asset prices and compressing credit spreads. The real yield is a direct gauge of monetary restriction.
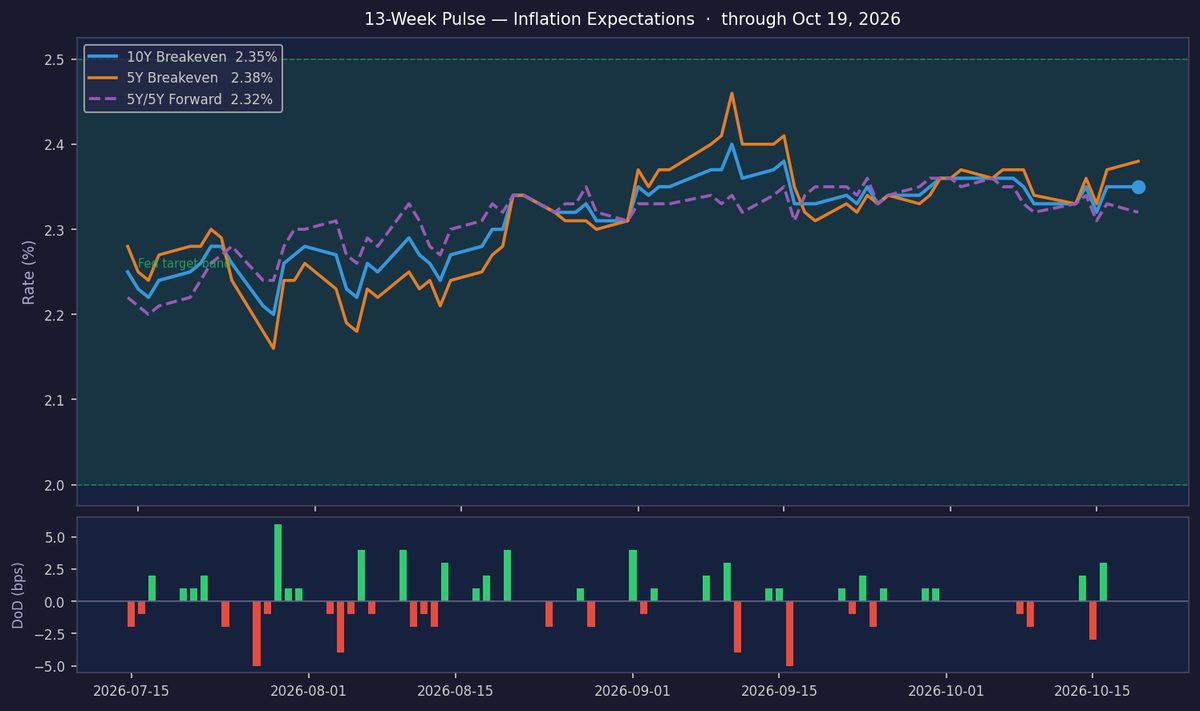
Inflation expectations remain firmly anchored, with the 10-year breakeven rate steady at 2.35% amid an ON TARGET regime. The lack of daily movement (+0.0 bps) reflects muted near-term catalysts, though the 2.0 bps weekly rise suggests incremental upward pressure. At the 75.4th percentile over the past decade, markets are pricing inflation slightly above historical norms but well within the Fed’s comfort zone.
The 5-year breakeven’s premium to the 10-year (-3.0 bps term premium) signals no material near-term inflation concerns, while the 5Y/5Y forward (2.32%) sits at the 83.8th percentile—elevated but stable. This suggests the Fed’s anchoring efforts are holding, with no evidence of structural drift. The forward curve remains consistent with a soft landing narrative, though the 4.0 bps WoW rise in 5Y breakevens warrants monitoring for short-term demand-side pressures.

The 10-year real yield of 2.74% remains firmly restrictive, with the 349 bps nominal-real spread reflecting embedded inflation expectations. Real yields have eased slightly (-4.0 bps DoD), but at this level, monetary policy continues to weigh on growth—consistent with the Fed’s higher-for-longer stance. The nominal yield’s climb to 6.23% underscores the persistence of inflation risk premiums in long-dated bonds.
A shift from ON TARGET would require either a sustained breach above 2.50% in 10Y breakevens or a collapse in the term premium (currently -3.0 bps). Near-term catalysts include October PCE data and any Fed pushback against recent yield declines. For now, the flatness of the breakeven curve suggests stability, but labor market or energy shocks could disrupt equilibrium. Maintain neutral duration risk.
| Series | Latest | DoD | WoW | 10Y Rank | Freq. |
|---|---|---|---|---|---|
| 10Y Breakeven (T10YIE) | 2.35% | +0.0 bps | +2.0 bps | 75.4th pct | Daily |
| 5Y Breakeven (T5YIE) | 2.38% | +1.0 bps | +4.0 bps | 68.4th pct | Daily |
| 5Y/5Y Forward (T5YIFR) | 2.32% | -1.0 bps | — | 83.8th pct | Daily |
| 10Y Real / TIPS (DFII10) | 2.74% | -4.0 bps | — | — | Daily |
| 10Y Nominal (DGS10) | 6.23% | +0.0 bps | +24.0 bps | — | Daily |
| Term Premium (10Y−5Y be) | -3.0 bps | n/a | — | — | Derived |
| CPI YoY | 4.0% YoY (September 2026) | n/a | — | — | Monthly |
| Core PCE YoY | 3.0% YoY (August 2026) | n/a | — | — | Monthly |