Bank credit expands $28.9B to $20.01T as C&I loans lead with 10% YoY growth
MarketsFN Data Team
The H.8 — Assets and Liabilities of Commercial Banks in the United States — is a weekly statistical release from the Federal Reserve, published every Friday at 4:15 PM ET. It covers the combined balance sheet of all US-chartered commercial banks, covering roughly $19+ trillion in total assets. Because bank credit underpins most economic activity — business investment, home purchases, consumer spending — the H.8 is one of the most closely watched leading indicators of economic health.
Total bank credit ($20.01T today) includes two major components: loans and leases (direct lending to businesses and households) and securities (government bonds, MBS, and other fixed-income holdings). Of the two, loans are the more economically significant — they create new purchasing power. Securities holdings fluctuate with the Fed's QE/QT cycles and banks' liquidity management decisions, not with private sector borrowing demand.
C&I loans ($2.96T, 28% of total) are commercial and industrial loans — credit to businesses for working capital, equipment, and operations. They are a leading indicator of corporate confidence. Real estate loans ($5.84T, 54%) cover mortgages and commercial property. Consumer loans ($1.93T, 18%) include credit cards, auto loans, and student debt — a direct read on household financial health.
The credit/deposit ratio compares total bank credit extended to total deposits held. A ratio above 100% means banks are lending out (or investing in securities) more than they hold in deposits — they must fund the gap via wholesale markets or equity. Currently at 101.2%, this metric signals whether the banking system is in a phase of credit expansion (ratio rising), contraction (falling), or deposit flight (deposits falling faster than credit).
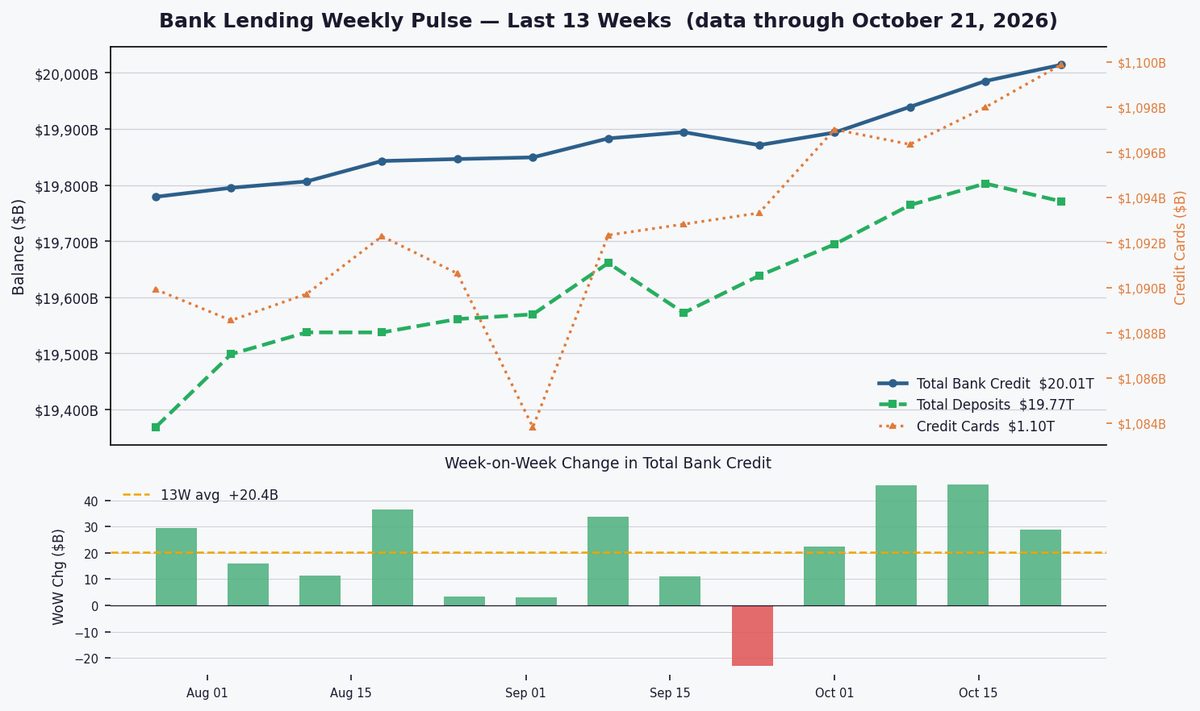
Total bank credit rose $28.9B to $20.01T, signaling expansion despite deposit outflows of $31.7B; the 101.2% credit/deposit ratio suggests banks are maintaining loan growth despite tighter funding conditions.
Bank credit expanded $28.9B this week, above the 13-week average of $20.4B, indicating resilient lending activity despite a $31.7B deposit outflow that pressures bank funding. Credit card loans grew $1.9B, maintaining a steady 4.1% YoY pace — neither accelerating into stress nor decelerating into caution, suggesting measured consumer borrowing.
C&I loans dominate with 10% YoY growth ($2.96T), reflecting business investment, while real estate loans lag at +2.7% ($5.84T) amid high rates. Consumer loans (+5.1% YoY, $1.93T) show moderate demand, with credit card growth at +4.1% signaling neither distress nor exuberance. The 28/54/18 loan mix indicates cautious business expansion and subdued household leverage.

The 101.2% credit/deposit ratio slightly exceeds the 4-year average (100.7%), showing banks are stretching liquidity to meet loan demand. With Fed Funds at 3.75%, deposit outflows suggest savers are chasing higher yields, but banks remain willing to lend, balancing growth and funding risks in a tight rate environment.
Full Statistics Dashboard
| Metric | Latest Value | Change / Context | Frequency |
|---|---|---|---|
| Data through | October 21, 2026 | Weekly H.8 | |
| Total bank credit | $20.01T | ▲ $28.9B WoW +6.1% YoY | Weekly |
| Total deposits | $19.77T | ▼ $31.7B WoW +7.2% YoY | Weekly |
| Credit cards | $1.10T | ▲ $1.9B WoW +4.1% YoY | Weekly |
| Credit / deposit ratio | 101.2% | 4Y avg: 100.7% | Weekly |
| C&I loans | $2.96T | 27.6% of loans +10.0% YoY | Monthly |
| Real estate loans | $5.84T | 54.5% of loans +2.7% YoY | Monthly |
| Consumer loans | $1.93T | 18.0% of loans +5.1% YoY | Monthly |
| Fed Funds Rate | 3.75% | Monthly | |
| Lending signal | EXPANDING | 13W avg WoW: +$20.4B |
Weekly series through October 21, 2026 (H.8 weekly, SA). Monthly categories through September 2026 — published in same H.8 release with ~6-week lag.
Watch next week’s payrolls and CPI for signals on loan demand sustainability. Credit card growth at 4.1% YoY must be monitored for delinquency cracks. A sustained credit expansion above $25B/week would confirm resilient lending; a drop below $15B could signal tightening.