10Y Inflation Outlook Holds Steady at 2.33%
MarketsFN Data Team
What is a breakeven rate?
The breakeven inflation rate equals the yield gap between a conventional Treasury and a TIPS of the same maturity. If the 10Y nominal yields 4.50% and the 10Y TIPS yields 2.00%, the 10Y breakeven is 2.50% — the level of average CPI at which an investor is indifferent between the two bonds. A higher breakeven signals stronger market inflation expectations.
Why three horizons?
The 5Y breakeven is most sensitive to near-term CPI prints and Fed policy. The 10Y breakeven blends short and long-run expectations. The 5Y/5Y forward looks only at years 5–10, stripping out near-term noise — it is the purest read on whether long-run inflation is anchored. The Fed watches the forward rate most closely.
The Fed's 2% target in breakeven terms
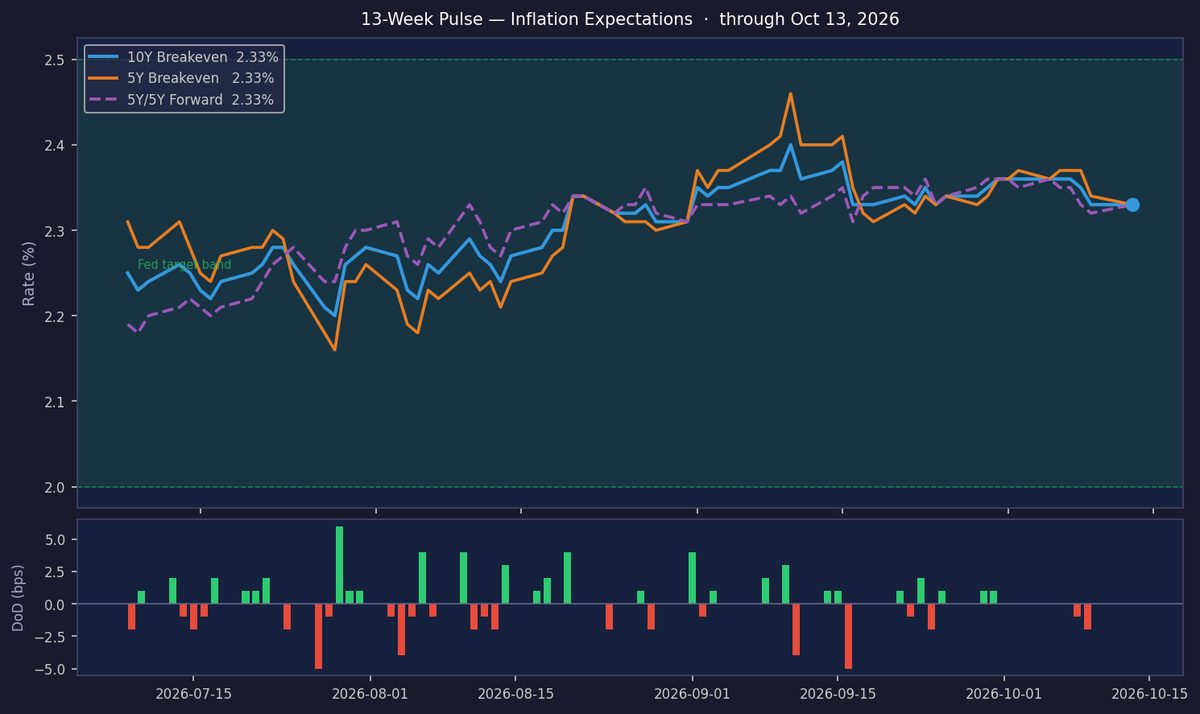
The Federal Reserve targets 2% PCE inflation, not CPI. Because CPI runs roughly 0.3–0.5 pp above PCE (different basket weights and housing costs), breakevens in the 2.2–2.5% range are broadly consistent with the Fed achieving its mandate. Breakevens above 2.5% signal markets doubting that 2% will be delivered; below 2.0% signals deflation or stagnation risk.
Real yields and monetary conditions
The 10Y TIPS yield is the "real" risk-free rate — what investors earn above and beyond inflation. Positive real yields make saving more attractive than spending or risk-taking: a tightening drag on the economy. Negative real yields (common in 2020–2022) were highly stimulative, driving asset prices and compressing credit spreads. The real yield is a direct gauge of monetary restriction.
Inflation expectations remain firmly anchored, with the 10Y breakeven unchanged at 2.33% today, reflecting an ON TARGET regime. The metric has held steady over the past three months, hovering near its 3M average of 2.31%, though it sits in the 69.4th percentile over the last decade, suggesting slightly elevated but stable long-term expectations. Today’s flat daily movement underscores a lack of immediate market catalysts.
The 5Y/5Y forward breakeven at 2.33%—the Fed’s preferred anchoring gauge—remains squarely within the central bank’s comfort zone, with no signs of drift. The absence of a gap between 5Y and 10Y breakevens (+0.0 bps term premium) signals balanced near-term and structural inflation expectations, with no material divergence between shorter and longer horizons. This alignment reinforces confidence in the Fed’s current policy trajectory.

The 10Y real yield of 2.91% reflects restrictive monetary conditions, further underscored by the 6.23% nominal yield. The 332 bps inflation compensation embedded in nominal rates suggests markets are pricing in sustained but manageable inflation. Real yields at these levels imply tight financial conditions, which should continue to weigh on growth-sensitive assets unless inflation softens meaningfully.
A shift from the ON TARGET regime would likely require a breakout in either breakevens or real yields, with the term structure (+0.0 bps) offering no early warnings. Key catalysts include the next CPI print or a hawkish Fed pivot, but for now, the flat term premium and anchored expectations suggest stability. Investors should monitor labor data and energy prices for potential disruptions.
| Series | Latest | DoD | WoW | 10Y Rank | Freq. |
|---|---|---|---|---|---|
| 10Y Breakeven (T10YIE) | 2.33% | +0.0 bps | -3.0 bps | 69.4th pct | Daily |
| 5Y Breakeven (T5YIE) | 2.33% | -1.0 bps | -3.0 bps | 62.5th pct | Daily |
| 5Y/5Y Forward (T5YIFR) | 2.33% | +1.0 bps | — | 86.4th pct | Daily |
| 10Y Real / TIPS (DFII10) | 2.91% | +4.0 bps | — | — | Daily |
| 10Y Nominal (DGS10) | 6.23% | +0.0 bps | +24.0 bps | — | Daily |
| Term Premium (10Y−5Y be) | +0.0 bps | n/a | — | — | Derived |
| CPI YoY | 3.7% YoY (August 2026) | n/a | — | — | Monthly |
| Core PCE YoY | 3.0% YoY (August 2026) | n/a | — | — | Monthly |