10Y Inflation Expectations Steady at 2.33%, Still On Target
MarketsFN Data Team
What is a breakeven rate?
The breakeven inflation rate equals the yield gap between a conventional Treasury and a TIPS of the same maturity. If the 10Y nominal yields 4.50% and the 10Y TIPS yields 2.00%, the 10Y breakeven is 2.50% — the level of average CPI at which an investor is indifferent between the two bonds. A higher breakeven signals stronger market inflation expectations.
Why three horizons?
The 5Y breakeven is most sensitive to near-term CPI prints and Fed policy. The 10Y breakeven blends short and long-run expectations. The 5Y/5Y forward looks only at years 5–10, stripping out near-term noise — it is the purest read on whether long-run inflation is anchored. The Fed watches the forward rate most closely.
The Fed's 2% target in breakeven terms
The Federal Reserve targets 2% PCE inflation, not CPI. Because CPI runs roughly 0.3–0.5 pp above PCE (different basket weights and housing costs), breakevens in the 2.2–2.5% range are broadly consistent with the Fed achieving its mandate. Breakevens above 2.5% signal markets doubting that 2% will be delivered; below 2.0% signals deflation or stagnation risk.
Real yields and monetary conditions
The 10Y TIPS yield is the "real" risk-free rate — what investors earn above and beyond inflation. Positive real yields make saving more attractive than spending or risk-taking: a tightening drag on the economy. Negative real yields (common in 2020–2022) were highly stimulative, driving asset prices and compressing credit spreads. The real yield is a direct gauge of monetary restriction.
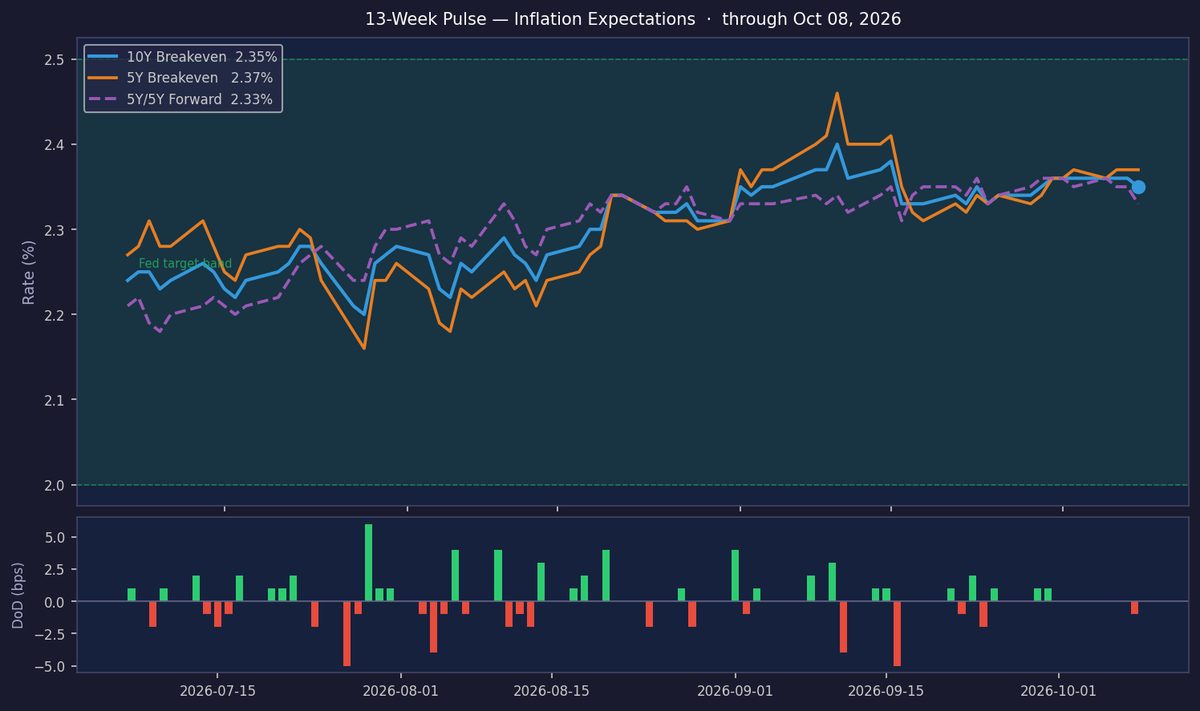
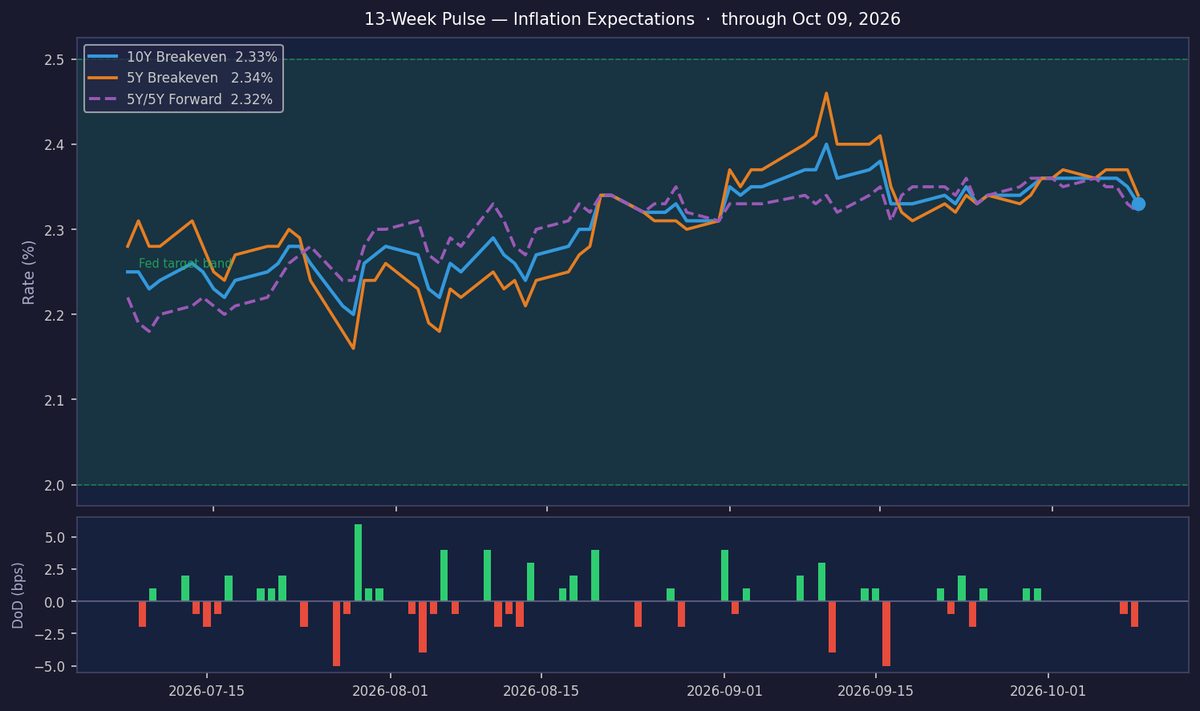
Inflation expectations remain anchored, with the 10-year breakeven rate at 2.33%, reflecting an ON TARGET regime. Today’s slight decline of 2 bps aligns with the modest downtrend observed over the past week, as markets digest recent CPI and core PCE data. The 10-year breakeven continues to trade near its 3-month average, suggesting stability in longer-term inflation pricing.
The 5-year/5-year forward rate at 2.32% remains firmly within the Fed’s comfort zone, indicating well-anchored medium-term expectations. The minimal gap between 5-year and 10-year breakevens (-1 bp) suggests no near-term inflation surge is priced in, reinforcing a structurally stable outlook. This consistency supports the view that inflation risks remain balanced for now.

The 10-year real yield of 2.87% signals restrictive monetary conditions, as it continues to outpace the Fed’s estimated neutral rate. This is further underscored by the nominal 10-year yield at 6.23%, reflecting both inflation expectations and tight policy. The elevated real yield implies financial conditions are weighing on growth, though not excessively so given the ON TARGET inflation regime.
A shift from ON TARGET would likely require a sustained move in breakevens beyond the 2.25-2.50% range or a material change in the term structure, which remains flat (-1 bp term premium). Key catalysts include unexpected labor market strength or energy-driven CPI shocks. For now, the regime appears stable, but vigilance is warranted given elevated real rates.
| Series | Latest | DoD | WoW | 10Y Rank | Freq. |
|---|---|---|---|---|---|
| 10Y Breakeven (T10YIE) | 2.33% | -2.0 bps | -3.0 bps | 69.5th pct | Daily |
| 5Y Breakeven (T5YIE) | 2.34% | -3.0 bps | -3.0 bps | 64.0th pct | Daily |
| 5Y/5Y Forward (T5YIFR) | 2.32% | -1.0 bps | — | 84.0th pct | Daily |
| 10Y Real / TIPS (DFII10) | 2.87% | -5.0 bps | — | — | Daily |
| 10Y Nominal (DGS10) | 6.23% | +0.0 bps | +24.0 bps | — | Daily |
| Term Premium (10Y−5Y be) | -1.0 bps | n/a | — | — | Derived |
| CPI YoY | 3.7% YoY (August 2026) | n/a | — | — | Monthly |
| Core PCE YoY | 3.0% YoY (August 2026) | n/a | — | — | Monthly |