Inflation Expectations Steady at 2.34%, Target Regime Holds
MarketsFN Data Team
What is a breakeven rate?
The breakeven inflation rate equals the yield gap between a conventional Treasury and a TIPS of the same maturity. If the 10Y nominal yields 4.50% and the 10Y TIPS yields 2.00%, the 10Y breakeven is 2.50% — the level of average CPI at which an investor is indifferent between the two bonds. A higher breakeven signals stronger market inflation expectations.
Why three horizons?
The 5Y breakeven is most sensitive to near-term CPI prints and Fed policy. The 10Y breakeven blends short and long-run expectations. The 5Y/5Y forward looks only at years 5–10, stripping out near-term noise — it is the purest read on whether long-run inflation is anchored. The Fed watches the forward rate most closely.
The Fed's 2% target in breakeven terms
The Federal Reserve targets 2% PCE inflation, not CPI. Because CPI runs roughly 0.3–0.5 pp above PCE (different basket weights and housing costs), breakevens in the 2.2–2.5% range are broadly consistent with the Fed achieving its mandate. Breakevens above 2.5% signal markets doubting that 2% will be delivered; below 2.0% signals deflation or stagnation risk.
Real yields and monetary conditions
The 10Y TIPS yield is the "real" risk-free rate — what investors earn above and beyond inflation. Positive real yields make saving more attractive than spending or risk-taking: a tightening drag on the economy. Negative real yields (common in 2020–2022) were highly stimulative, driving asset prices and compressing credit spreads. The real yield is a direct gauge of monetary restriction.
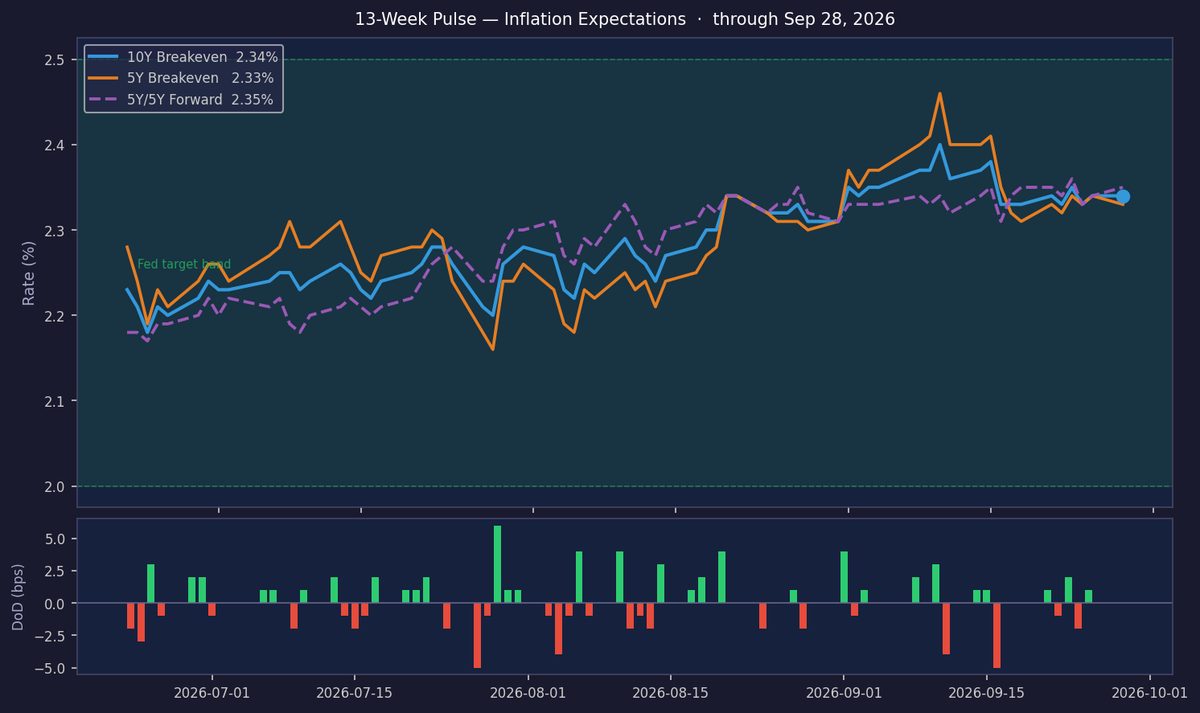
Today’s inflation expectations remain firmly anchored, with the 10Y breakeven unchanged at 2.34%, reflecting an ON TARGET regime. The lack of movement DoD underscores stability, with the metric hovering near its 3-month average and sitting in the 73rd percentile over the past decade. This suggests investors see little near-term risk of inflation deviating from the Fed’s preferred path.
The 5Y/5Y forward at 2.35%—the Fed’s key anchoring gauge—remains comfortably within range, though its 90th percentile level warrants mild vigilance. The negligible gap between 5Y and 10Y breakevens (+1.0 bps term premium) signals neither near-term pressure nor structural shifts, reinforcing the view that inflation expectations are well-contained. For now, the forward curve suggests no imminent drift toward higher or lower inflation.

The 10Y real yield of 2.83% confirms restrictive monetary conditions, as it remains sharply positive and above its long-run equilibrium. Coupled with a 6.23% nominal yield, this implies inflation expectations are tightly managed, with real returns absorbing most of the nominal move. The Fed’s policy stance continues to lean hawkish, though the -2.0 bps DoD dip in real yields hints at marginal easing pressure.
A regime shift from ON TARGET would likely require a sustained move in the 5Y/5Y forward beyond the 2.40% threshold or a breakdown in the term structure. The +1.0 bps term premium offers no immediate signal, but catalysts like a CPI surprise or labor market shock could disrupt the balance. Investors should monitor next week’s PCE print for early signs of drift.
| Series | Latest | DoD | WoW | 10Y Rank | Freq. |
|---|---|---|---|---|---|
| 10Y Breakeven (T10YIE) | 2.34% | +0.0 bps | +0.0 bps | 73.0th pct | Daily |
| 5Y Breakeven (T5YIE) | 2.33% | -1.0 bps | +0.0 bps | 62.9th pct | Daily |
| 5Y/5Y Forward (T5YIFR) | 2.35% | +1.0 bps | — | 90.4th pct | Daily |
| 10Y Real / TIPS (DFII10) | 2.83% | -2.0 bps | — | — | Daily |
| 10Y Nominal (DGS10) | 6.23% | +0.0 bps | +24.0 bps | — | Daily |
| Term Premium (10Y−5Y be) | +1.0 bps | n/a | — | — | Derived |
| CPI YoY | 3.7% YoY (August 2026) | n/a | — | — | Monthly |
| Core PCE YoY | 3.3% YoY (July 2026) | n/a | — | — | Monthly |