HY spreads widen to 293bps as risk-off sentiment builds ahead of key data
MarketsFN Data Team
The Option-Adjusted Spread measures the yield premium a corporate bond pays over a risk-free government bond of the same maturity — after stripping out the value of any embedded options (like call provisions). It isolates pure credit risk compensation. A wider OAS means bond investors demand more yield for holding corporate debt, signalling rising perceived risk. A tighter OAS means confidence in issuers is high and credit conditions are loose.
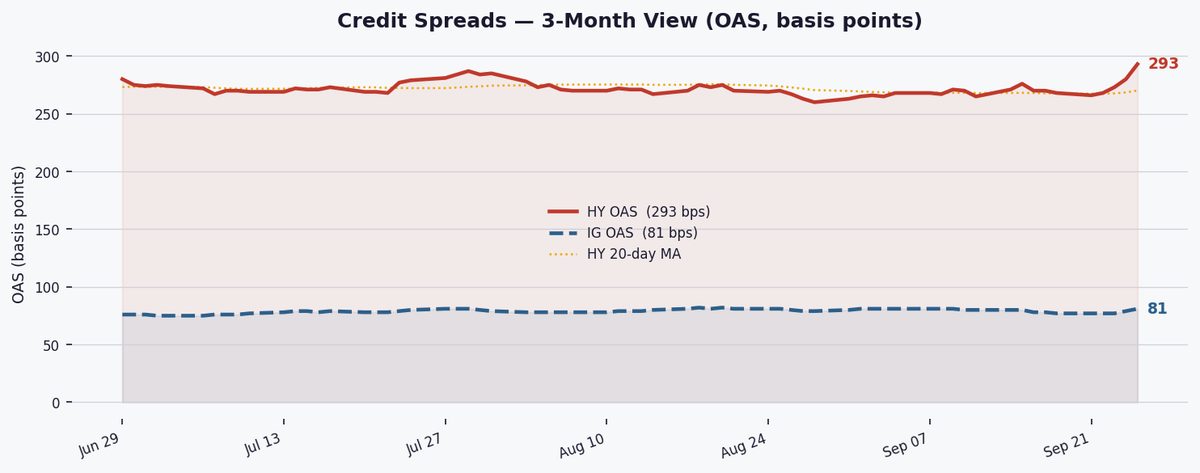
Investment Grade (IG) bonds are rated BBB−/Baa3 or above by S&P/Moody's. They represent large, financially stable companies. IG OAS is currently 81 bps. High Yield (HY) bonds are rated below BBB−/Baa3 — also called "junk bonds" — issued by companies with higher debt loads or less stable cash flows. HY OAS is 293 bps. The HY–IG gap of 212 bps is the market's price for taking extra risk.
When spreads widen (rise), investors are demanding more compensation for credit risk — often because recession fears are rising, corporate earnings are deteriorating, or liquidity is tightening. When spreads tighten (fall), risk appetite is strong: investors are willing to accept less yield premium, usually because the economic outlook is improving. Credit spreads often lead equity markets by days or weeks — they are a leading indicator of financial stress.
Historically, HY OAS has spiked before or during every US recession: ~600 bps in 2001, ~1,900 bps in 2008 (peak), ~900 bps in March 2020. The current HY OAS of 293 bps sits at the 42th percentile of the past 10 years — meaning spreads have been wider than today only 58% of the time. A sustained move above 600 bps would historically mark the threshold of serious credit stress.
US high-yield spreads rose 13bps to 293bps today, extending the week's widening trend (+25bps) amid normal but tightening conditions, signaling growing investor caution ahead of critical economic releases.
High-yield spreads (OAS) climbed to 293bps today, now at the 42nd percentile of their 10-year range (259-461bps), suggesting moderate valuation. The 13bps daily and 25bps weekly widening contrasts with the 20-day MA (270bps) rising above the 60-day MA (272bps), indicating near-term pressure. While still in a NORMAL regime, this tightening direction warrants caution as spreads approach the median (302bps).
Investment-grade spreads edged up 2bps to 81bps (31st percentile), remaining historically tight. The HY-IG differential (212bps) is below its 4-year average (222bps), suggesting muted risk appetite as investors demand less extra yield for HY exposure. This reflects a preference for IG safety despite HY's higher nominal yields.
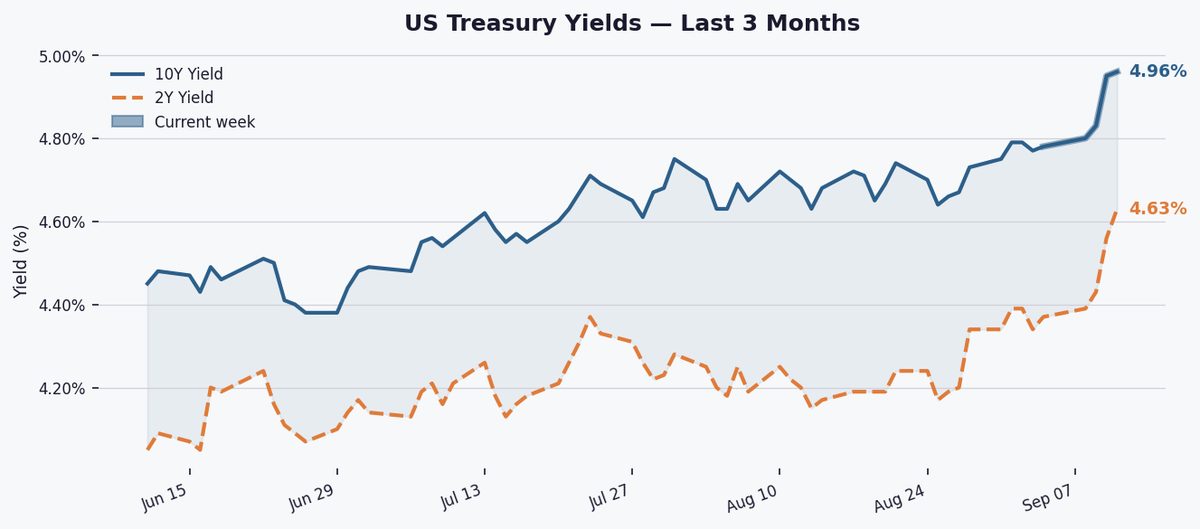
HY effective yields hit 7.87%, offering a 270bps premium over 10Y Treasuries (5.17%). Moody's Baa-Aaa spread (45bps) remains compressed, signaling stable credit conditions. However, elevated HY yields may pressure leveraged issuers, especially those facing refinancing in a higher-for-longer rate environment.

Full Statistics Dashboard
| Metric | Current | Change | Historical Rank |
|---|---|---|---|
| HY OAS (ICE BofA) | 293 bps | ▲ 13 bps DoD ▲ 25 bps WoW | 42th pct |
| IG OAS (ICE BofA) | 81 bps | ▲ 2 bps DoD ▲ 4 bps WoW | 31th pct |
| HY−IG Differential | 212 bps | 4Y avg: 222 bps ▼ 10 bps vs avg | |
| HY Effective Yield | 7.87% | over 10Y: +270 bps | |
| IG Effective Yield | 5.88% | ||
| Moody's Baa Yield | 6.63% | Baa−Aaa: 45 bps | |
| Moody's Aaa Yield | 6.18% | ||
| 10Y Treasury | 5.17% | ||
| SOFR | 3.900% | vs 3M T-Bill: ▼ 34 bps bps | |
| HY OAS Regime | NORMAL | Direction: TIGHTENING (20d MA 270 vs 60d MA 272 bps) | |
| 10Y HY Range | 259–461 bps | median 302 bps |
Funding stress remains low, with the SOFR-T-Bill spread at -34bps, indicating ample liquidity. This benign backdrop is not driving recent spread widening, suggesting moves are risk-sentiment driven rather than a liquidity crunch. Stable funding supports orderly market functioning despite volatility.

Watch Friday's PCE inflation data for Fed policy clues; a hot print could push HY OAS toward 302bps (median), potentially triggering a regime shift. The 300bps level is key psychological resistance—a breach would signal material deterioration in credit conditions.