Inflation Expectations Hold Steady as 10Y Breakeven Dips Slightly
MarketsFN Data Team
What is a breakeven rate?
The breakeven inflation rate equals the yield gap between a conventional Treasury and a TIPS of the same maturity. If the 10Y nominal yields 4.50% and the 10Y TIPS yields 2.00%, the 10Y breakeven is 2.50% — the level of average CPI at which an investor is indifferent between the two bonds. A higher breakeven signals stronger market inflation expectations.
Why three horizons?
The 5Y breakeven is most sensitive to near-term CPI prints and Fed policy. The 10Y breakeven blends short and long-run expectations. The 5Y/5Y forward looks only at years 5–10, stripping out near-term noise — it is the purest read on whether long-run inflation is anchored. The Fed watches the forward rate most closely.
The Fed's 2% target in breakeven terms
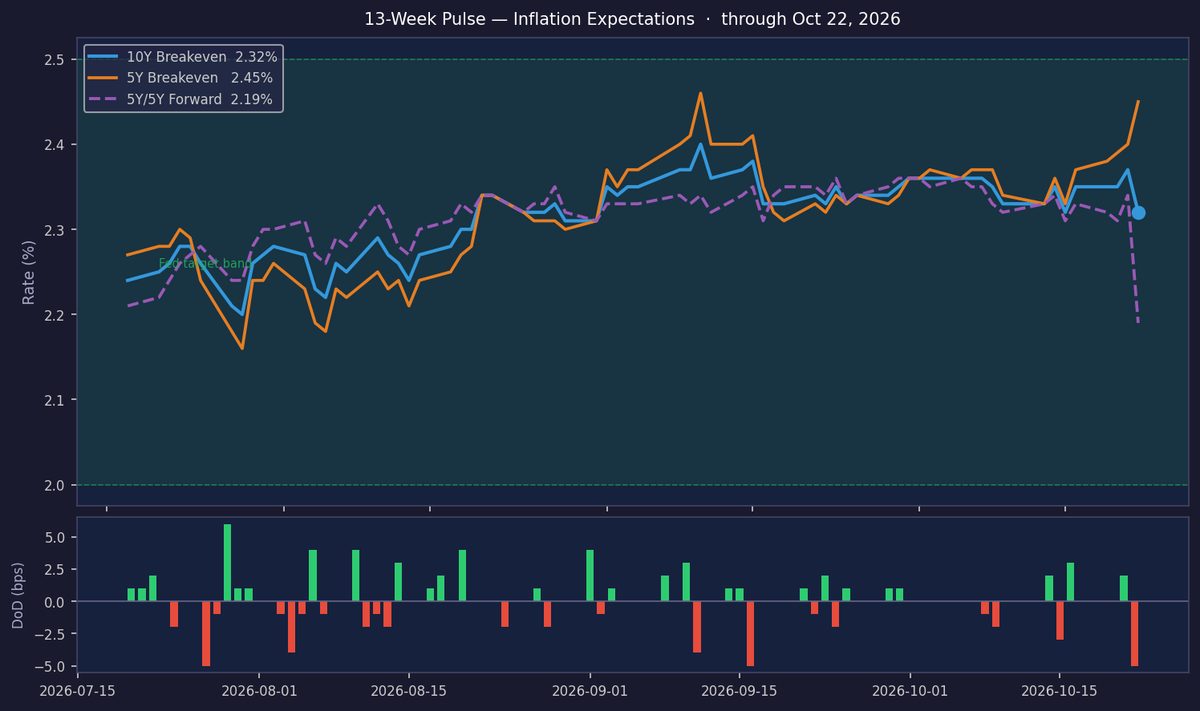
The Federal Reserve targets 2% PCE inflation, not CPI. Because CPI runs roughly 0.3–0.5 pp above PCE (different basket weights and housing costs), breakevens in the 2.2–2.5% range are broadly consistent with the Fed achieving its mandate. Breakevens above 2.5% signal markets doubting that 2% will be delivered; below 2.0% signals deflation or stagnation risk.
Real yields and monetary conditions
The 10Y TIPS yield is the "real" risk-free rate — what investors earn above and beyond inflation. Positive real yields make saving more attractive than spending or risk-taking: a tightening drag on the economy. Negative real yields (common in 2020–2022) were highly stimulative, driving asset prices and compressing credit spreads. The real yield is a direct gauge of monetary restriction.
This week’s inflation expectations held steady, with the 10Y breakeven unchanged at 2.32%, firmly in the ON TARGET regime and at the 66.7th percentile over the past decade. Today’s 5.0 bps drop in the 10Y breakeven reflects mild demand for inflation protection, though the 5Y breakeven rose 5.0 bps, suggesting near-term uncertainty. The stability in longer-term expectations signals confidence in the Fed’s ability to maintain inflation near target, but next week’s data could test this resolve.
The 5Y/5Y forward rate fell 15.0 bps to 2.19%, slightly below its 3-month average and near the 50th percentile historically. While this suggests medium-term expectations remain anchored, the week’s volatility—particularly the 12.0 bps WoW rise in the 5Y breakeven—warrants monitoring for signs of drift. The Fed will likely view the current level as acceptable but may grow cautious if the forward rate diverges further from its 2.32% average.

The 10Y real yield of 2.76% remains firmly restrictive, reflecting tight monetary policy amid elevated nominal yields (6.23%). The 347 bps inflation compensation embedded in nominal yields aligns with the Fed’s hawkish stance, though the modest decline in real yields this week hints at easing financial conditions. This dynamic suggests the economy is absorbing higher rates without acute stress, but the gap between real and nominal yields underscores persistent inflation risks.
Next week’s focus includes the Q3 GDP advance estimate and September PCE data, which will test the term structure’s flatness (term premium at -13.0 bps). Fed speakers, including Chair Waller, could clarify whether recent inflation trends justify patience or warrant renewed hawkishness. Watch for shifts in the 5Y/5Y forward and 10Y breakeven to gauge whether anchoring holds or erodes further.
| Series | Latest | DoD | WoW | 10Y Rank | Freq. |
|---|---|---|---|---|---|
| 10Y Breakeven (T10YIE) | 2.32% | -5.0 bps | +0.0 bps | 66.7th pct | Daily |
| 5Y Breakeven (T5YIE) | 2.45% | +5.0 bps | +12.0 bps | 76.3th pct | Daily |
| 5Y/5Y Forward (T5YIFR) | 2.19% | -15.0 bps | — | 49.9th pct | Daily |
| 10Y Real / TIPS (DFII10) | 2.76% | -1.0 bps | — | — | Daily |
| 10Y Nominal (DGS10) | 6.23% | +0.0 bps | +24.0 bps | — | Daily |
| Term Premium (10Y−5Y be) | -13.0 bps | n/a | — | — | Derived |
| CPI YoY | 4.0% YoY (September 2026) | n/a | — | — | Monthly |
| Core PCE YoY | 3.0% YoY (August 2026) | n/a | — | — | Monthly |