HY spreads widen to 315 bps as credit markets digest mixed risk appetite
MarketsFN Data Team
The Option-Adjusted Spread measures the yield premium a corporate bond pays over a risk-free government bond of the same maturity — after stripping out the value of any embedded options (like call provisions). It isolates pure credit risk compensation. A wider OAS means bond investors demand more yield for holding corporate debt, signalling rising perceived risk. A tighter OAS means confidence in issuers is high and credit conditions are loose.
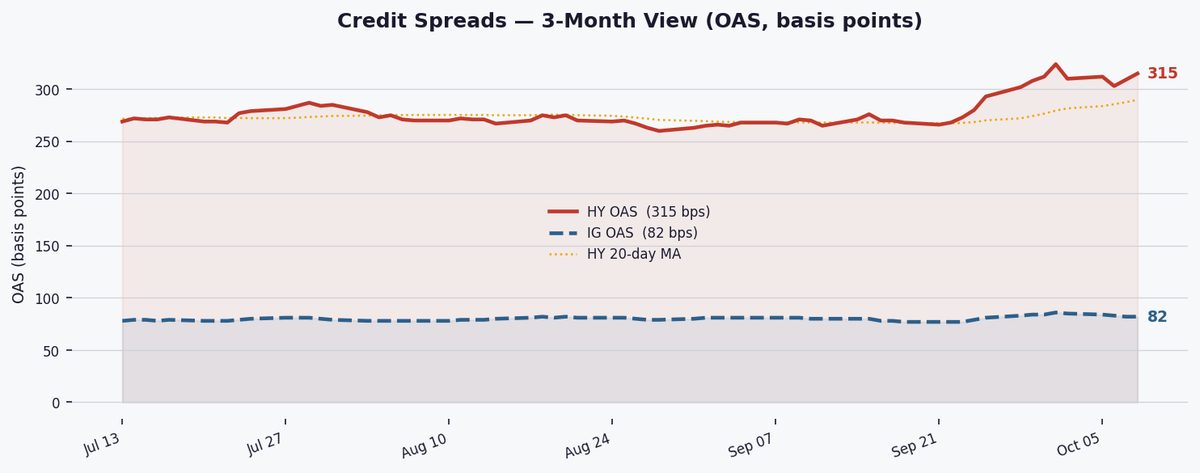
Investment Grade (IG) bonds are rated BBB−/Baa3 or above by S&P/Moody's. They represent large, financially stable companies. IG OAS is currently 82 bps. High Yield (HY) bonds are rated below BBB−/Baa3 — also called "junk bonds" — issued by companies with higher debt loads or less stable cash flows. HY OAS is 315 bps. The HY–IG gap of 233 bps is the market's price for taking extra risk.
When spreads widen (rise), investors are demanding more compensation for credit risk — often because recession fears are rising, corporate earnings are deteriorating, or liquidity is tightening. When spreads tighten (fall), risk appetite is strong: investors are willing to accept less yield premium, usually because the economic outlook is improving. Credit spreads often lead equity markets by days or weeks — they are a leading indicator of financial stress.
Historically, HY OAS has spiked before or during every US recession: ~600 bps in 2001, ~1,900 bps in 2008 (peak), ~900 bps in March 2020. The current HY OAS of 315 bps sits at the 62th percentile of the past 10 years — meaning spreads have been wider than today only 38% of the time. A sustained move above 600 bps would historically mark the threshold of serious credit stress.
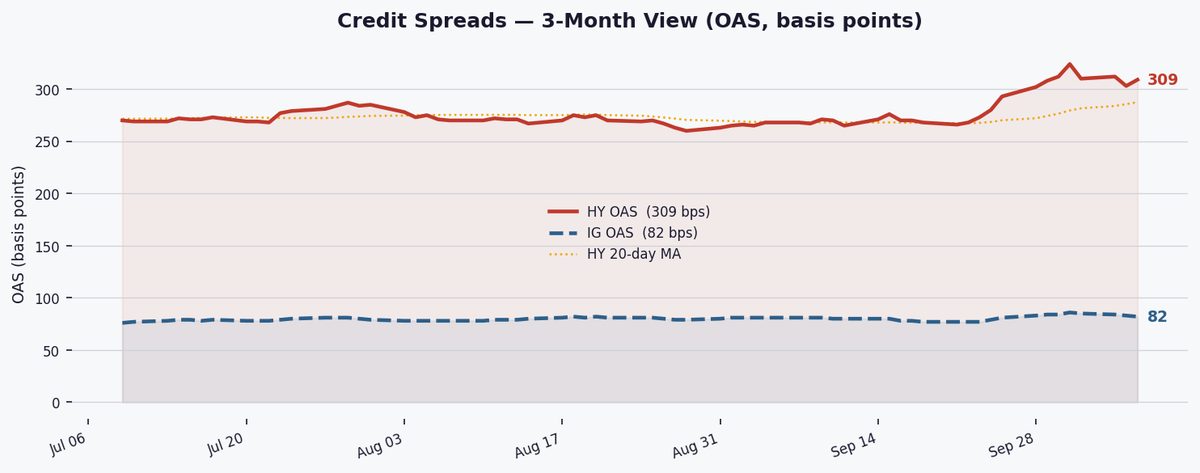
High-yield spreads rose 6 bps to 315 bps today, remaining in a NORMAL regime but extending a widening trend, signaling cautious investor sentiment amid elevated Treasury yields and corporate refinancing concerns.
The ICE BofA HY OAS widened 6 bps to 315 bps today, though remains 9 bps tighter on the week. At the 62nd percentile over 10 years, spreads sit above the 20/60-day MAs (290/278 bps), suggesting recent underperformance. The NORMAL regime implies neither extreme value nor distress, but the widening direction warrants monitoring given median historical OAS is 302 bps. HY's 8.11% yield may attract selective buyers if spreads stabilize.
IG spreads held flat at 82 bps (39th percentile), maintaining their 4 bps weekly tightening. The HY-IG differential of 233 bps sits slightly above its 221 bps 4-year average, indicating modest but not aggressive risk appetite. Investors appear balanced, with IG's 5.94% yield offering adequate compensation without stretching into HY's volatility. The differential suggests no panic, but no rush into risk either.
HY's 8.11% yield offers a 289 bps pickup over 10Y Treasuries (5.22%), while Moody's Baa-Aaa spread of 45 bps reflects moderate quality differentiation. These levels pressure leveraged borrowers, especially with SOFR at 3.87% compounding refinancing costs. The HY yield's 8%+ threshold may cap new issuance unless spreads tighten from here.

Full Statistics Dashboard
| Metric | Current | Change | Historical Rank |
|---|---|---|---|
| HY OAS (ICE BofA) | 315 bps | ▲ 6 bps DoD ▼ 9 bps WoW | 62th pct |
| IG OAS (ICE BofA) | 82 bps | ▼ 0 bps DoD ▼ 4 bps WoW | 39th pct |
| HY−IG Differential | 233 bps | 4Y avg: 221 bps ▲ 12 bps vs avg | |
| HY Effective Yield | 8.11% | over 10Y: +289 bps | |
| IG Effective Yield | 5.94% | ||
| Moody's Baa Yield | 6.70% | Baa−Aaa: 45 bps | |
| Moody's Aaa Yield | 6.25% | ||
| 10Y Treasury | 5.22% | ||
| SOFR | 3.870% | vs 3M T-Bill: ▼ 36 bps bps | |
| HY OAS Regime | NORMAL | Direction: WIDENING (20d MA 290 vs 60d MA 278 bps) | |
| 10Y HY Range | 259–461 bps | median 302 bps |
The SOFR-T-Bill spread at -36 bps shows money markets remain loose, with bills yielding more than repo. This lack of funding stress is preventing HY/IG spreads from blowing out further, but the -36 bps inversion suggests abundant liquidity isn't driving spread compression either. Neutral funding conditions leave credit moves to macro forces.

Watch Thursday's CPI and Friday's retail sales for Treasury yield cues that could accelerate HY moves. A sustained break above 330 bps (10Y 70th percentile) may shift HY to a WARNING regime, while a drop below 290 bps (20-day MA) could signal renewed risk appetite. IG's 80 bps level remains a psychological anchor.