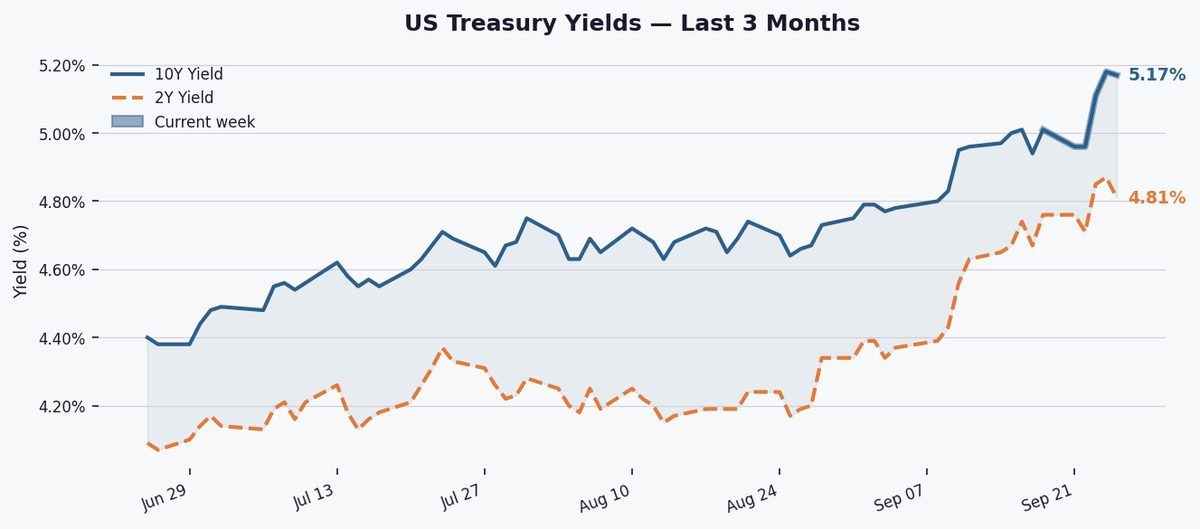
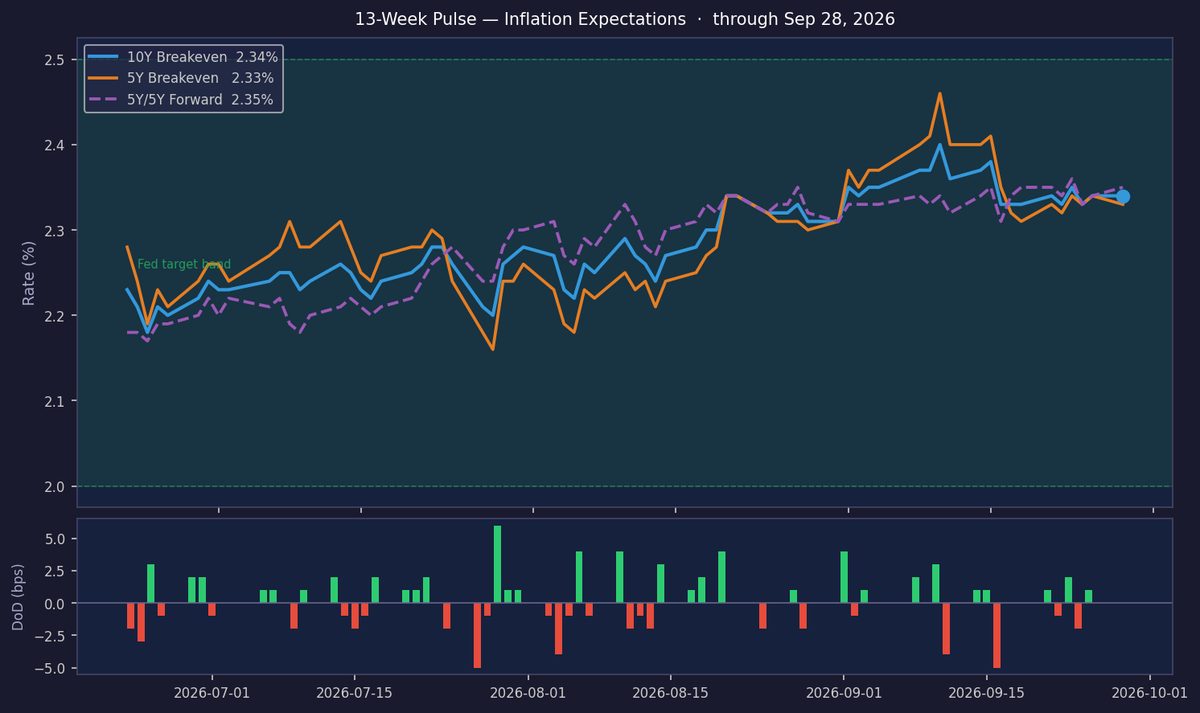
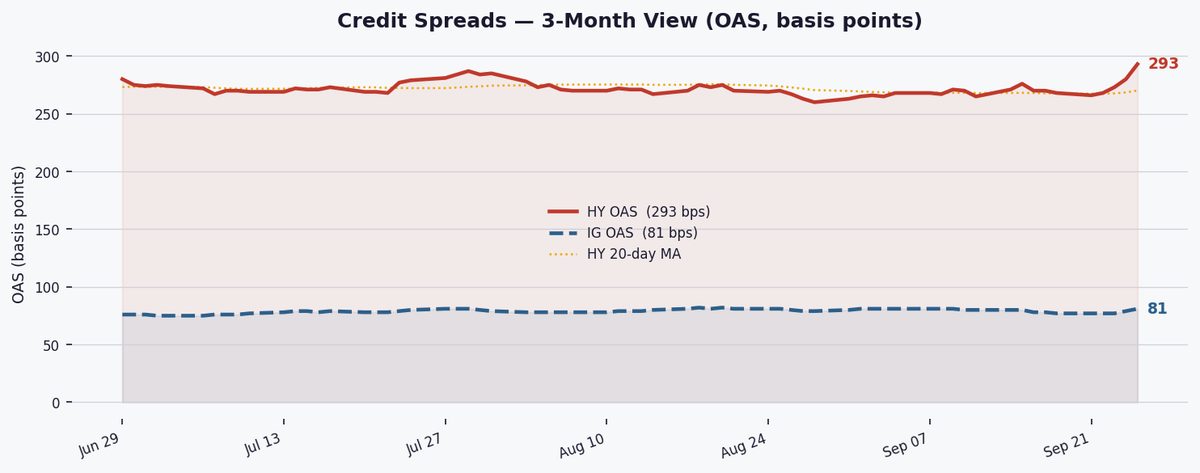
HY spreads widen to 308 bps as credit stress builds amid rising yields
MarketsFN Data Team
The Option-Adjusted Spread measures the yield premium a corporate bond pays over a risk-free government bond of the same maturity — after stripping out the value of any embedded options (like call provisions). It isolates pure credit risk compensation. A wider OAS means bond investors demand more yield for holding corporate debt, signalling rising perceived risk. A tighter OAS means confidence in issuers is high and credit conditions are loose.
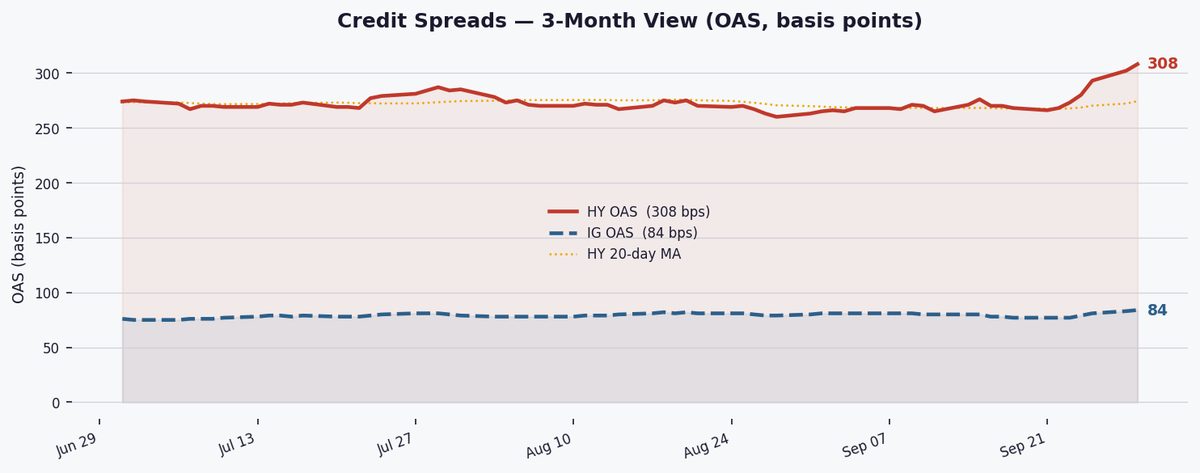
Investment Grade (IG) bonds are rated BBB−/Baa3 or above by S&P/Moody's. They represent large, financially stable companies. IG OAS is currently 84 bps. High Yield (HY) bonds are rated below BBB−/Baa3 — also called "junk bonds" — issued by companies with higher debt loads or less stable cash flows. HY OAS is 308 bps. The HY–IG gap of 224 bps is the market's price for taking extra risk.
When spreads widen (rise), investors are demanding more compensation for credit risk — often because recession fears are rising, corporate earnings are deteriorating, or liquidity is tightening. When spreads tighten (fall), risk appetite is strong: investors are willing to accept less yield premium, usually because the economic outlook is improving. Credit spreads often lead equity markets by days or weeks — they are a leading indicator of financial stress.
Historically, HY OAS has spiked before or during every US recession: ~600 bps in 2001, ~1,900 bps in 2008 (peak), ~900 bps in March 2020. The current HY OAS of 308 bps sits at the 53th percentile of the past 10 years — meaning spreads have been wider than today only 47% of the time. A sustained move above 600 bps would historically mark the threshold of serious credit stress.
High-yield spreads rose 6 bps to 308 bps today, extending a 40 bps weekly widening in NORMAL regime, signaling growing investor caution as Treasury yields pressure leveraged borrowers.
High-yield spreads sit at 308 bps, in the 53rd percentile of 10-year ranges, suggesting middling valuation. The 6 bps daily and 40 bps weekly widening reflects mounting stress, with the 20-day MA (274 bps) now diverging sharply from the 60-day MA (273 bps), indicating short-term bearish momentum. While still in NORMAL regime, the trend warns of potential further deterioration if macro conditions worsen.
Investment-grade spreads edged up 1 bps to 84 bps (47th percentile), far calmer than HY turbulence. The HY-IG differential of 224 bps slightly exceeds its 4-year average (221 bps), suggesting modest risk aversion but no flight to safety — investors aren’t yet abandoning HY for IG’s stability.
HY yields hit 8.08%, offering a 282 bps premium over 10Y Treasuries (5.26%), but Moody’s Baa-Aaa spread of 45 bps shows tight quality differentiation. Elevated yields signal rising refinancing costs, particularly for lower-rated issuers, with HY now testing levels that could trigger distress in leveraged balance sheets.

Full Statistics Dashboard
| Metric | Current | Change | Historical Rank |
|---|---|---|---|
| HY OAS (ICE BofA) | 308 bps | ▲ 6 bps DoD ▲ 40 bps WoW | 53th pct |
| IG OAS (ICE BofA) | 84 bps | ▲ 1 bps DoD ▲ 7 bps WoW | 47th pct |
| HY−IG Differential | 224 bps | 4Y avg: 221 bps ▲ 3 bps vs avg | |
| HY Effective Yield | 8.08% | over 10Y: +282 bps | |
| IG Effective Yield | 5.97% | ||
| Moody's Baa Yield | 6.72% | Baa−Aaa: 45 bps | |
| Moody's Aaa Yield | 6.27% | ||
| 10Y Treasury | 5.26% | ||
| SOFR | 3.880% | vs 3M T-Bill: ▼ 37 bps bps | |
| HY OAS Regime | NORMAL | Direction: WIDENING (20d MA 274 vs 60d MA 273 bps) | |
| 10Y HY Range | 259–461 bps | median 302 bps |
Funding stress remains muted, with SOFR (3.88%) below 3M T-bills (4.25%), a -37 bps spread indicating loose repo conditions. This lack of banking-sector strain is dampening HY/IG volatility, but widening credit spreads could tighten funding if lenders grow wary.

Watch Friday’s payrolls data for wage inflation signals that could push Treasury yields higher, exacerbating HY stress. A breach of 325 bps (HY OAS) would likely shift the regime from NORMAL to WIDE, reflecting systemic credit concerns.