10Y Breakeven Holds Steady at 2.32% Amid On-Target Inflation
MarketsFN Data Team
What is a breakeven rate?
The breakeven inflation rate equals the yield gap between a conventional Treasury and a TIPS of the same maturity. If the 10Y nominal yields 4.50% and the 10Y TIPS yields 2.00%, the 10Y breakeven is 2.50% — the level of average CPI at which an investor is indifferent between the two bonds. A higher breakeven signals stronger market inflation expectations.
Why three horizons?
The 5Y breakeven is most sensitive to near-term CPI prints and Fed policy. The 10Y breakeven blends short and long-run expectations. The 5Y/5Y forward looks only at years 5–10, stripping out near-term noise — it is the purest read on whether long-run inflation is anchored. The Fed watches the forward rate most closely.
The Fed's 2% target in breakeven terms
The Federal Reserve targets 2% PCE inflation, not CPI. Because CPI runs roughly 0.3–0.5 pp above PCE (different basket weights and housing costs), breakevens in the 2.2–2.5% range are broadly consistent with the Fed achieving its mandate. Breakevens above 2.5% signal markets doubting that 2% will be delivered; below 2.0% signals deflation or stagnation risk.
Real yields and monetary conditions
The 10Y TIPS yield is the "real" risk-free rate — what investors earn above and beyond inflation. Positive real yields make saving more attractive than spending or risk-taking: a tightening drag on the economy. Negative real yields (common in 2020–2022) were highly stimulative, driving asset prices and compressing credit spreads. The real yield is a direct gauge of monetary restriction.
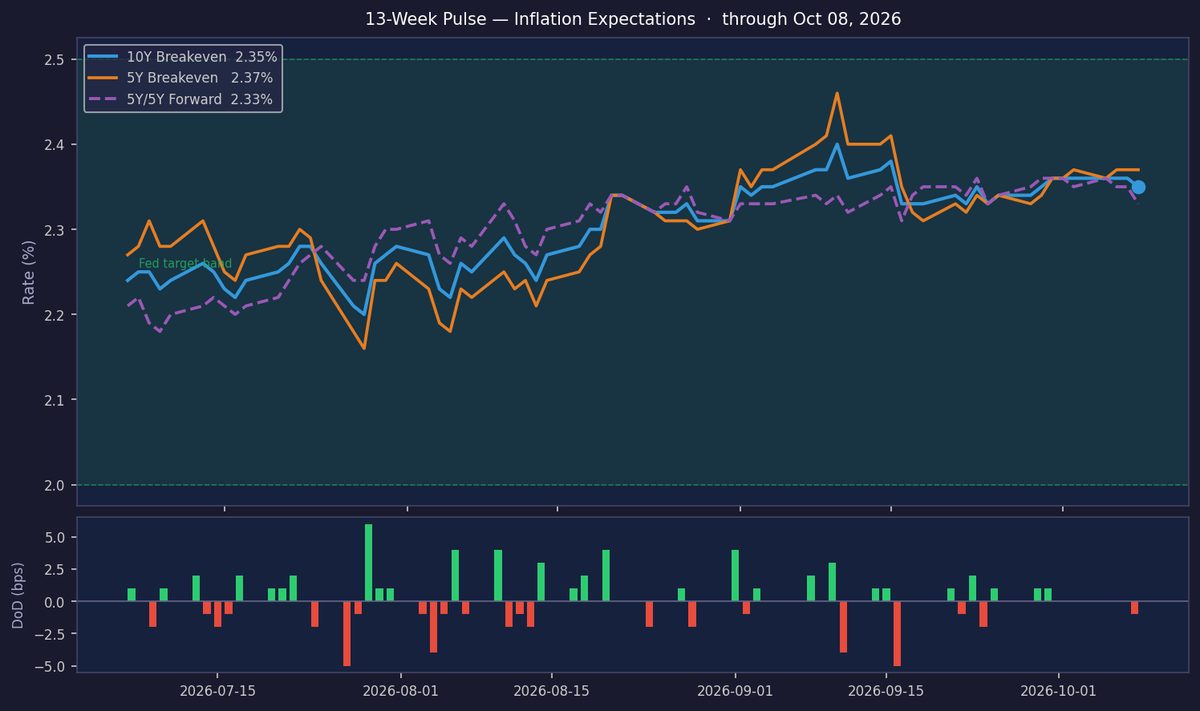
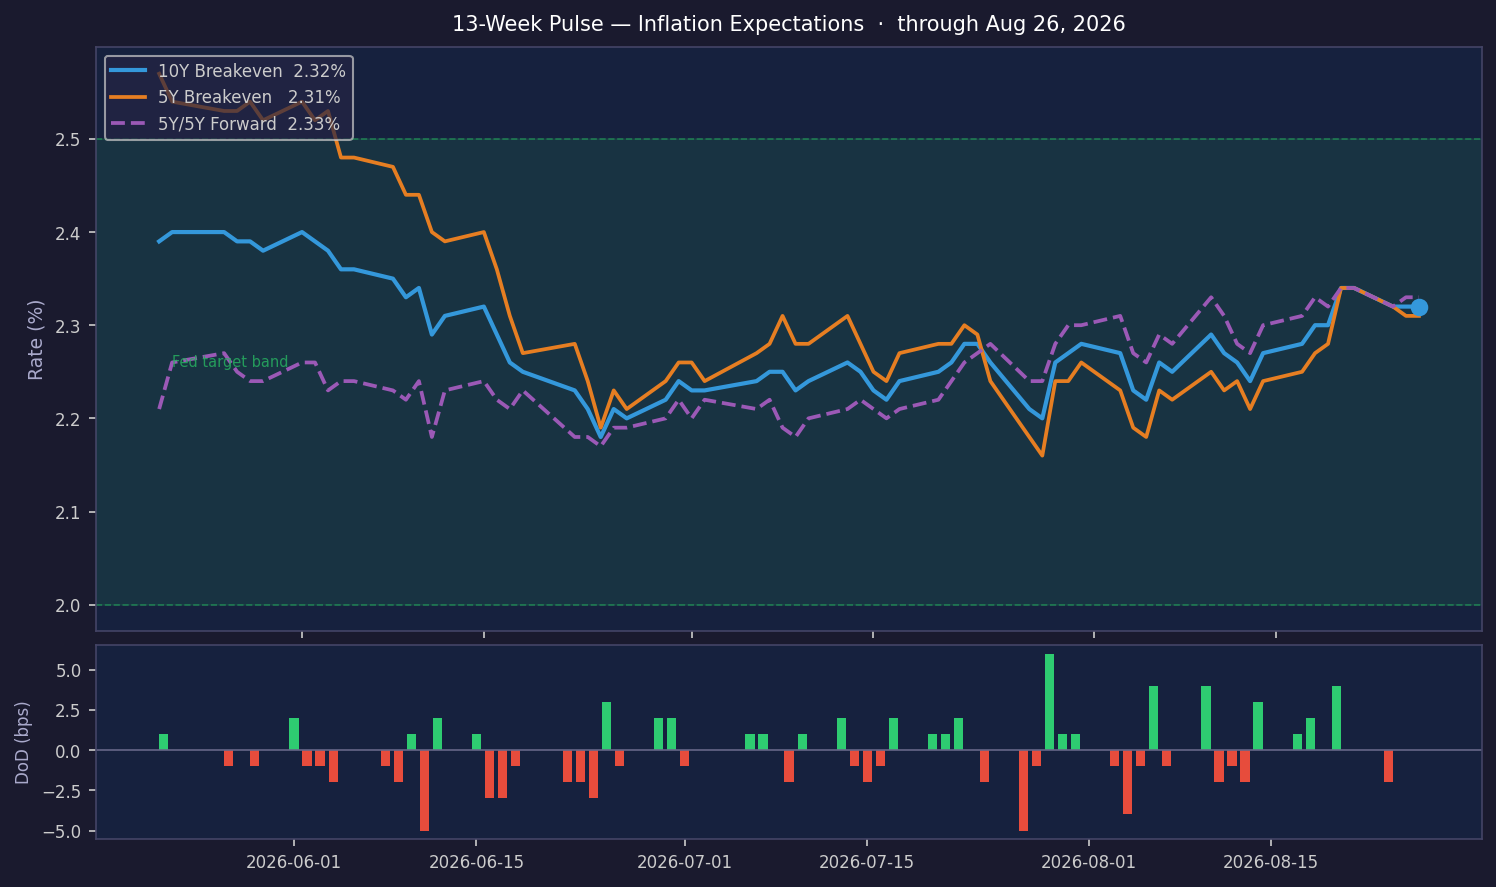
Inflation expectations remain firmly anchored, with the 10-year breakeven rate holding steady at 2.32% amid an ON TARGET regime. Today’s flat daily movement reflects muted market reactions to recent data, though the 3-month average continues to edge higher. The 10-year breakeven now sits at the 68th percentile of its decade-long range, signaling persistent but contained inflation pressure.
The 5Y/5Y forward breakeven at 2.33% remains near the upper end of the Fed’s comfort zone, though its 87th percentile ranking suggests elevated but stable long-term anchoring. The negligible 1 bp gap between 5Y and 10Y breakevens points to balanced near-term and structural inflation expectations, with no clear skew toward overheating or disinflation.

The 10-year real yield of 2.32% indicates restrictive monetary conditions, reinforced by the 6.23% nominal yield—a 391 bp inflation premium. This tightness aligns with the Fed’s higher-for-longer stance, though the 6 bp drop in real yields today hints at slight easing pressure, possibly reflecting softer growth signals.
A regime shift from ON TARGET would likely require a sustained move in the 5Y/5Y forward above 2.40% or a breakdown in the term structure (currently +1 bp). Watch for July PCE revisions or labor market surprises as near-term catalysts, but the flat term premium suggests no imminent stress in inflation expectations.
| Series | Latest | DoD | WoW | 10Y Rank | Freq. |
|---|---|---|---|---|---|
| 10Y Breakeven (T10YIE) | 2.32% | +0.0 bps | +2.0 bps | 68.2th pct | Daily |
| 5Y Breakeven (T5YIE) | 2.31% | +0.0 bps | +3.0 bps | 61.1th pct | Daily |
| 5Y/5Y Forward (T5YIFR) | 2.33% | +0.0 bps | — | 87.4th pct | Daily |
| 10Y Real / TIPS (DFII10) | 2.32% | -6.0 bps | — | — | Daily |
| 10Y Nominal (DGS10) | 6.23% | +0.0 bps | +24.0 bps | — | Daily |
| Term Premium (10Y−5Y be) | +1.0 bps | n/a | — | — | Derived |
| CPI YoY | 3.5% YoY (July 2026) | n/a | — | — | Monthly |
| Core PCE YoY | 3.3% YoY (July 2026) | n/a | — | — | Monthly |