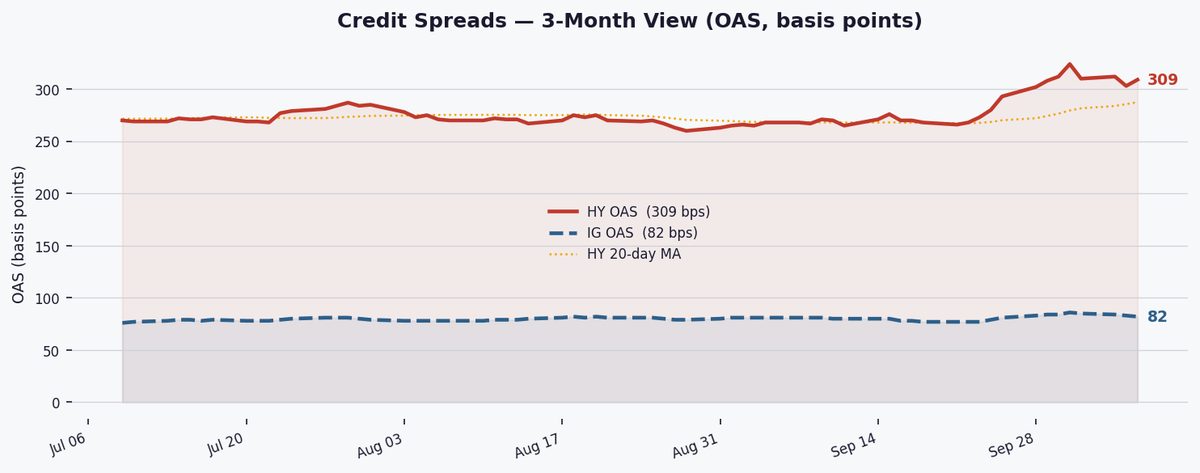
HY spreads widen to 309 bps amid mixed risk sentiment, holding near 10-year median
MarketsFN Data Team
The Option-Adjusted Spread measures the yield premium a corporate bond pays over a risk-free government bond of the same maturity — after stripping out the value of any embedded options (like call provisions). It isolates pure credit risk compensation. A wider OAS means bond investors demand more yield for holding corporate debt, signalling rising perceived risk. A tighter OAS means confidence in issuers is high and credit conditions are loose.
Investment Grade (IG) bonds are rated BBB−/Baa3 or above by S&P/Moody's. They represent large, financially stable companies. IG OAS is currently 82 bps. High Yield (HY) bonds are rated below BBB−/Baa3 — also called "junk bonds" — issued by companies with higher debt loads or less stable cash flows. HY OAS is 309 bps. The HY–IG gap of 227 bps is the market's price for taking extra risk.
When spreads widen (rise), investors are demanding more compensation for credit risk — often because recession fears are rising, corporate earnings are deteriorating, or liquidity is tightening. When spreads tighten (fall), risk appetite is strong: investors are willing to accept less yield premium, usually because the economic outlook is improving. Credit spreads often lead equity markets by days or weeks — they are a leading indicator of financial stress.
Historically, HY OAS has spiked before or during every US recession: ~600 bps in 2001, ~1,900 bps in 2008 (peak), ~900 bps in March 2020. The current HY OAS of 309 bps sits at the 54th percentile of the past 10 years — meaning spreads have been wider than today only 46% of the time. A sustained move above 600 bps would historically mark the threshold of serious credit stress.
US high-yield spreads rose 6 bps to 309 bps (54th percentile) in a NORMAL regime, signaling cautious risk appetite as the 20-day MA (288 bps) diverges from the 60-day MA (277 bps), testing recent stability.
High-yield spreads sit at 309 bps (54th percentile), up 6 bps DoD but down 3 bps WoW, hovering near the 10-year median (302 bps). The 20-day MA (288 bps) pulling away from the 60-day MA (277 bps) suggests short-term widening pressure, though the NORMAL regime neither flags acute stress nor clear opportunity. Investors weigh the 8.08% effective yield against widening momentum.
Investment-grade spreads tightened 1 bp to 82 bps (39th percentile), with the HY-IG differential at 227 bps vs its 4-year average (221 bps). The modest gap implies balanced risk appetite — no rush into HY’s extra yield, but no flight to IG safety either. IG’s 5.98% yield remains palatable for quality-seeking capital.
HY yields (8.08%) offer a 280 bp premium over 10Y Treasuries (5.28%), while Moody’s Baa-Aaa spread (48 bps) shows stable credit-tier demand. At 6.74%, Baa yields pressure leveraged borrowers’ refinancing costs, though still below 2022-23 peaks. HY’s 8%+ yield may attract selective buyers if spreads stabilize.

Full Statistics Dashboard
| Metric | Current | Change | Historical Rank |
|---|---|---|---|
| HY OAS (ICE BofA) | 309 bps | ▲ 6 bps DoD ▼ 3 bps WoW | 54th pct |
| IG OAS (ICE BofA) | 82 bps | ▼ 1 bps DoD ▼ 2 bps WoW | 39th pct |
| HY−IG Differential | 227 bps | 4Y avg: 221 bps ▲ 6 bps vs avg | |
| HY Effective Yield | 8.08% | over 10Y: +280 bps | |
| IG Effective Yield | 5.98% | ||
| Moody's Baa Yield | 6.74% | Baa−Aaa: 48 bps | |
| Moody's Aaa Yield | 6.26% | ||
| 10Y Treasury | 5.28% | ||
| SOFR | 3.880% | vs 3M T-Bill: ▼ 34 bps bps | |
| HY OAS Regime | NORMAL | Direction: WIDENING (20d MA 288 vs 60d MA 277 bps) | |
| 10Y HY Range | 259–461 bps | median 302 bps |
The SOFR-T-Bill spread (-34 bps) indicates loose funding, with SOFR (3.88%) below 3M bills (4.22%). This benign backdrop dampens volatility but offers little impetus for spread compression. Banks face low stress, allowing credit moves to reflect fundamental views rather than liquidity constraints.

Watch next week’s CPI and retail sales data for shifts in Fed pricing; a break above 330 bps (HY OAS) could signal a WARNING regime. The 60-day MA (277 bps) remains key support — a sustained breach may trigger technical selling.