European Markets Mixed: DAX Up 0.33% — Stability Amidst Minor Fluctuations.
MarketsFN Team
European markets approaching close (still trading) • US markets actively trading • Analysis based on last 8 hours
📊 Market Overview
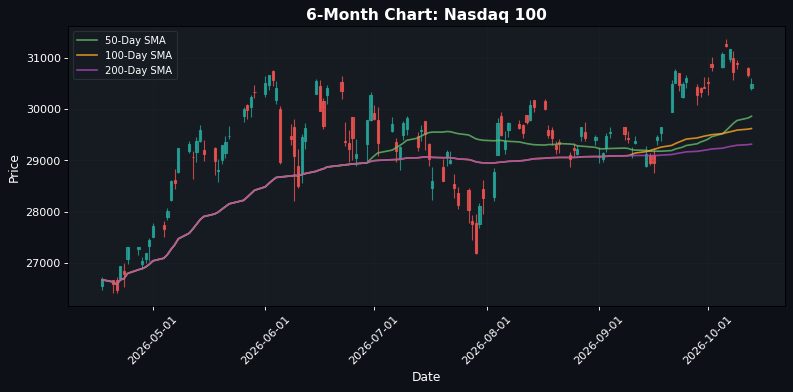
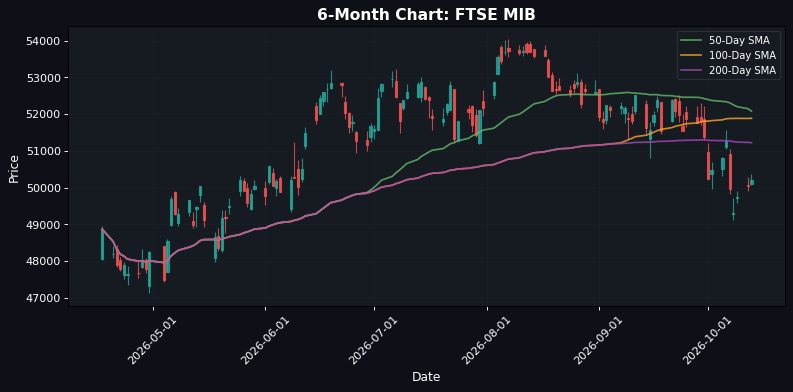
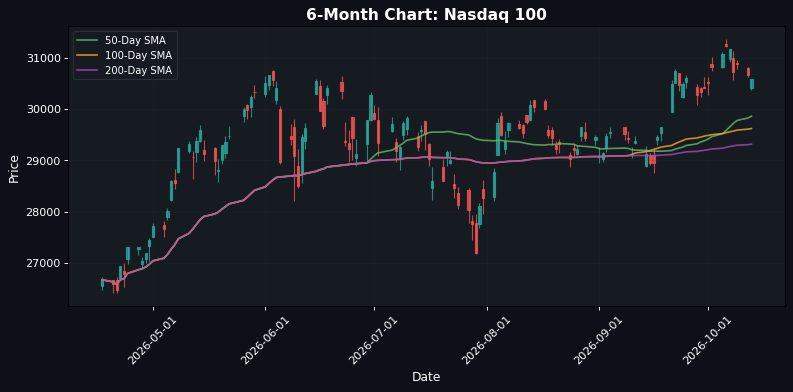
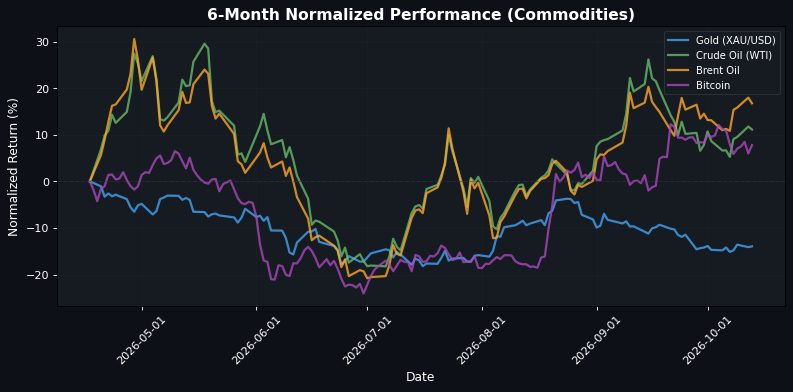
**European Markets Show Resilience Amid Mixed Global Sentiment** As European markets approach the close, a notable divergence is evident, with the DAX leading the pack, up +0.33% at 25,362.29, while the EuroStoxx 50 slips slightly, down -0.11% at 6,194.08. The FTSE 100 and FTSE MIB also reflect positive momentum, gaining +0.29% to 10,686.91 and +0.35% to 50,211.59, respectively. This mixed performance suggests that while some indices are buoyed by local factors, broader market sentiment remains cautious. In the US, the S&P 500 is flat at 7,807.44, indicating a wait-and-see approach from investors as they digest recent economic data. The Dow Jones is slightly up +0.06% at 51,880.91, while the Nasdaq 100 lags behind, down -0.29% at 30,575.33, reflecting ongoing concerns about tech valuations amid rising interest rates. In the FX market, the euro is gaining ground against the dollar, trading at 1.1191, up +0.30%, which may be supporting European equities. Conversely, crude oil prices are under pressure, with WTI down -0.58% at $93.20 and Brent down -1.03% at $105.55, likely impacting energy stocks and overall market sentiment. The dominant theme today is the resilience of European indices despite global headwinds, particularly in tech-heavy US markets. Investors may be underpricing the potential for European economic recovery, especially as the ECB signals a commitment to maintaining accommodative policies. Looking ahead, the upcoming US inflation data will be a critical catalyst, as it could significantly influence market direction and investor sentiment, particularly in relation to interest rate expectations.
🇪🇺 European Markets (Approaching Close)
| Name | Price | Daily (%) |
|---|---|---|
| EuroStoxx 50 | 6194.08 | -0.11% |
| DAX | 25362.29 | +0.33% |
| FTSE 100 | 10686.91 | +0.29% |
| CAC 40 | 7839.99 | +0.09% |
| FTSE MIB | 50211.59 | +0.35% |
| IBEX 35 | 19284.40 | -0.01% |
🇺🇸 US Markets (Currently Active)
| Name | Price | Daily (%) |
|---|---|---|
| S&P 500 | 7807.44 | +0.00% |
| Dow Jones | 51880.91 | +0.06% |
| Nasdaq 100 | 30575.33 | -0.29% |
🌏 Asian Markets
| Name | Price | Daily (%) |
|---|---|---|
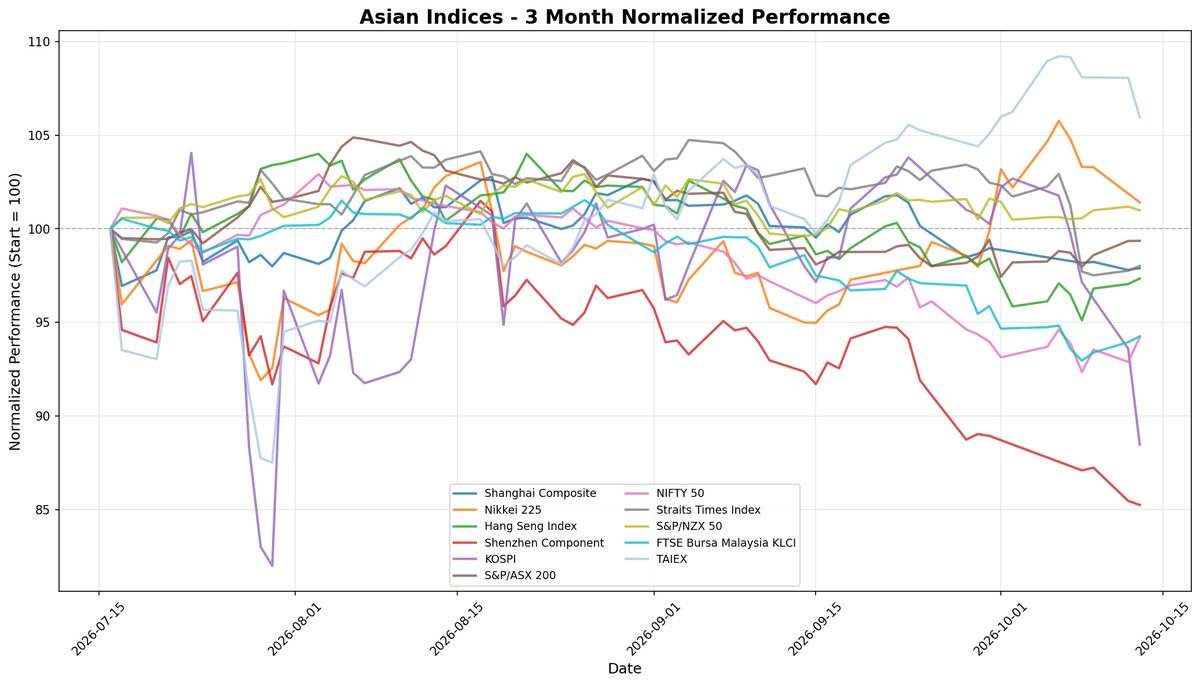
| Nikkei 225 | 67777.52 | -1.82% |
| Shanghai Composite | 3800.86 | +0.10% |
| Hang Seng | 24345.22 | +0.30% |
💱 FX & Commodities
| Name | Price | Daily (%) |
|---|---|---|
| EUR/USD | 1.12 | +0.30% |
| GBP/USD | 1.32 | +0.23% |
| USD/JPY | 158.38 | -0.11% |
| Gold (XAU/USD) | 4198.50 | +0.19% |
| Crude Oil (WTI) | 93.20 | -0.58% |
| Brent Oil | 105.55 | -1.03% |
| Bitcoin | 83143.36 | +1.69% |
🌍 Geopolitics and Market Drivers
Current market dynamics are heavily influenced by several key geopolitical and macroeconomic factors. Firstly, the ongoing conflict in Ukraine continues to escalate, with Western nations considering further sanctions against Russia, which could disrupt energy supplies and heighten inflationary pressures in Europe. On the central bank front, the Federal Reserve's recent signals indicate a potential pause in interest rate hikes, as inflation shows signs of moderating. This has led to a mixed response in equity markets, with investors weighing the implications for growth against persistent inflation risks. Economic data releases have shown a slowdown in consumer spending, raising concerns about the resilience of the U.S. economy. The latest GDP figures indicate a growth rate of 2.1%, which, while positive, reflects a deceleration from previous quarters. Politically, the U.S. debt ceiling negotiations are intensifying, with potential implications for fiscal policy and market stability. The outcome of these discussions could significantly impact investor sentiment and market liquidity. Overall, these factors create a complex landscape, with heightened volatility expected as markets react to evolving geopolitical tensions and economic indicators.
📅 Today's Economic Calendar
All times are in US Eastern Time (ET)
| Time (ET) | Event | Importance |
|---|---|---|
| 02:00 | German CPI (MoM) (Sep) | High |
| 02:00 | German CPI (YoY) (Sep) | Medium |
| 03:15 | ECB's Elderson Speaks | Medium |
| 03:45 | Fed Waller Speaks | Medium |
| 06:00 | OPEC Monthly Report | Medium |
| 08:15 | ADP Employment Change Weekly | Medium |
| 10:00 | Existing Home Sales (MoM) (Sep) | Medium |
| 10:00 | Existing Home Sales (Sep) | High |
| 13:30 | ECB's Lane Speaks | Medium |
| 14:00 | Federal Budget Balance (Sep) | Medium |
| 21:30 | CPI (YoY) (Sep) | Medium |
| 21:30 | CPI (MoM) (Sep) | Medium |
| 21:30 | PPI (YoY) (Sep) | Medium |
| 22:10 | ECB President Lagarde Speaks | Medium |
| 23:00 | Exports (YoY) (Sep) | Medium |
| 23:00 | Imports (YoY) (Sep) | Medium |
| 23:00 | Trade Balance (USD) (Sep) | Medium |
A series of significant economic events are scheduled, including the release of German CPI data and various speeches from key central bank officials, which could influence market sentiment regarding inflation and monetary policy. The ADP Employment Change and Existing Home Sales reports will provide insights into the U.S. labor market and housing sector, while the CPI and PPI data later in the day will be critical for assessing inflation trends. Overall, these events are likely to create volatility in financial markets as investors react to potential shifts in economic indicators and central bank guidance.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.