European Indices Slip: EuroStoxx 50 Down 0.45% — Cautious Sentiment Ahead of US Trading.
MarketsFN Team
European markets approaching close (still trading) • US markets actively trading • Analysis based on last 8 hours
📊 Market Overview
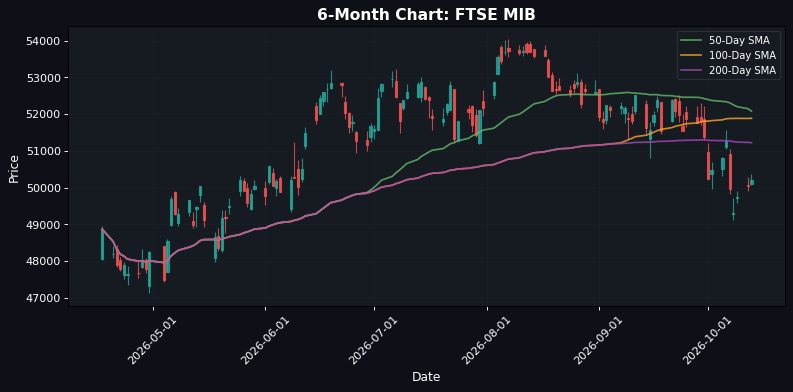
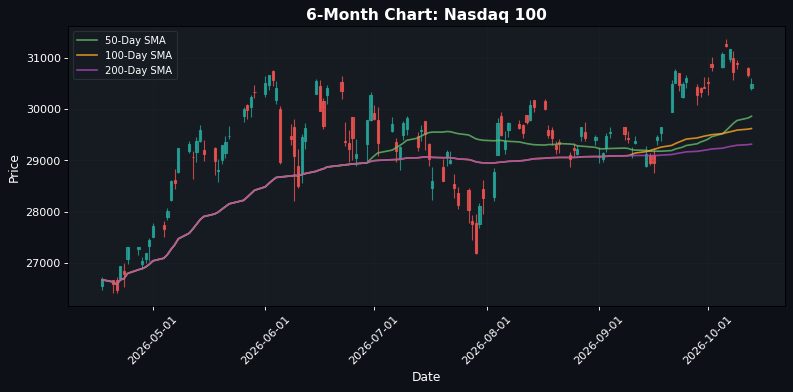
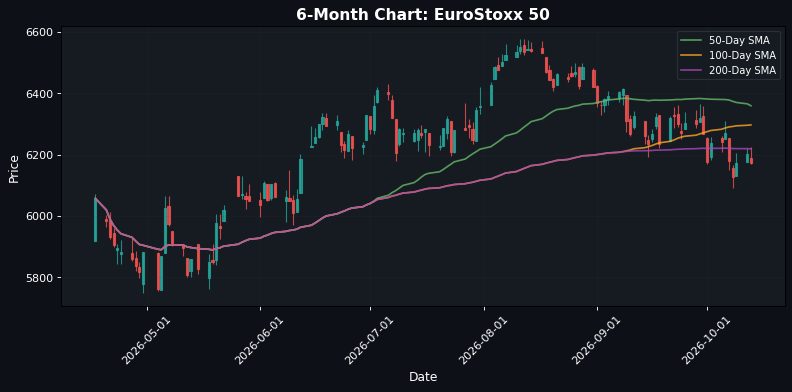
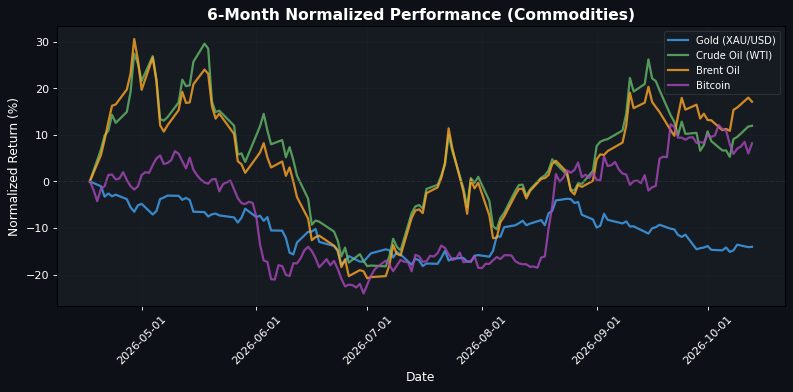
**Market Sentiment Dips as European Indices Close Lower Amid Mixed Global Performance** European markets are closing on a cautious note, with the EuroStoxx 50 down by 0.45% at 6173.03, reflecting a broader trend of slight declines across the continent. The DAX and FTSE 100 both registered minimal losses of 0.07%, while the CAC 40 fell by 0.18%. The FTSE MIB and IBEX 35 showed resilience, with declines of just 0.01% and 0.39%, respectively. This subdued performance comes as investors grapple with mixed signals from global markets, particularly as US indices are currently trading lower, with the S&P 500 down 0.14% at 7796.10 and the Nasdaq 100 leading the decline at -0.60%. In the FX and commodities space, the euro is gaining strength against the dollar, with EUR/USD up 0.36% at 1.1197, while the GBP/USD also saw a modest increase of 0.27%. Gold is slightly up by 0.09%, trading at 4194.2002, indicating a flight to safety amidst the equity market pullback. However, Brent Oil is down 0.74% at 105.8600, contrasting with WTI's slight gain of 0.14% at 93.8700, highlighting a divergence in oil market sentiment. The market appears to be underpricing the potential impact of upcoming economic data releases, particularly the US employment figures scheduled for later this week. A stronger-than-expected jobs report could shift sentiment and provide a much-needed boost to risk assets, while a weaker report may exacerbate current market hesitancy. Investors should prepare for volatility as these data points are likely to influence market direction significantly.
🇪🇺 European Markets (Approaching Close)
| Name | Price | Daily (%) |
|---|---|---|
| EuroStoxx 50 | 6173.03 | -0.45% |
| DAX | 25259.33 | -0.07% |
| FTSE 100 | 10648.35 | -0.07% |
| CAC 40 | 7819.01 | -0.18% |
| FTSE MIB | 50028.09 | -0.01% |
| IBEX 35 | 19211.40 | -0.39% |
🇺🇸 US Markets (Currently Active)
| Name | Price | Daily (%) |
|---|---|---|
| S&P 500 | 7796.10 | -0.14% |
| Dow Jones | 51791.39 | -0.11% |
| Nasdaq 100 | 30481.65 | -0.60% |
🌏 Asian Markets
| Name | Price | Daily (%) |
|---|---|---|
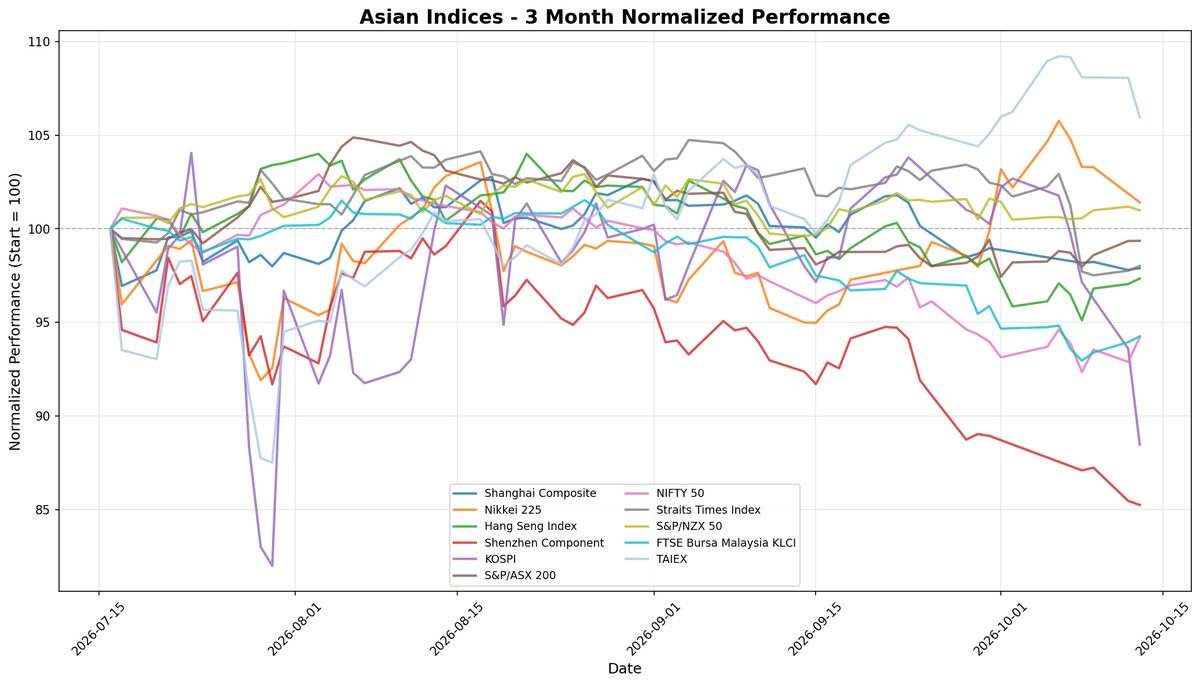
| Nikkei 225 | 69030.92 | -0.02% |
| Shanghai Composite | 3800.86 | +0.10% |
| Hang Seng | 24345.22 | +0.30% |
💱 FX & Commodities
| Name | Price | Daily (%) |
|---|---|---|
| EUR/USD | 1.12 | +0.36% |
| GBP/USD | 1.32 | +0.27% |
| USD/JPY | 158.39 | -0.10% |
| Gold (XAU/USD) | 4194.20 | +0.09% |
| Crude Oil (WTI) | 93.87 | +0.14% |
| Brent Oil | 105.86 | -0.74% |
| Bitcoin | 83439.23 | +2.05% |
🌍 Geopolitics and Market Drivers
Current market dynamics are heavily influenced by several key geopolitical and macroeconomic factors. Firstly, the ongoing conflict in Ukraine continues to create volatility, particularly in energy markets, as European nations grapple with supply disruptions and rising prices. This situation is compounded by heightened tensions in the Middle East, which have raised concerns about oil supply stability. On the central bank front, the Federal Reserve's recent signals indicate a potential pause in interest rate hikes, as inflation shows signs of moderating. This shift could bolster investor sentiment, but it also raises questions about the sustainability of economic growth. Economic data releases have shown mixed signals; while U.S. job growth remains robust, consumer spending is beginning to show signs of fatigue, suggesting a potential slowdown. Additionally, China's economic recovery appears sluggish, impacting global demand. Politically, the upcoming U.S. elections are creating uncertainty, with potential implications for fiscal policy and regulatory changes. These factors collectively contribute to a cautious market outlook, as investors weigh geopolitical risks against economic indicators.
📅 Today's Economic Calendar
All times are in US Eastern Time (ET)
| Time (ET) | Event | Importance |
|---|---|---|
| 02:00 | German CPI (MoM) (Sep) | High |
| 02:00 | German CPI (YoY) (Sep) | Medium |
| 03:15 | ECB's Elderson Speaks | Medium |
| 03:45 | Fed Waller Speaks | Medium |
| 06:00 | OPEC Monthly Report | Medium |
| 08:15 | ADP Employment Change Weekly | Medium |
| 10:00 | Existing Home Sales (MoM) (Sep) | Medium |
| 10:00 | Existing Home Sales (Sep) | High |
| 13:30 | ECB's Lane Speaks | Medium |
| 14:00 | Federal Budget Balance (Sep) | Medium |
| 21:30 | CPI (YoY) (Sep) | Medium |
| 21:30 | CPI (MoM) (Sep) | Medium |
| 21:30 | PPI (YoY) (Sep) | Medium |
| 22:10 | ECB President Lagarde Speaks | Medium |
| 23:00 | Exports (YoY) (Sep) | Medium |
| 23:00 | Imports (YoY) (Sep) | Medium |
| 23:00 | Trade Balance (USD) (Sep) | Medium |
The release of German CPI data and various speeches from ECB and Fed officials are likely to influence market sentiment, particularly regarding inflation expectations and monetary policy direction. Additionally, the ADP Employment Change and Existing Home Sales reports will provide insights into the labor market and housing sector, impacting investor confidence. Lastly, the CPI and PPI data, along with trade balance figures, will be crucial for assessing inflationary pressures and trade dynamics, potentially leading to volatility in currency and equity markets.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.