Inflation Expectations Hold Steady at 2.40%, Up 3.0 bps
MarketsFN Data Team

What is a breakeven rate?
The breakeven inflation rate equals the yield gap between a conventional Treasury and a TIPS of the same maturity. If the 10Y nominal yields 4.50% and the 10Y TIPS yields 2.00%, the 10Y breakeven is 2.50% — the level of average CPI at which an investor is indifferent between the two bonds. A higher breakeven signals stronger market inflation expectations.
Why three horizons?
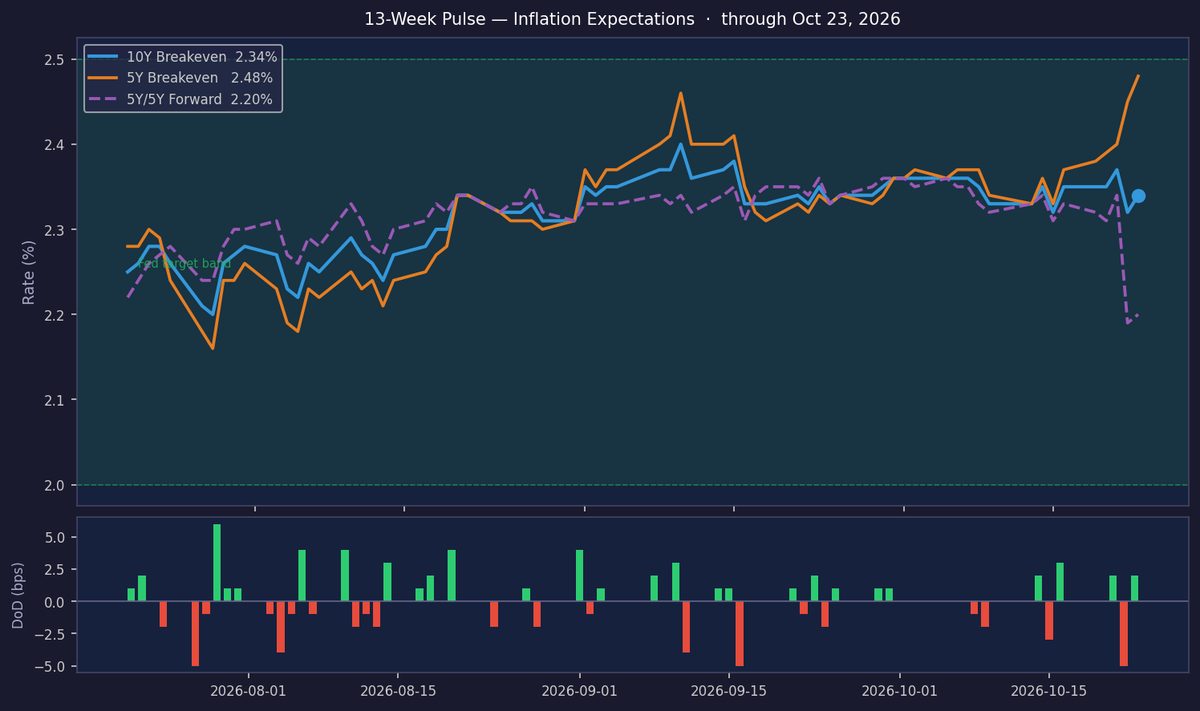
The 5Y breakeven is most sensitive to near-term CPI prints and Fed policy. The 10Y breakeven blends short and long-run expectations. The 5Y/5Y forward looks only at years 5–10, stripping out near-term noise — it is the purest read on whether long-run inflation is anchored. The Fed watches the forward rate most closely.
The Fed's 2% target in breakeven terms
The Federal Reserve targets 2% PCE inflation, not CPI. Because CPI runs roughly 0.3–0.5 pp above PCE (different basket weights and housing costs), breakevens in the 2.2–2.5% range are broadly consistent with the Fed achieving its mandate. Breakevens above 2.5% signal markets doubting that 2% will be delivered; below 2.0% signals deflation or stagnation risk.
Real yields and monetary conditions
The 10Y TIPS yield is the "real" risk-free rate — what investors earn above and beyond inflation. Positive real yields make saving more attractive than spending or risk-taking: a tightening drag on the economy. Negative real yields (common in 2020–2022) were highly stimulative, driving asset prices and compressing credit spreads. The real yield is a direct gauge of monetary restriction.
Inflation expectations rose notably this week, with the 10Y breakeven reaching 2.40%, up 6bps WoW and now in the 85th percentile over the past decade. Today’s +3bps DoD move reflects persistent market skepticism about the Fed’s ability to sustainably return inflation to target, despite the ON TARGET regime holding. Next week’s focus will be on whether this upward momentum stabilizes or extends further.
The 5Y/5Y forward rate edged up 1bp today to 2.34%, remaining near the top of its recent range but still within the Fed’s comfort zone. While this week’s 11bps WoW jump in 5Y breakevens suggests some near-term unanchoring, the forward gauge’s stability at the 88.8th percentile signals long-term expectations are not yet unmoored. Watch for any divergence between near-term and forward pricing.

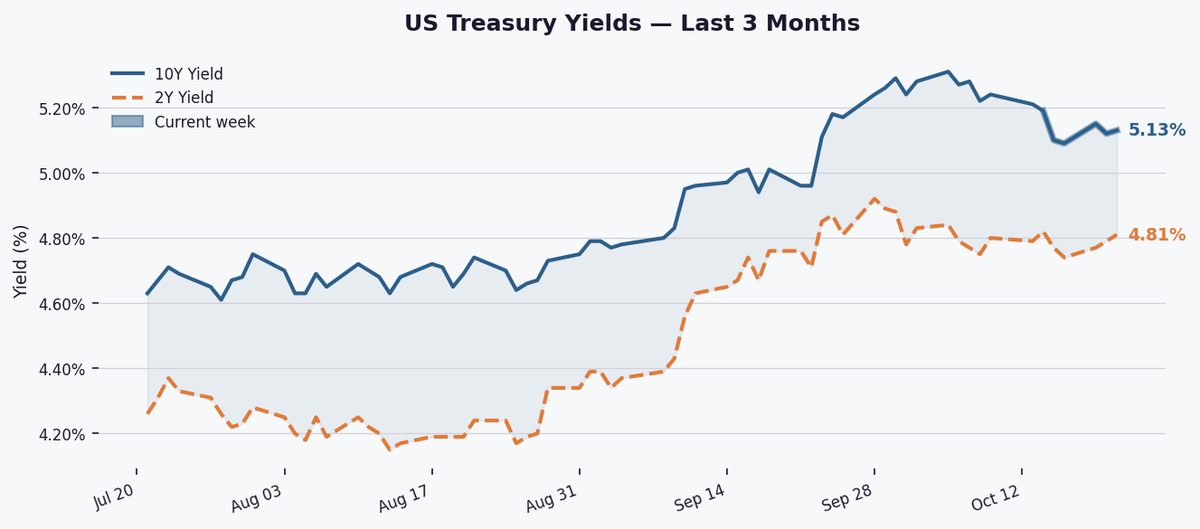
The 10Y real yield of 2.46% reflects restrictive monetary conditions, as it sits well above the Fed’s estimated neutral rate. Combined with the 6.23% nominal yield, this implies elevated inflation compensation (3.77%) and tight financial conditions. Real yields at these levels risk slowing growth if sustained, but for now align with the Fed’s inflation-fighting stance.
Next week’s August CPI (Wed) and retail sales (Fri) will test whether recent inflation repricing is justified, while Fed speakers (notably Williams on Thu) may address the term premium’s inversion (-6bps). A hot CPI print could push breakevens higher, but a miss may trigger a correction after this week’s sharp moves. Monitor the 5Y/5Y forward for anchoring signals.
| Series | Latest | DoD | WoW | 10Y Rank | Freq. |
|---|---|---|---|---|---|
| 10Y Breakeven (T10YIE) | 2.40% | +3.0 bps | +6.0 bps | 85.0th pct | Daily |
| 5Y Breakeven (T5YIE) | 2.46% | +5.0 bps | +11.0 bps | 77.0th pct | Daily |
| 5Y/5Y Forward (T5YIFR) | 2.34% | +1.0 bps | — | 88.8th pct | Daily |
| 10Y Real / TIPS (DFII10) | 2.46% | +3.0 bps | — | — | Daily |
| 10Y Nominal (DGS10) | 6.23% | +0.0 bps | +24.0 bps | — | Daily |
| Term Premium (10Y−5Y be) | -6.0 bps | n/a | — | — | Derived |
| CPI YoY | 3.5% YoY (July 2026) | n/a | — | — | Monthly |
| Core PCE YoY | 3.3% YoY (July 2026) | n/a | — | — | Monthly |