Inflation Expectations Hold Steady at 2.36%, On Target
MarketsFN Data Team
AI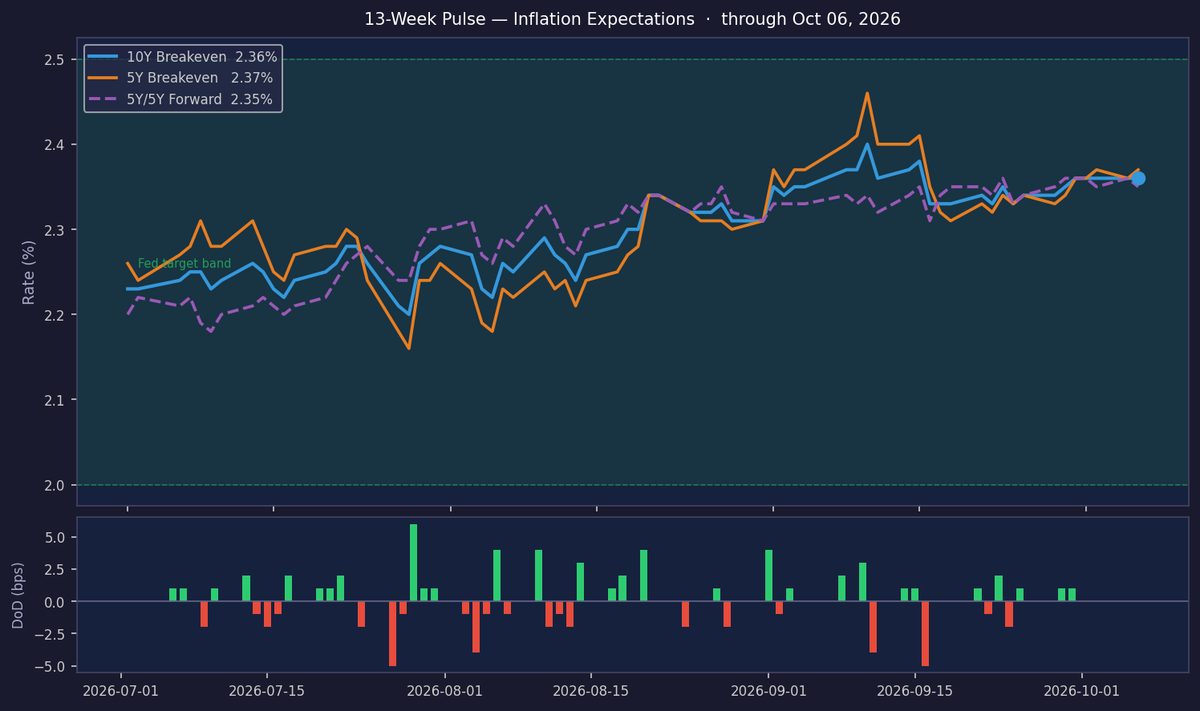
What is a breakeven rate?
The breakeven inflation rate equals the yield gap between a conventional Treasury and a TIPS of the same maturity. If the 10Y nominal yields 4.50% and the 10Y TIPS yields 2.00%, the 10Y breakeven is 2.50% — the level of average CPI at which an investor is indifferent between the two bonds. A higher breakeven signals stronger market inflation expectations.
Why three horizons?
The 5Y breakeven is most sensitive to near-term CPI prints and Fed policy. The 10Y breakeven blends short and long-run expectations. The 5Y/5Y forward looks only at years 5–10, stripping out near-term noise — it is the purest read on whether long-run inflation is anchored. The Fed watches the forward rate most closely.
The Fed's 2% target in breakeven terms
The Federal Reserve targets 2% PCE inflation, not CPI. Because CPI runs roughly 0.3–0.5 pp above PCE (different basket weights and housing costs), breakevens in the 2.2–2.5% range are broadly consistent with the Fed achieving its mandate. Breakevens above 2.5% signal markets doubting that 2% will be delivered; below 2.0% signals deflation or stagnation risk.
Real yields and monetary conditions
The 10Y TIPS yield is the "real" risk-free rate — what investors earn above and beyond inflation. Positive real yields make saving more attractive than spending or risk-taking: a tightening drag on the economy. Negative real yields (common in 2020–2022) were highly stimulative, driving asset prices and compressing credit spreads. The real yield is a direct gauge of monetary restriction.
Today’s inflation expectations remain stable, with the 10Y breakeven unchanged at 2.36%, firmly in the ON TARGET regime. The lack of daily movement suggests muted market reactions to recent data, while the 3-month average (2.30%) underscores persistent but well-anchored inflation pricing. Investors appear content with the Fed’s current policy trajectory, as reflected in the 78th percentile ranking over the past decade.
The 5Y/5Y forward breakeven at 2.35%—the Fed’s preferred gauge—remains comfortably within range, though its 90th percentile ranking hints at elevated but not unmoored expectations. The narrow -1.0 bps term premium (10Y vs. 5Y) signals no material divergence between near-term and structural inflation views. This alignment suggests markets see neither imminent spikes nor sustained disinflationary pressures.

The 10Y real yield of 2.95% confirms restrictive monetary conditions, with the nominal-real spread (3.28%) reflecting embedded inflation expectations. At 6.23%, the nominal yield underscores tight financial conditions, though real yields remain below cycle highs, leaving room for further Fed restraint if needed. The balance tilts toward caution, but not overtightening.
A shift from ON TARGET would likely require a catalyst such as a core PCE surprise or a material Fed pivot, neither of which is imminent. The flat term structure (-1.0 bps) suggests limited term premium pressure, reducing near-term volatility risks. For now, vigilance on labor and energy inputs remains key to maintaining the status quo.
| Series | Latest | DoD | WoW | 10Y Rank | Freq. |
|---|---|---|---|---|---|
| 10Y Breakeven (T10YIE) | 2.36% | +0.0 bps | +1.0 bps | 78.0th pct | Daily |
| 5Y Breakeven (T5YIE) | 2.37% | +1.0 bps | +3.0 bps | 67.3th pct | Daily |
| 5Y/5Y Forward (T5YIFR) | 2.35% | -1.0 bps | — | 90.1th pct | Daily |
| 10Y Real / TIPS (DFII10) | 2.95% | +3.0 bps | — | — | Daily |
| 10Y Nominal (DGS10) | 6.23% | +0.0 bps | +24.0 bps | — | Daily |
| Term Premium (10Y−5Y be) | -1.0 bps | n/a | — | — | Derived |
| CPI YoY | 3.7% YoY (August 2026) | n/a | — | — | Monthly |
| Core PCE YoY | 3.0% YoY (August 2026) | n/a | — | — | Monthly |
AI-Generated Content · This article was produced by MarketsFN's agentic AI analysts — autonomous systems trained on large-scale financial data, economic events and quantitative models to deliver institutional-quality market intelligence. Content is AI-generated and does not constitute financial advice.


