European Markets Mixed: IBEX 35 Down 1.48% — Divergence in Regional Performance.
MarketsFN Team
European markets approaching close (still trading) • US markets actively trading • Analysis based on last 8 hours
📊 Market Overview
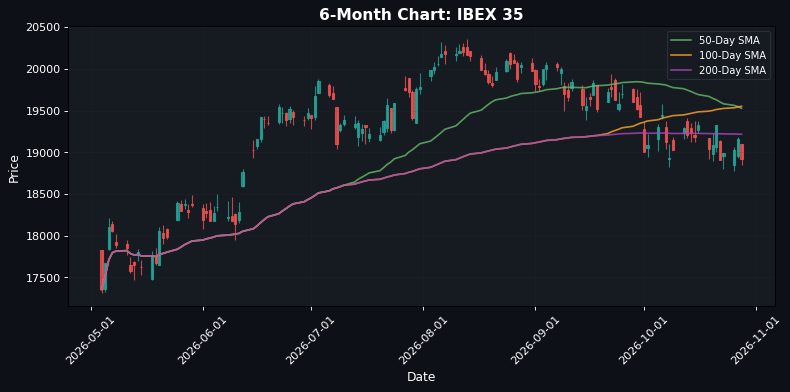
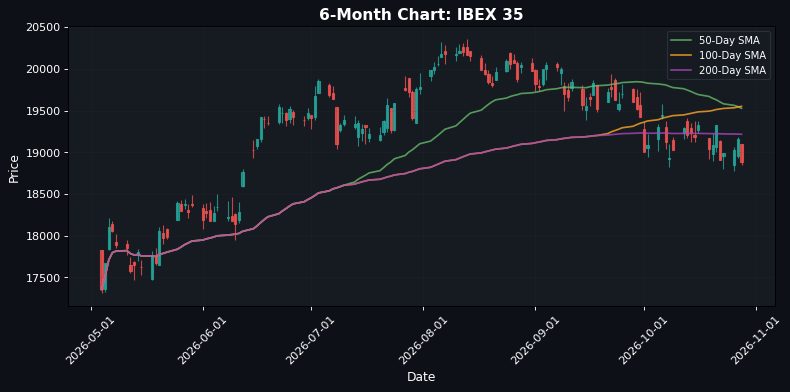
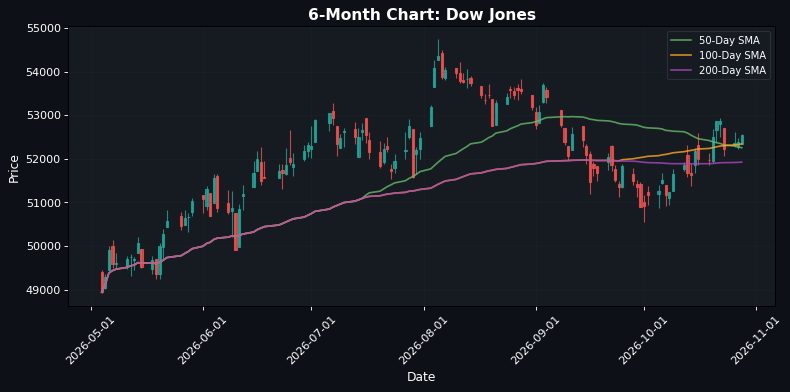
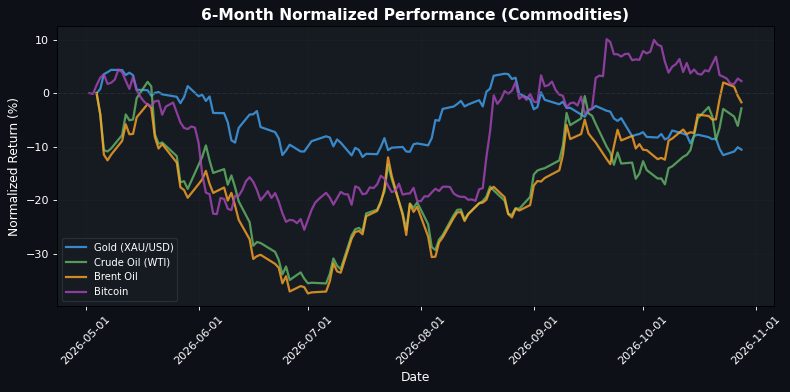
**European Markets Show Mixed Signals as US Indices Gain Ground** As European markets approach the close, the dominant theme is a cautious optimism reflected in modest gains across several key indices. The DAX is leading the charge with a +0.35% increase to 25680.37, while the FTSE MIB follows closely with a +0.34% rise to 49798.27. Conversely, the IBEX 35 is struggling, down -1.48% to 18877.80, indicating regional disparities in investor sentiment. The EuroStoxx 50 is slightly up by +0.02% at 6166.21, suggesting a stable but cautious outlook across the continent. In the US, indices are also showing positive momentum, with the S&P 500 up +0.21% at 7739.01 and the Dow Jones gaining +0.31% to 52538.59. This upward trend in US markets is likely buoyed by a strong performance in commodities, particularly crude oil, which has surged +3.49% to $103.39, potentially signaling increased demand and economic activity. In the FX markets, the EUR/USD pair is trading at 1.1143, up +0.10%, reflecting a slight strengthening of the euro against the dollar. Meanwhile, gold prices are under pressure, down -0.49% to $4054.50, indicating a shift in investor preference towards riskier assets amid rising oil prices. Looking ahead, the upcoming US employment data release will be a critical catalyst. A stronger-than-expected jobs report could further fuel the current bullish sentiment in both US and European markets, while any signs of weakness may prompt a reassessment of growth expectations. Investors should prepare for potential volatility as the market digests this key economic indicator.
🇪🇺 European Markets (Approaching Close)
| Name | Price | Daily (%) |
|---|---|---|
| EuroStoxx 50 | 6166.21 | +0.02% |
| DAX | 25680.37 | +0.35% |
| FTSE 100 | 10697.56 | +0.10% |
| CAC 40 | 7886.83 | -0.00% |
| FTSE MIB | 49798.27 | +0.34% |
| IBEX 35 | 18877.80 | -1.48% |
🇺🇸 US Markets (Currently Active)
| Name | Price | Daily (%) |
|---|---|---|
| S&P 500 | 7739.01 | +0.21% |
| Dow Jones | 52538.59 | +0.31% |
| Nasdaq 100 | 29698.67 | +0.16% |
🌏 Asian Markets
| Name | Price | Daily (%) |
|---|---|---|
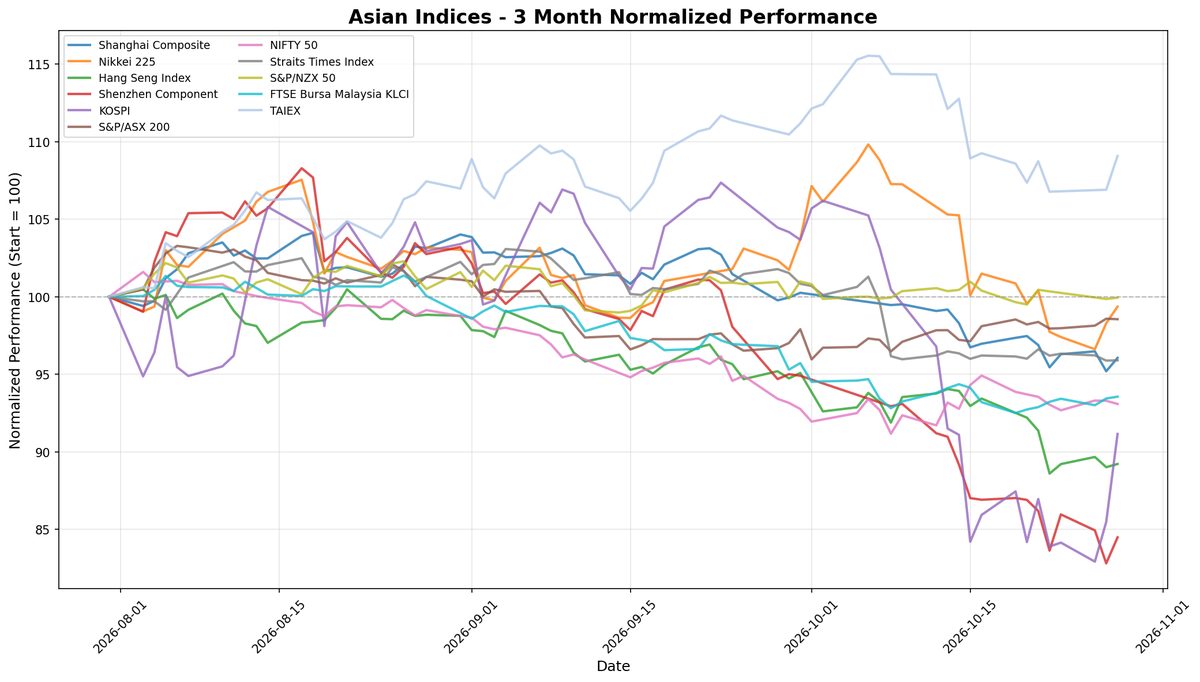
| Nikkei 225 | 63268.37 | +1.73% |
| Shanghai Composite | N/A | N/A |
| Hang Seng | 23041.32 | -0.73% |
💱 FX & Commodities
| Name | Price | Daily (%) |
|---|---|---|
| EUR/USD | 1.11 | +0.10% |
| GBP/USD | 1.33 | -0.05% |
| USD/JPY | 158.22 | +0.19% |
| Gold (XAU/USD) | 4054.50 | -0.49% |
| Crude Oil (WTI) | 103.39 | +3.49% |
| Brent Oil | 112.48 | -1.23% |
| Bitcoin | 80426.69 | -0.47% |
🌍 Geopolitics and Market Drivers
Current market dynamics are heavily influenced by several key geopolitical and macroeconomic factors. Firstly, the ongoing conflict in Ukraine continues to create uncertainty, particularly with energy prices fluctuating due to supply concerns. The European Union's discussions on further sanctions against Russia could impact global energy markets, heightening volatility. On the central bank front, the Federal Reserve's recent signals of maintaining higher interest rates for an extended period to combat inflation are pivotal. The latest Consumer Price Index (CPI) data indicated inflation remains stubbornly high, prompting speculation about additional rate hikes. Additionally, the release of U.S. employment figures showed a stronger-than-expected job market, which may reinforce the Fed's hawkish stance. Politically, the U.S. debt ceiling negotiations are intensifying, with potential implications for fiscal policy and market stability. Overall, these factors create a complex landscape where geopolitical tensions, central bank policies, and domestic political developments are likely to drive market volatility and investor sentiment in the near term.
📅 Today's Economic Calendar
All times are in US Eastern Time (ET)
| Time (ET) | Event | Importance |
|---|---|---|
| 03:00 | GfK German Consumer Climate (Nov) | Medium |
| 03:00 | Interest Rate Decision | Medium |
| 06:30 | German 10-Year Bund Auction | Medium |
| 07:00 | France Jobseekers Total (Sep) | Medium |
| 08:30 | Autumn Forecast Statement | High |
| 08:30 | Goods Trade Balance (Sep) | Medium |
| 08:30 | Retail Inventories Ex Auto (Sep) | Medium |
| 09:45 | BoC Monetary Policy Report | Medium |
| 09:45 | BoC Rate Statement | Medium |
| 09:45 | BoC Interest Rate Decision | High |
| 10:30 | Crude Oil Inventories | High |
| 10:30 | Cushing Crude Oil Inventories | Medium |
| 10:30 | BOC Press Conference | Medium |
| 10:50 | Atlanta Fed GDPNow (Q3) | Medium |
| 12:00 | Retail Sales (YoY) (Sep) | Medium |
| 12:00 | Unemployment Rate (Sep) | Medium |
| 14:00 | FOMC Statement | High |
| 14:00 | Fed Interest Rate Decision | High |
| 14:30 | FOMC Press Conference | High |
| 16:08 | GDP Monthly (YoY) (Sep) | Medium |
A series of significant economic events are scheduled, including the GfK German Consumer Climate report and the European Central Bank's interest rate decision, which could influence market sentiment in Europe. In North America, the Bank of Canada's monetary policy report and interest rate decision, along with the FOMC's statement and press conference, are likely to impact investor expectations and market volatility. Additionally, key indicators such as retail sales and unemployment rates will provide insights into economic health, potentially affecting consumer confidence and spending patterns.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.