European Markets Mixed: DAX Up 0.33% — US Indices Show Mild Gains Ahead of Close.
MarketsFN Team
European markets approaching close (still trading) • US markets actively trading • Analysis based on last 8 hours
📊 Market Overview
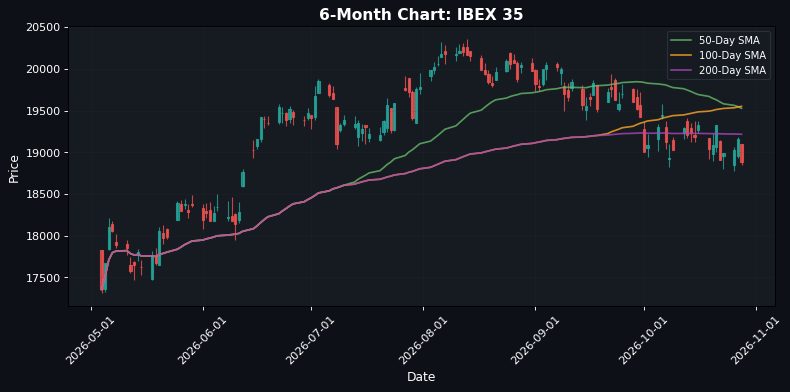
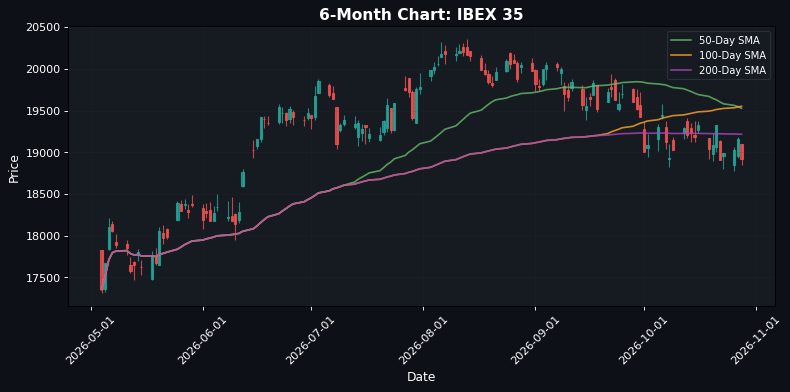
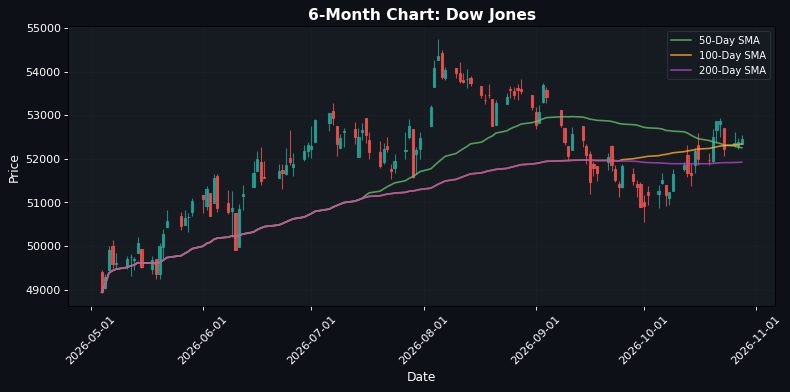
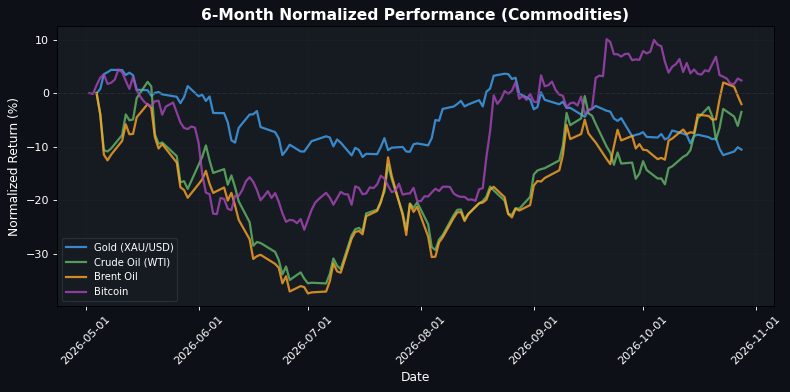
**European Markets Struggle Amid Mixed Sentiment; US Indices Show Modest Gains** As European markets approach the close, the prevailing sentiment is one of caution, with the EuroStoxx 50 down slightly by -0.03% at 6163.07. The DAX is the standout performer, gaining +0.33% to 25676.22, while the IBEX 35 lags significantly, down -1.24% at 18923.50. The CAC 40 and FTSE 100 are nearly flat, with minor movements of -0.02% and +0.09%, respectively. This mixed performance reflects investor uncertainty amid ongoing geopolitical tensions and economic data releases. In the US, indices are showing modest gains, with the S&P 500 up +0.05% at 7726.67 and the Dow Jones rising +0.13% to 52445.84. The Nasdaq 100 remains unchanged at 29652.00, indicating a lack of momentum in tech stocks. This divergence highlights a potential rotation away from growth towards value, as seen in the DAX's performance compared to the more stagnant Nasdaq. In the FX and commodities space, the EUR/USD is slightly up by +0.06% at 1.1138, while crude oil prices are experiencing a notable rise, with WTI up +2.78% at 102.6800. This increase in oil prices could be a response to supply concerns, contrasting with Brent oil, which is down -1.58% at 112.0800. The mixed performance in commodities may reflect broader market anxieties about inflation and energy supply stability. Looking ahead, the upcoming US employment data release will be a critical catalyst. A stronger-than-expected jobs report could bolster confidence in the economic recovery and lead to a more pronounced rally in US equities, while disappointing figures might exacerbate current market hesitations.
🇪🇺 European Markets (Approaching Close)
| Name | Price | Daily (%) |
|---|---|---|
| EuroStoxx 50 | 6163.07 | -0.03% |
| DAX | 25676.22 | +0.33% |
| FTSE 100 | 10696.55 | +0.09% |
| CAC 40 | 7885.92 | -0.02% |
| FTSE MIB | 49689.27 | +0.12% |
| IBEX 35 | 18923.50 | -1.24% |
🇺🇸 US Markets (Currently Active)
| Name | Price | Daily (%) |
|---|---|---|
| S&P 500 | 7726.67 | +0.05% |
| Dow Jones | 52445.84 | +0.13% |
| Nasdaq 100 | 29652.00 | +0.00% |
🌏 Asian Markets
| Name | Price | Daily (%) |
|---|---|---|
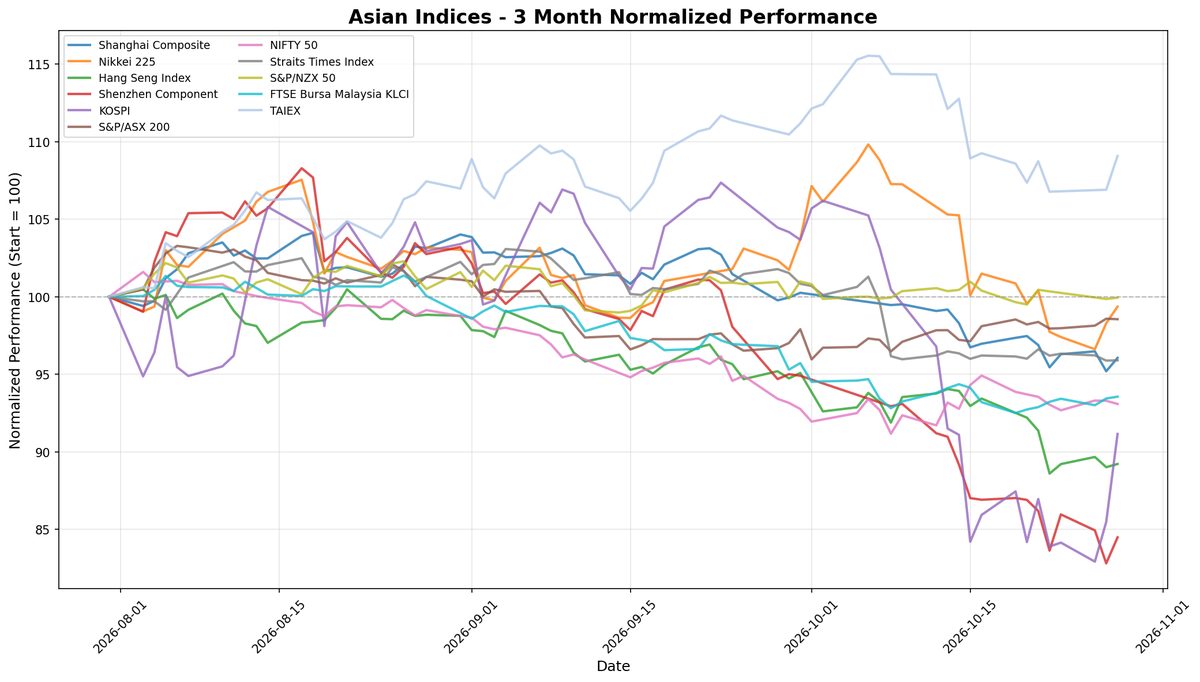
| Nikkei 225 | 63268.37 | +1.73% |
| Shanghai Composite | 3681.47 | +0.91% |
| Hang Seng | 23094.83 | +0.23% |
💱 FX & Commodities
| Name | Price | Daily (%) |
|---|---|---|
| EUR/USD | 1.11 | +0.06% |
| GBP/USD | 1.33 | -0.06% |
| USD/JPY | 158.17 | +0.17% |
| Gold (XAU/USD) | 4054.80 | -0.49% |
| Crude Oil (WTI) | 102.68 | +2.78% |
| Brent Oil | 112.08 | -1.58% |
| Bitcoin | 80520.24 | -0.35% |
🌍 Geopolitics and Market Drivers
Current market dynamics are heavily influenced by several key geopolitical and macroeconomic factors. Firstly, the ongoing conflict in Ukraine continues to create volatility, particularly in energy markets, as European nations grapple with supply disruptions and inflationary pressures. Additionally, tensions between the U.S. and China, especially regarding trade and technology, are heightening uncertainty, impacting investor sentiment. On the central bank front, the Federal Reserve's recent signals indicate a potential pause in interest rate hikes, as inflation shows signs of moderation. This has led to a rally in equities, as investors anticipate a more accommodative monetary policy. Conversely, the European Central Bank remains hawkish, emphasizing the need to combat persistent inflation, which could lead to further divergence in monetary policy between the U.S. and Europe. Economic data releases, particularly U.S. employment figures and consumer spending reports, are closely watched, as they provide insights into the resilience of the economy. Overall, these factors contribute to a cautious yet optimistic market outlook, with investors balancing geopolitical risks against potential economic recovery.
📅 Today's Economic Calendar
All times are in US Eastern Time (ET)
| Time (ET) | Event | Importance |
|---|---|---|
| 03:00 | GfK German Consumer Climate (Nov) | Medium |
| 03:00 | Interest Rate Decision | Medium |
| 06:30 | German 10-Year Bund Auction | Medium |
| 07:00 | France Jobseekers Total (Sep) | Medium |
| 08:30 | Autumn Forecast Statement | High |
| 08:30 | Goods Trade Balance (Sep) | Medium |
| 08:30 | Retail Inventories Ex Auto (Sep) | Medium |
| 09:45 | BoC Monetary Policy Report | Medium |
| 09:45 | BoC Rate Statement | Medium |
| 09:45 | BoC Interest Rate Decision | High |
| 10:30 | Crude Oil Inventories | High |
| 10:30 | Cushing Crude Oil Inventories | Medium |
| 10:30 | BOC Press Conference | Medium |
| 10:50 | Atlanta Fed GDPNow (Q3) | Medium |
| 12:00 | Retail Sales (YoY) (Sep) | Medium |
| 12:00 | Unemployment Rate (Sep) | Medium |
| 14:00 | FOMC Statement | High |
| 14:00 | Fed Interest Rate Decision | High |
| 14:30 | FOMC Press Conference | High |
| 16:08 | GDP Monthly (YoY) (Sep) | Medium |
A series of significant economic events are scheduled, including the GfK German Consumer Climate report and interest rate decisions from both the Bank of Canada (BoC) and the Federal Reserve (Fed), which are likely to influence market sentiment. The release of the Autumn Forecast Statement and various retail and employment data will provide insights into economic health, potentially impacting consumer confidence and spending. Overall, these events could lead to increased market volatility, particularly in interest rate-sensitive sectors and commodities like crude oil.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.