European Indices Up: DAX Rises 1.45% — Positive Momentum Ahead of US Market Close
MarketsFN Team
European markets approaching close (still trading) • US markets actively trading • Analysis based on last 8 hours
📊 Market Overview
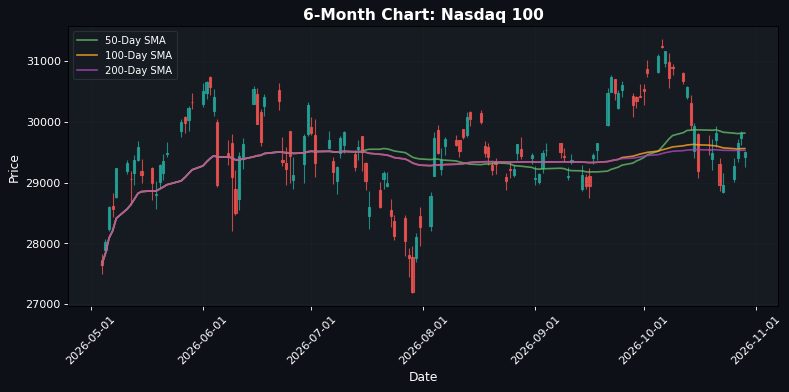
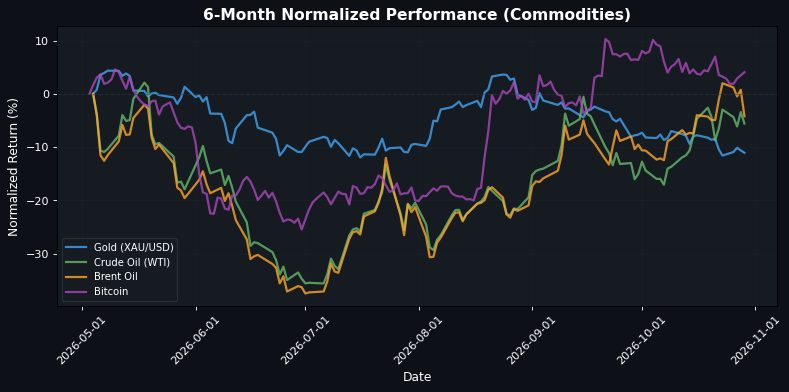
**European Markets Rally While US Indices Struggle: A Divergent Path Amidst Commodity Pressures** As European markets approach the close, a notable divergence is evident between the robust performance of European indices and the struggles of US markets. The EuroStoxx 50 is up +0.78% at 6215.68, led by the DAX, which has surged +1.45% to 26076.19. The CAC 40 follows closely with a +1.25% gain, reflecting strong investor sentiment across the continent. In contrast, US indices are under pressure, with the S&P 500 down -0.23% at 7725.92 and the Nasdaq 100 declining -1.06% to 29497.50, indicating a stark contrast in market dynamics. This divergence can be attributed to the recent volatility in commodities, particularly crude oil, which has seen WTI prices fall -2.23% to $100.49 and Brent oil plummet -4.94% to $109.62. Such declines are likely weighing on US market sentiment, as higher energy costs have been a persistent concern for inflation and economic growth. Meanwhile, the FX market shows a slight strengthening of the euro against the dollar, with EUR/USD at 1.1167, up +0.08%, suggesting a more favorable outlook for European equities. Investors should be particularly attentive to upcoming economic data releases, specifically the US inflation report scheduled for next week. This data will be crucial in determining the trajectory of monetary policy and could either validate the current bearish sentiment in US equities or provide a catalyst for a rebound if inflation shows signs of cooling. The market's reaction to this report will be pivotal in shaping the near-term outlook for both US and European markets.
🇪🇺 European Markets (Approaching Close)
| Name | Price | Daily (%) |
|---|---|---|
| EuroStoxx 50 | 6215.68 | +0.78% |
| DAX | 26076.19 | +1.45% |
| FTSE 100 | 10736.68 | +0.39% |
| CAC 40 | 7985.69 | +1.25% |
| FTSE MIB | 50091.60 | +0.54% |
| IBEX 35 | 18862.80 | -0.11% |
🇺🇸 US Markets (Currently Active)
| Name | Price | Daily (%) |
|---|---|---|
| S&P 500 | 7725.92 | -0.23% |
| Dow Jones | 52319.92 | -0.30% |
| Nasdaq 100 | 29497.50 | -1.06% |
🌏 Asian Markets
| Name | Price | Daily (%) |
|---|---|---|
| Nikkei 225 | 63954.19 | +1.08% |
| Shanghai Composite | N/A | N/A |
| Hang Seng | 23094.83 | +0.23% |
💱 FX & Commodities
| Name | Price | Daily (%) |
|---|---|---|
| EUR/USD | 1.12 | +0.08% |
| GBP/USD | 1.34 | +0.36% |
| USD/JPY | 157.82 | +0.02% |
| Gold (XAU/USD) | 4032.10 | -0.48% |
| Crude Oil (WTI) | 100.49 | -2.23% |
| Brent Oil | 109.62 | -4.94% |
| Bitcoin | 81725.20 | +0.56% |
🌍 Geopolitics and Market Drivers
Current market dynamics are heavily influenced by several key geopolitical and macroeconomic factors. Firstly, the ongoing conflict in Ukraine continues to create uncertainty, particularly with the potential for escalated military actions and its implications for energy prices in Europe. This situation is compounded by the recent tensions in the Middle East, which have raised concerns about oil supply disruptions. On the central bank front, the Federal Reserve's signals regarding interest rates remain pivotal. Recent comments suggest a cautious approach to further rate hikes, as inflation shows signs of moderation but still exceeds target levels. This has led to mixed reactions in equity markets, with investors weighing growth prospects against potential tightening. Economic data releases have also played a crucial role, particularly the latest employment figures, which indicate a resilient labor market but raise questions about wage inflation. Additionally, consumer sentiment data reflects growing concerns over economic stability, impacting spending forecasts. Overall, these geopolitical tensions and central bank signals are creating a volatile environment, prompting investors to reassess risk and return profiles across various asset classes.
📅 Today's Economic Calendar
All times are in US Eastern Time (ET)
| Time (ET) | Event | Importance |
|---|---|---|
| 03:00 | GDP (QoQ) (Q3) | Medium |
| 03:00 | GDP (YoY) (Q3) | Medium |
| 06:10 | Italian 10-Year BTP Auction | Medium |
| 08:30 | Continuing Jobless Claims | Medium |
| 08:30 | Core PCE Price Index (MoM) (Sep) | High |
| 08:30 | Core PCE Price Index (YoY) (Sep) | High |
| 08:30 | Core PCE Prices (Q3) | Medium |
| 08:30 | GDP (QoQ) (Q3) | High |
| 08:30 | GDP Price Index (QoQ) (Q3) | Medium |
| 08:30 | Initial Jobless Claims | High |
| 08:30 | PCE price index (MoM) (Sep) | Medium |
| 08:30 | PCE Price index (YoY) (Sep) | Medium |
| 08:30 | Personal Spending (MoM) (Sep) | Medium |
| 09:15 | Deposit Facility Rate (Oct) | High |
| 09:15 | ECB Marginal Lending Facility | Medium |
| 09:15 | ECB Monetary Policy Statement | Medium |
| 09:15 | ECB Interest Rate Decision (Oct) | High |
| 09:45 | ECB Press Conference | High |
| 10:30 | Atlanta Fed GDPNow (Q4) | Medium |
| 10:30 | German Buba Mauderer Speaks | Medium |
| 11:15 | ECB President Lagarde Speaks | Medium |
| 13:00 | 7-Year Note Auction | Medium |
| 13:00 | Gross Debt-to-GDP ratio (MoM) (Sep) | Medium |
| 16:30 | Fed's Balance Sheet | Medium |
| 19:30 | Tokyo Core CPI (YoY) (Oct) | Medium |
| 19:50 | Industrial Production (MoM) (Sep) | Medium |
| 20:30 | PPI (QoQ) (Q3) | Medium |
| 20:30 | PPI (YoY) (Q3) | Medium |
| 22:30 | BoJ Monetary Policy Statement | Medium |
| 23:00 | BoJ Outlook Report (YoY) | Medium |
| 23:00 | BoJ Interest Rate Decision | High |
A series of significant economic indicators will be released, including GDP data and inflation metrics such as the Core PCE Price Index, which could influence market sentiment regarding economic growth and inflationary pressures. The European Central Bank's interest rate decision and monetary policy statement are also critical, as they will provide insights into future monetary policy direction, potentially impacting the euro and European equities. Additionally, jobless claims data and various auctions, including Italian BTPs and U.S. notes, will further shape investor expectations and market dynamics throughout the day.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.