HY spreads hold at 338 bps in normal regime as IG widens to 91 bps
MarketsFN Data Team
The Option-Adjusted Spread measures the yield premium a corporate bond pays over a risk-free government bond of the same maturity — after stripping out the value of any embedded options (like call provisions). It isolates pure credit risk compensation. A wider OAS means bond investors demand more yield for holding corporate debt, signalling rising perceived risk. A tighter OAS means confidence in issuers is high and credit conditions are loose.
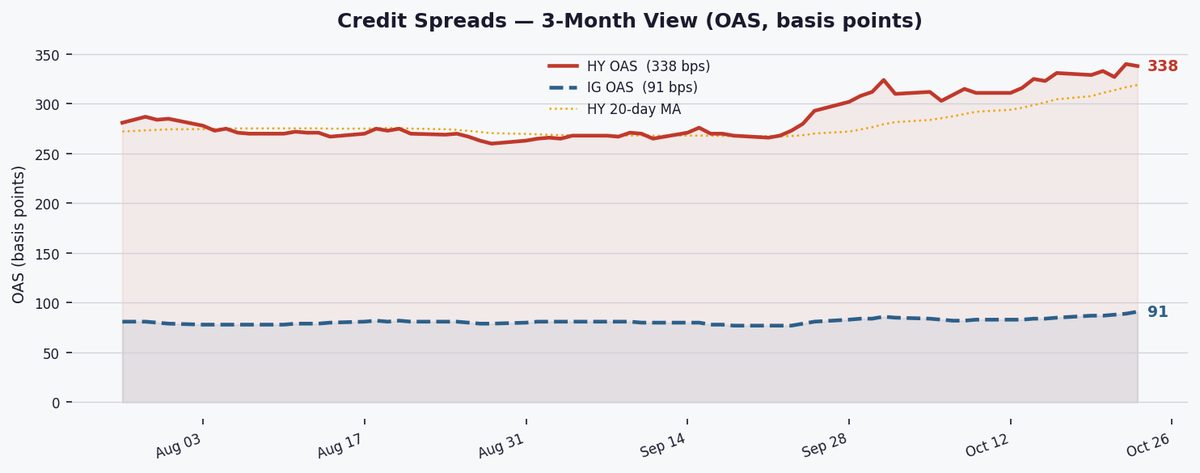
Investment Grade (IG) bonds are rated BBB−/Baa3 or above by S&P/Moody's. They represent large, financially stable companies. IG OAS is currently 91 bps. High Yield (HY) bonds are rated below BBB−/Baa3 — also called "junk bonds" — issued by companies with higher debt loads or less stable cash flows. HY OAS is 338 bps. The HY–IG gap of 247 bps is the market's price for taking extra risk.
When spreads widen (rise), investors are demanding more compensation for credit risk — often because recession fears are rising, corporate earnings are deteriorating, or liquidity is tightening. When spreads tighten (fall), risk appetite is strong: investors are willing to accept less yield premium, usually because the economic outlook is improving. Credit spreads often lead equity markets by days or weeks — they are a leading indicator of financial stress.
Historically, HY OAS has spiked before or during every US recession: ~600 bps in 2001, ~1,900 bps in 2008 (peak), ~900 bps in March 2020. The current HY OAS of 338 bps sits at the 84th percentile of the past 10 years — meaning spreads have been wider than today only 16% of the time. A sustained move above 600 bps would historically mark the threshold of serious credit stress.
High-yield spreads edged 2 bps tighter to 338 bps in normal conditions, though still at the 84th percentile historically, while IG widened 2 bps to 91 bps — the HY-IG gap remains elevated at 247 bps versus its 220 bps average.
The ICE BofA HY index OAS sits at 338 bps, in the 84th percentile of its 10-year range, indicating relatively wide spreads. Today's 2 bps tightening contrasts with a 7 bps widening week-to-date. The 20-day MA (319 bps) now exceeds the 60-day MA (287 bps), signaling short-term widening momentum. While in a NORMAL regime, spreads remain nearer their decade-high (461 bps) than median (302 bps), suggesting selective opportunities amid lingering caution.
Investment-grade spreads widened 2 bps to 91 bps (64th percentile), continuing this week's 6 bps rise. The HY-IG differential of 247 bps remains above its 220 bps 4-year average, indicating investors aren't aggressively reaching for yield. This risk-averse stance reflects in IG's tighter percentile rank (64th) versus HY (84th), with quality still commanding a premium.
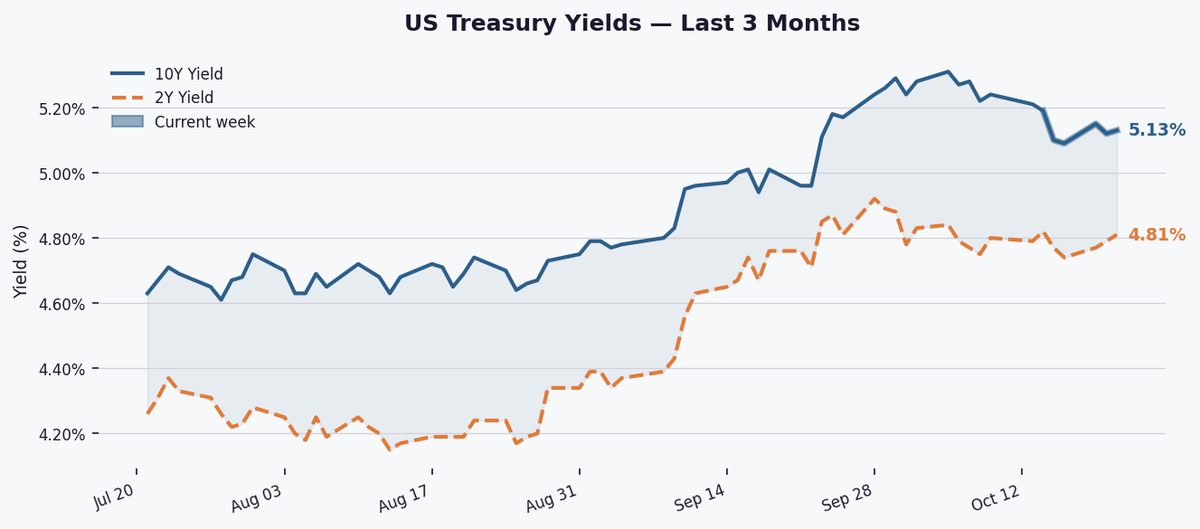
HY yields at 8.14% offer a 314 bps premium over 10Y Treasuries (5.00%), while Moody's Baa-Aaa spread of 47 bps signals moderate quality differentiation. With Baa yields at 6.47%, refinancing pressure builds for leveraged issuers — HY yields now exceed their 10-year median by 114 bps, raising default risks for weaker credits.

Full Statistics Dashboard
| Metric | Current | Change | Historical Rank |
|---|---|---|---|
| HY OAS (ICE BofA) | 338 bps | ▼ 2 bps DoD ▲ 7 bps WoW | 84th pct |
| IG OAS (ICE BofA) | 91 bps | ▲ 2 bps DoD ▲ 6 bps WoW | 64th pct |
| HY−IG Differential | 247 bps | 4Y avg: 220 bps ▲ 27 bps vs avg | |
| HY Effective Yield | 8.14% | over 10Y: +314 bps | |
| IG Effective Yield | 5.84% | ||
| Moody's Baa Yield | 6.47% | Baa−Aaa: 47 bps | |
| Moody's Aaa Yield | 6.00% | ||
| 10Y Treasury | 5.00% | ||
| SOFR | 3.920% | vs 3M T-Bill: ▼ 30 bps bps | |
| HY OAS Regime | NORMAL | Direction: WIDENING (20d MA 319 vs 60d MA 287 bps) | |
| 10Y HY Range | 259–461 bps | median 302 bps |
The SOFR-T-Bill spread at -30 bps shows money markets remain stable, with repo rates (3.92%) below T-bills (4.22%). This lack of funding stress isn't driving current spread moves, allowing credit risks to be priced independently of banking system pressures.

Watch Friday's PCE data for inflation clues that could accelerate spread widening. A sustained HY OAS break above 350 bps (near the 90th percentile) could shift the regime from NORMAL to WIDENING, particularly if IG spreads exceed 100 bps simultaneously.