European Markets Up: EuroStoxx 50 Rises 0.92% — Positive Momentum Ahead of US Open
MarketsFN Team
European markets approaching close (still trading) • US markets actively trading • Analysis based on last 8 hours
📊 Market Overview
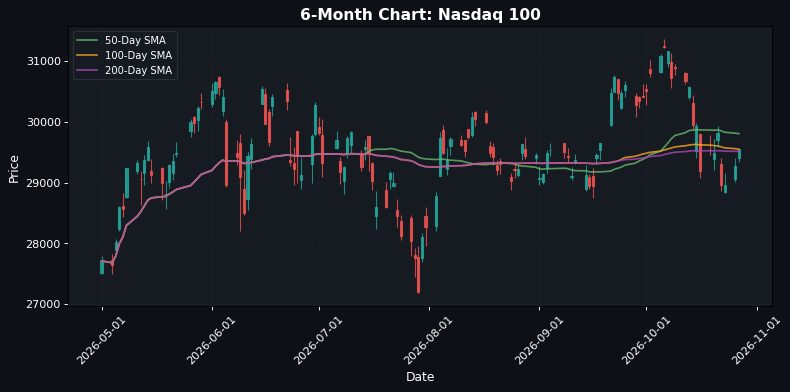
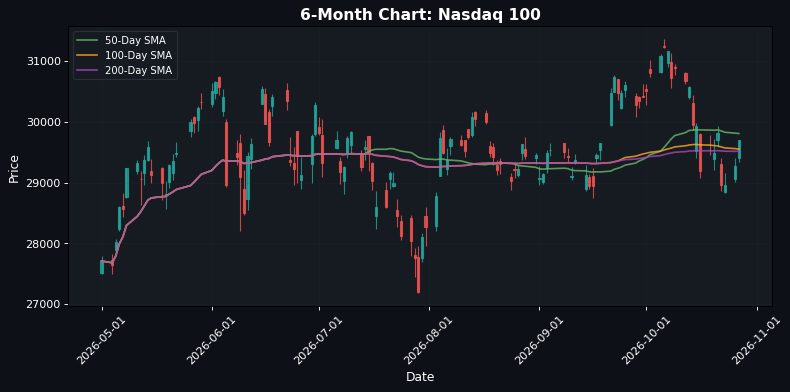
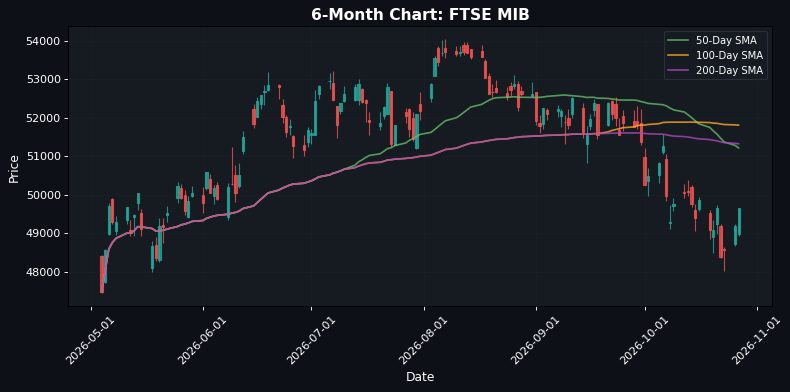
**European Markets Rally While US Indices Show Mixed Signals Amid Commodity Volatility** European indices are closing on a high note, with the EuroStoxx 50 up +0.92% at 6172.71, driven by strong performances in the DAX (+0.88% to 25634.12) and FTSE MIB (+0.94% to 49651.68). The CAC 40 also contributed positively, rising +0.68% to 7900.88. However, the FTSE 100 diverged from this trend, declining -0.68% to 10693.73, indicating a potential sector-specific weakness that investors should scrutinize. In the US, the S&P 500 is up +0.74% at 7733.47, while the Dow Jones is lagging with a modest gain of +0.19% at 52459.16. The Nasdaq 100 stands out with a robust +1.45% increase to 29697.84, reflecting strong tech sector momentum. This divergence suggests that investors are favoring growth stocks, particularly in technology, amidst a backdrop of fluctuating commodity prices. The FX market is seeing the euro weaken slightly against the dollar, with EUR/USD down -0.28% at 1.1147, while GBP/USD also dipped -0.22% to 1.3314. This comes as crude oil prices are under pressure, with WTI down -1.64% at 100.0900 and Brent oil plummeting -5.48% to 109.4600, likely impacting inflation expectations and consumer sentiment. Looking ahead, the upcoming US inflation data release will be crucial. A higher-than-expected inflation figure could shift market sentiment, particularly in the tech sector, and influence the Fed's monetary policy stance. Investors should prepare for potential volatility as this data could validate or challenge the current bullish sentiment in equities.
🇪🇺 European Markets (Approaching Close)
| Name | Price | Daily (%) |
|---|---|---|
| EuroStoxx 50 | 6172.71 | +0.92% |
| DAX | 25634.12 | +0.88% |
| FTSE 100 | 10693.73 | -0.68% |
| CAC 40 | 7900.88 | +0.68% |
| FTSE MIB | 49651.68 | +0.94% |
| IBEX 35 | 19185.80 | +0.80% |
🇺🇸 US Markets (Currently Active)
| Name | Price | Daily (%) |
|---|---|---|
| S&P 500 | 7733.47 | +0.74% |
| Dow Jones | 52459.16 | +0.19% |
| Nasdaq 100 | 29697.84 | +1.45% |
🌏 Asian Markets
| Name | Price | Daily (%) |
|---|---|---|
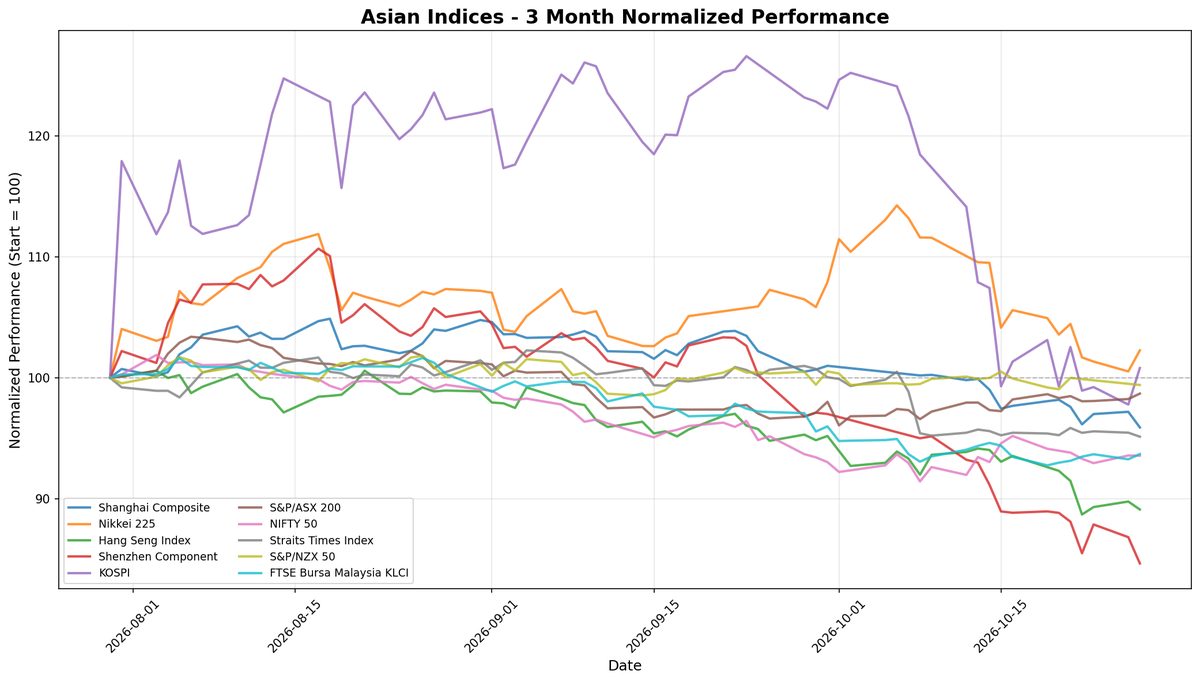
| Nikkei 225 | 62189.65 | -0.80% |
| Shanghai Composite | N/A | N/A |
| Hang Seng | 23211.81 | +0.51% |
💱 FX & Commodities
| Name | Price | Daily (%) |
|---|---|---|
| EUR/USD | 1.11 | -0.28% |
| GBP/USD | 1.33 | -0.22% |
| USD/JPY | 157.85 | +0.25% |
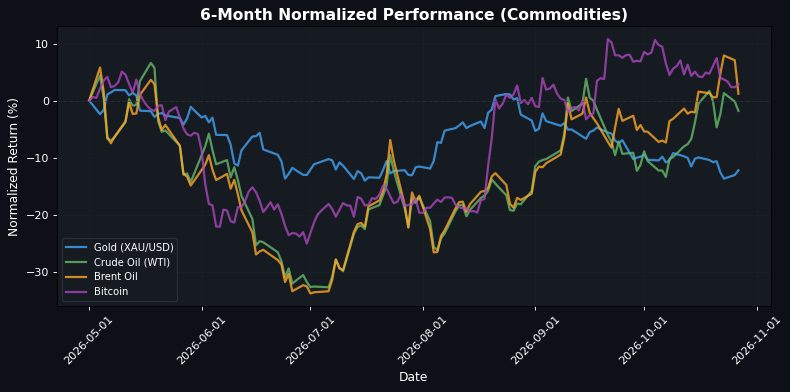
| Gold (XAU/USD) | 4076.60 | +0.95% |
| Crude Oil (WTI) | 100.09 | -1.64% |
| Brent Oil | 109.46 | -5.48% |
| Bitcoin | 80419.76 | +0.52% |
🌍 Geopolitics and Market Drivers
Current market dynamics are heavily influenced by several key geopolitical and macroeconomic factors. Firstly, the ongoing conflict in Ukraine continues to create uncertainty, particularly with energy prices and supply chains in Europe. The potential for escalated military actions could disrupt markets further. Central banks are also in focus, with the U.S. Federal Reserve signaling a cautious approach to interest rate hikes amid mixed economic data. Recent inflation reports show signs of easing, but core inflation remains a concern, prompting speculation about future monetary policy adjustments. Additionally, the release of U.S. employment data has shown resilience, with job growth exceeding expectations, which could influence the Fed's decision-making process. On the political front, the upcoming elections in key economies, including the U.S., are adding to market volatility, as potential shifts in policy could impact fiscal measures and economic growth trajectories. Overall, these factors contribute to a cautious market sentiment, with investors closely monitoring developments for their implications on growth and inflation.
📅 Today's Economic Calendar
All times are in US Eastern Time (ET)
| Time (ET) | Event | Importance |
|---|---|---|
| 01:00 | BoJ Core CPI (YoY) | Medium |
| 08:00 | Building Permits (Sep) | Medium |
| 08:15 | ADP Employment Change Weekly | Medium |
| 08:30 | Core Durable Goods Orders (MoM) (Sep) | Medium |
| 08:30 | Durable Goods Orders (MoM) (Sep) | High |
| 09:00 | S&P/CS HPI Composite - 20 n.s.a. (YoY) (Aug) | Medium |
| 09:00 | S&P/CS HPI Composite - 20 n.s.a. (MoM) (Aug) | Medium |
| 10:00 | CB Consumer Confidence (Oct) | High |
| 10:00 | New Home Sales (MoM) (Sep) | Medium |
| 10:00 | New Home Sales (Sep) | High |
| 11:40 | Atlanta Fed GDPNow (Q3) | Medium |
| 13:00 | 5-Year Note Auction | Medium |
| 13:00 | ECB President Lagarde Speaks | Medium |
| 16:30 | API Weekly Crude Oil Stock | Medium |
| 20:15 | RBA Assist Gov Bullock Speaks | Medium |
| 20:30 | CPI (QoQ) (Q3) | Medium |
| 20:30 | CPI (YoY) (Q3) | Medium |
| 20:30 | Trimmed Mean CPI (QoQ) (Q3) | Medium |
| 21:00 | RBNZ Interest Rate Decision | High |
| 21:00 | RBNZ Rate Statement | Medium |
| 22:00 | RBNZ Press Conference | Medium |
A series of significant economic events are scheduled, including the release of key inflation indicators such as the BoJ Core CPI and various CPI measures from Australia and New Zealand, which could influence central bank policies and market expectations. Additionally, U.S. data on building permits, durable goods orders, and consumer confidence will provide insights into economic health and may impact equity and bond markets. The RBNZ's interest rate decision and subsequent press conference will be closely watched for signals on future monetary policy, potentially affecting the New Zealand dollar and regional markets.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.