European Markets Up: EuroStoxx 50 Rises 0.62% — Positive Momentum Ahead of US Close
MarketsFN Team
European markets approaching close (still trading) • US markets actively trading • Analysis based on last 8 hours
📊 Market Overview
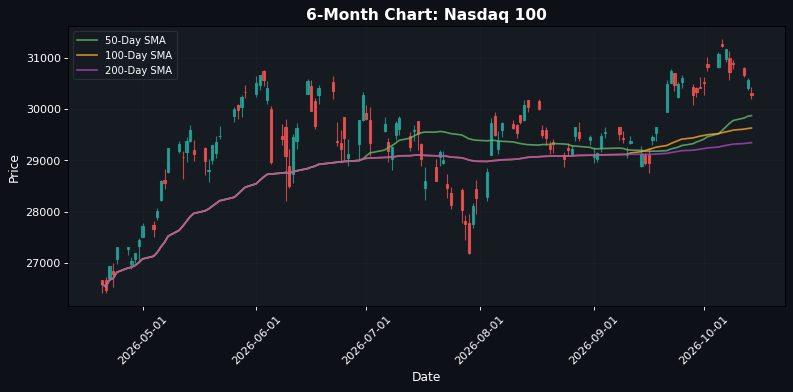
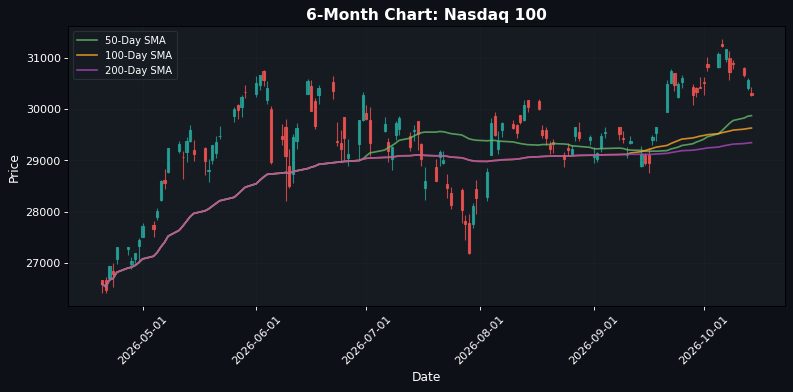
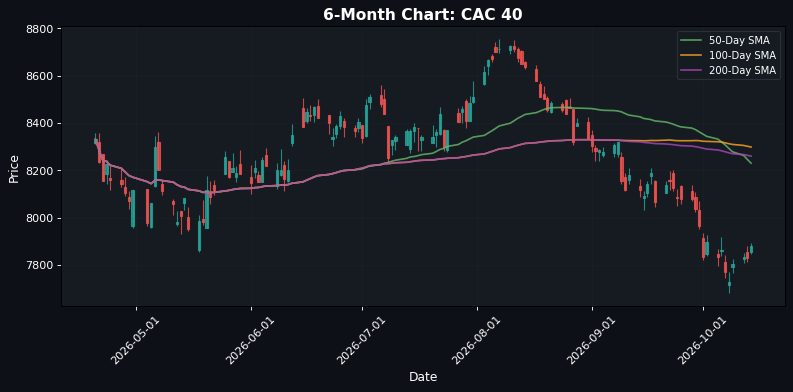
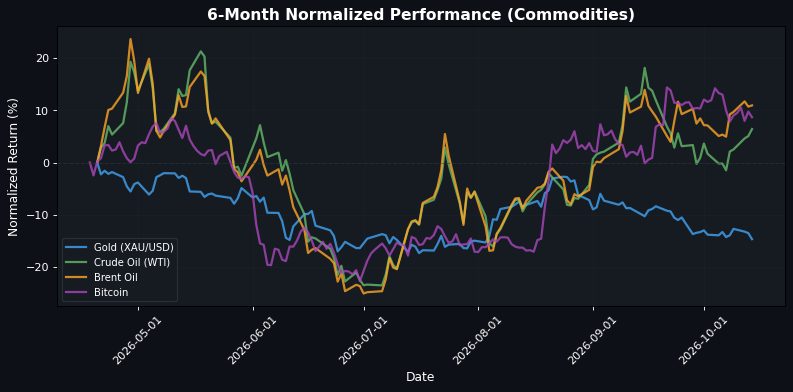
**European Markets Rally While US Indices Struggle Amid Mixed Sentiment** As European markets approach the close, a notable divergence is evident between the robust performance of European indices and the struggles of US markets. The EuroStoxx 50 rose by +0.62% to 6205.19, with the DAX and CAC 40 also showing strength, up +0.61% to 25415.05 and +0.66% to 7879.21, respectively. This positive momentum contrasts sharply with the US indices, where the S&P 500 is down -0.57% at 7760.84, and the Nasdaq 100 has fallen -0.98% to 30269.26, indicating a risk-off sentiment among US investors. The mixed performance can be attributed to a stronger dollar, with the EUR/USD trading at 1.1121, down -0.72%, and the GBP/USD at 1.3172, down -0.61%. This dollar strength is impacting commodities, as gold prices have dipped -1.35% to 4121.1001, while crude oil has seen a modest gain of +1.29% to 95.3500, reflecting ongoing supply concerns amid geopolitical tensions. The divergence in market performance suggests that European equities may be underpricing the potential for continued economic recovery, especially as the region shows resilience in the face of global headwinds. Conversely, US markets appear to be reacting to tighter monetary policy expectations, which could be weighing on investor sentiment. Looking ahead, the upcoming US employment data release will be a critical catalyst. A stronger-than-expected jobs report could further pressure US indices, while a weaker report might provide a much-needed boost to market confidence and potentially align US performance more closely with the positive trends seen in Europe.
🇪🇺 European Markets (Approaching Close)
| Name | Price | Daily (%) |
|---|---|---|
| EuroStoxx 50 | 6205.19 | +0.62% |
| DAX | 25415.05 | +0.61% |
| FTSE 100 | 10688.39 | +0.36% |
| CAC 40 | 7879.21 | +0.66% |
| FTSE MIB | 49872.54 | -0.37% |
| IBEX 35 | 19200.80 | -0.05% |
🇺🇸 US Markets (Currently Active)
| Name | Price | Daily (%) |
|---|---|---|
| S&P 500 | 7760.84 | -0.57% |
| Dow Jones | 51718.97 | +0.09% |
| Nasdaq 100 | 30269.26 | -0.98% |
🌏 Asian Markets
| Name | Price | Daily (%) |
|---|---|---|
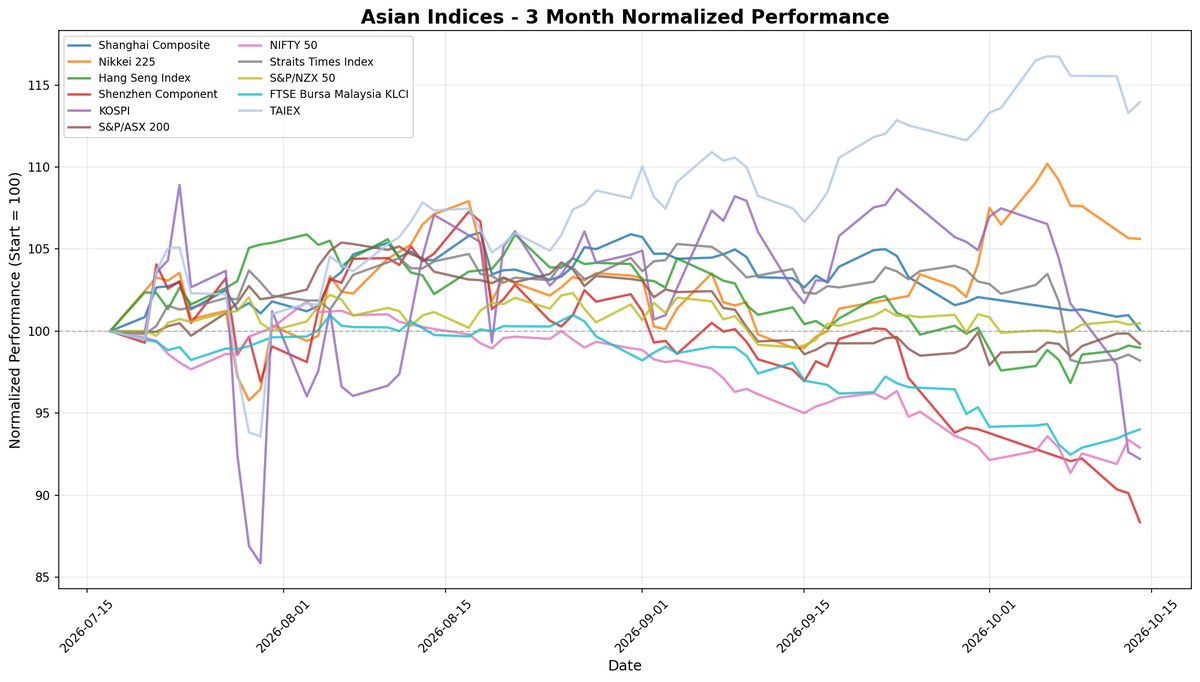
| Nikkei 225 | 67744.29 | -0.05% |
| Shanghai Composite | 3767.23 | -0.89% |
| Hang Seng | 24314.17 | -0.13% |
💱 FX & Commodities
| Name | Price | Daily (%) |
|---|---|---|
| EUR/USD | 1.11 | -0.72% |
| GBP/USD | 1.32 | -0.61% |
| USD/JPY | 158.92 | +0.38% |
| Gold (XAU/USD) | 4121.10 | -1.35% |
| Crude Oil (WTI) | 95.35 | +1.29% |
| Brent Oil | 105.91 | +0.21% |
| Bitcoin | 82290.96 | -0.97% |
🌍 Geopolitics and Market Drivers
Recent geopolitical tensions, particularly the ongoing conflict in Ukraine and escalating tensions in the South China Sea, are significantly impacting market sentiment. The U.S. has reaffirmed its support for Ukraine, which could lead to prolonged instability in Europe and affect energy prices. Additionally, China's military maneuvers near Taiwan have raised concerns about potential disruptions in global supply chains. On the macroeconomic front, central banks are signaling a cautious approach to interest rate policies. The Federal Reserve's recent comments suggest a potential pause in rate hikes, reflecting concerns about economic growth amid persistent inflation. Meanwhile, the European Central Bank is grappling with similar inflationary pressures, which could influence its monetary policy decisions. Economic data releases, including U.S. job growth and inflation figures, are closely monitored as they provide insights into the health of the economy. A stronger-than-expected jobs report could bolster the Fed's confidence in pausing rate hikes, while disappointing data may prompt a reassessment of economic forecasts. Overall, these factors create a complex landscape for investors, with heightened volatility expected in response to geopolitical and economic developments.
📅 Today's Economic Calendar
All times are in US Eastern Time (ET)
| Time (ET) | Event | Importance |
|---|---|---|
| 01:30 | BoE Gov Bailey Speaks | Medium |
| 02:00 | BoE MPC Member Pill Speaks | Medium |
| 02:05 | BoC Gov Macklem Speaks | Medium |
| 02:30 | WPI Inflation (YoY) (Sep) | Medium |
| 03:00 | Spanish CPI (YoY) (Sep) | Medium |
| 03:00 | Spanish HICP (YoY) (Sep) | Medium |
| 04:00 | New Loans (Sep) | Medium |
| 04:00 | ECB's Elderson Speaks | Medium |
| 04:15 | German Buba Vice President Buch Speaks | Medium |
| 04:30 | ECB President Lagarde Speaks | Medium |
| 05:00 | IEA Monthly Report | Medium |
| 05:40 | FOMC Member Bowman Speaks | Medium |
| 06:00 | Euro Summit | Medium |
| 08:30 | Core CPI (MoM) (Sep) | High |
| 08:30 | Core CPI (YoY) (Sep) | Medium |
| 08:30 | CPI (MoM) (Sep) | High |
| 08:30 | CPI (YoY) (Sep) | High |
| 08:30 | Building Permits (MoM) (Aug) | Medium |
| 09:30 | US Leading Index (MoM) | Medium |
| 12:15 | ECB's Schnabel Speaks | Medium |
| 14:00 | Beige Book | Medium |
| 16:30 | API Weekly Crude Oil Stock | Medium |
| 20:30 | Employment Change (Sep) | Medium |
| 20:30 | Full Employment Change (Sep) | Medium |
| 20:30 | Unemployment Rate (Sep) | Medium |
| 22:45 | German Buba Vice President Buch Speaks | Medium |
| 22:55 | FOMC Member Bowman Speaks | Medium |
| 23:00 | Federal Budget Balance (Sep) | Medium |
| 23:40 | BoE Deputy Governor Woods Speaks | Medium |
| 23:40 | BoE MPC Member Pill Speaks | Medium |
A series of significant speeches from central bank officials, including the Bank of England (BoE) and the European Central Bank (ECB), alongside key inflation and employment data releases, are expected to create volatility in the markets. The focus will be on the Core CPI and CPI figures from the U.S., which could influence monetary policy expectations, while comments from central bank leaders may provide insights into future interest rate decisions. Overall, these events could lead to heightened market reactions, particularly in currency and bond markets, as investors assess the implications for economic growth and inflation.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.