European Markets Up: EuroStoxx 50 Rises 0.36% — Positive Momentum Ahead of US Trading
MarketsFN Team
European markets approaching close (still trading) • US markets actively trading • Analysis based on last 8 hours
📊 Market Overview
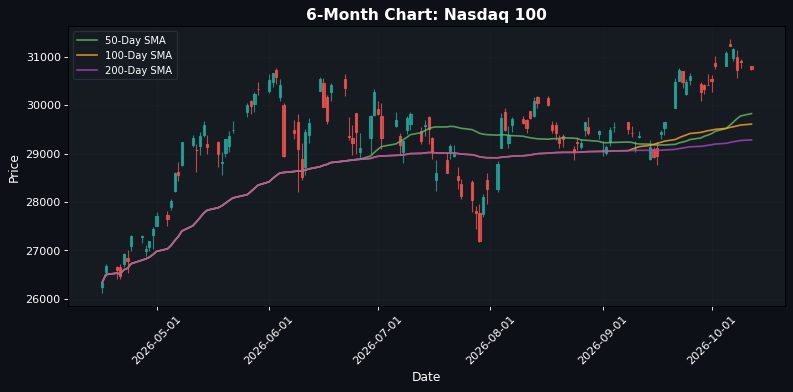
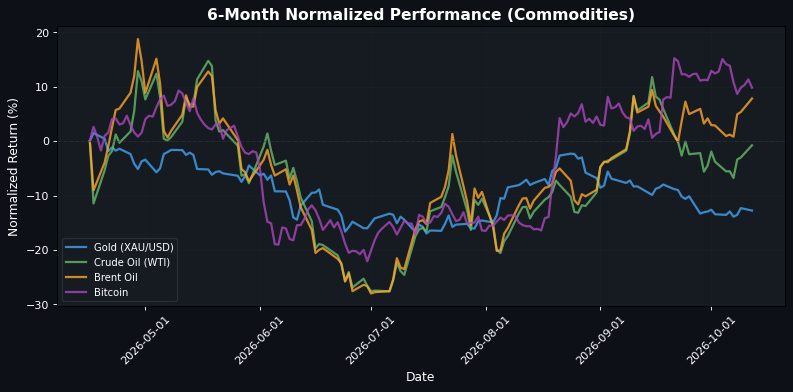
**European Markets Show Resilience Amid Mixed US Performance** European indices are closing the day with a notable degree of resilience, led by the DAX, which gained +0.78% to reach 25283.32, and the FTSE 100, up +0.76% at 10632.56. The EuroStoxx 50 also saw a modest increase of +0.36%, closing at 6195.82. This positive momentum contrasts sharply with the mixed performance in the US markets, where the S&P 500 remains flat at 7811.72, while the Nasdaq 100 is down -0.47% at 30738.98, reflecting investor caution amid ongoing economic uncertainties. The divergence in performance can be attributed to the stronger showing in European commodities, particularly crude oil, which surged +2.31% to $93.9700 for WTI and +2.34% for Brent at $107.1700. This uptick in oil prices is likely providing a boost to European energy stocks, which are benefiting from heightened demand and supply constraints. In contrast, the US markets are grappling with mixed signals from tech stocks, which are under pressure as investors reassess growth prospects. In the FX markets, the EUR/USD pair is slightly down by -0.08% at 1.1179, reflecting a cautious sentiment as traders digest the implications of rising commodity prices on inflation. Meanwhile, gold prices fell -0.51% to $4195.0000, indicating a shift in investor preference towards riskier assets amid the oil rally. Looking ahead, the upcoming US employment data release will be a critical catalyst. A stronger-than-expected jobs report could shift market sentiment, potentially lifting the S&P 500 and Nasdaq 100, while a disappointing figure may exacerbate the current volatility in tech stocks.
🇪🇺 European Markets (Approaching Close)
| Name | Price | Daily (%) |
|---|---|---|
| EuroStoxx 50 | 6195.82 | +0.36% |
| DAX | 25283.32 | +0.78% |
| FTSE 100 | 10632.56 | +0.76% |
| CAC 40 | 7822.02 | +0.24% |
| FTSE MIB | 49950.86 | +0.41% |
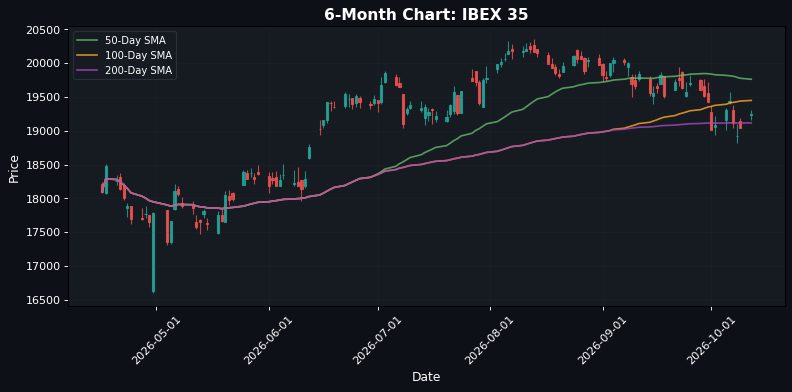
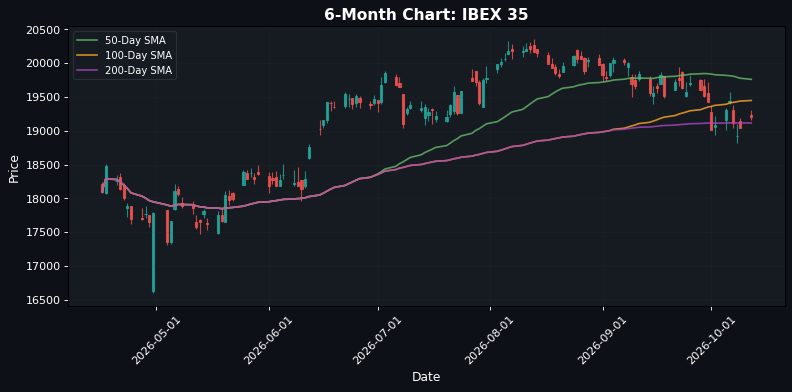
| IBEX 35 | 19207.20 | +0.91% |
🇺🇸 US Markets (Currently Active)
| Name | Price | Daily (%) |
|---|---|---|
| S&P 500 | 7811.72 | +0.00% |
| Dow Jones | 51772.60 | +0.23% |
| Nasdaq 100 | 30738.98 | -0.47% |
🌏 Asian Markets
| Name | Price | Daily (%) |
|---|---|---|
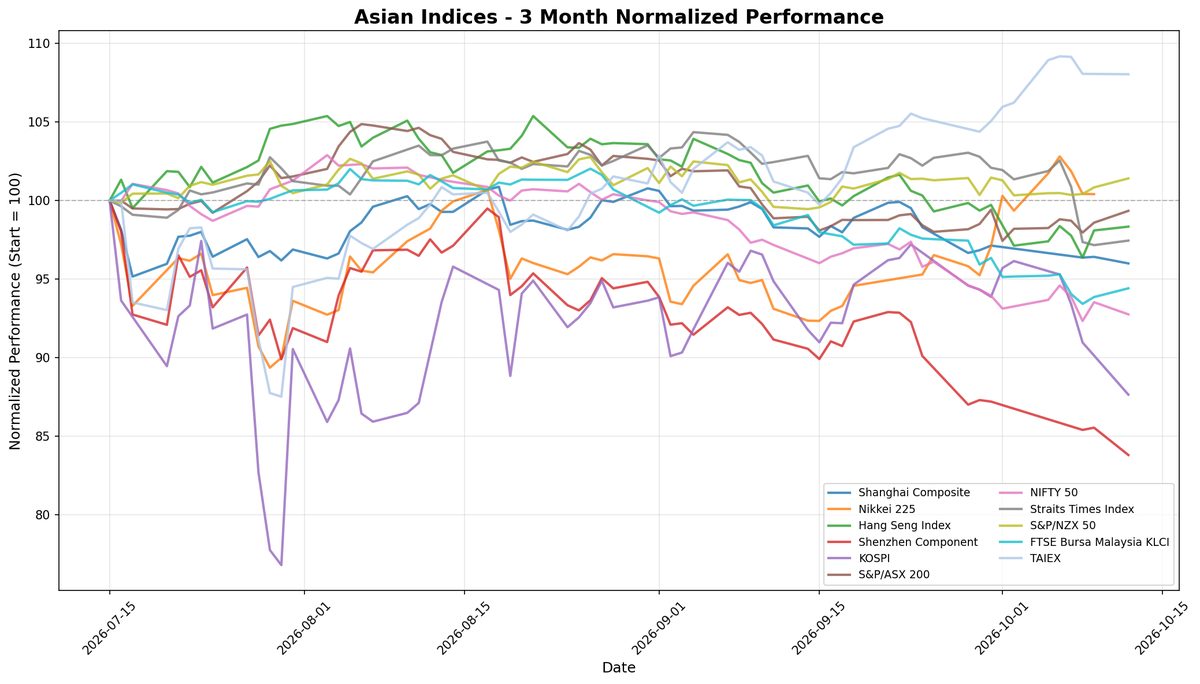
| Nikkei 225 | 69030.92 | -0.02% |
| Shanghai Composite | 3797.24 | -0.43% |
| Hang Seng | 24271.20 | +0.25% |
💱 FX & Commodities
| Name | Price | Daily (%) |
|---|---|---|
| EUR/USD | 1.12 | -0.08% |
| GBP/USD | 1.32 | -0.06% |
| USD/JPY | 158.64 | +0.27% |
| Gold (XAU/USD) | 4195.00 | -0.51% |
| Crude Oil (WTI) | 93.97 | +2.31% |
| Brent Oil | 107.17 | +2.34% |
| Bitcoin | 82534.05 | -1.37% |
🌍 Geopolitics and Market Drivers
Current market dynamics are heavily influenced by several key geopolitical and macroeconomic factors. Firstly, ongoing tensions in Eastern Europe, particularly surrounding Ukraine, continue to create uncertainty, impacting energy prices and supply chains. The potential for escalated conflict remains a concern for investors, particularly in the energy sector. On the central bank front, the Federal Reserve's recent signals indicate a cautious approach to interest rate hikes, with policymakers emphasizing the need for data-driven decisions. This has led to mixed reactions in equity markets, as investors weigh the implications of prolonged low rates against inflationary pressures. Economic data releases have shown a mixed bag; while employment figures remain robust, inflation data suggests persistent price pressures, complicating the Fed's path forward. Politically, the upcoming elections in key regions, including the U.S. and Europe, are creating additional volatility, as shifts in power could lead to changes in fiscal policies and international relations. Overall, these factors contribute to a cautious market sentiment, with investors closely monitoring developments for potential impacts on growth and stability.
📅 Today's Economic Calendar
All times are in US Eastern Time (ET)
| Time (ET) | Event | Importance |
|---|---|---|
| 03:00 | Turkish Retail Sales (MoM) (Aug) | Medium |
| 03:00 | Turkish Retail Sales (YoY) (Aug) | Medium |
| 06:30 | CPI (YoY) (Sep) | Medium |
| 08:50 | BoE MPC Member Mann Speaks | Medium |
| 19:01 | BRC Retail Sales Monitor (YoY) (Sep) | Medium |
| 20:30 | RBA Meeting Minutes | Medium |
| 20:30 | NAB Business Confidence (Sep) | Medium |
The release of Turkish retail sales data for August, both month-on-month and year-on-year, may indicate consumer spending trends and influence the Turkish lira's performance. Additionally, the CPI data for September will provide insights into inflationary pressures in Turkey, potentially impacting monetary policy decisions. In the UK, comments from BoE MPC member Mann and the BRC retail sales monitor could affect market sentiment regarding the Bank of England's interest rate outlook, while the RBA meeting minutes and NAB business confidence data will shed light on Australia's economic health and future policy direction.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.