European Markets Rise: IBEX 35 Up 0.77% — Positive Momentum Ahead of US Trading
MarketsFN Team
🌍 European Markets Rise: IBEX 35 Up 0.77% — Positive Momentum Ahead of US Trading
European markets approaching close (still trading) • US markets actively trading • Analysis based on last 8 hours
📊 Market Overview
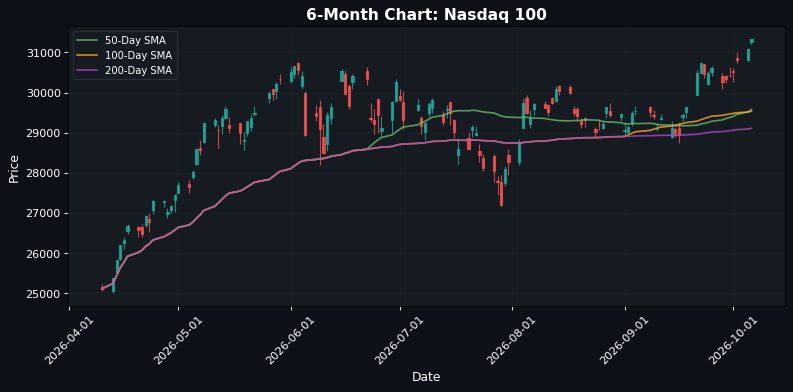
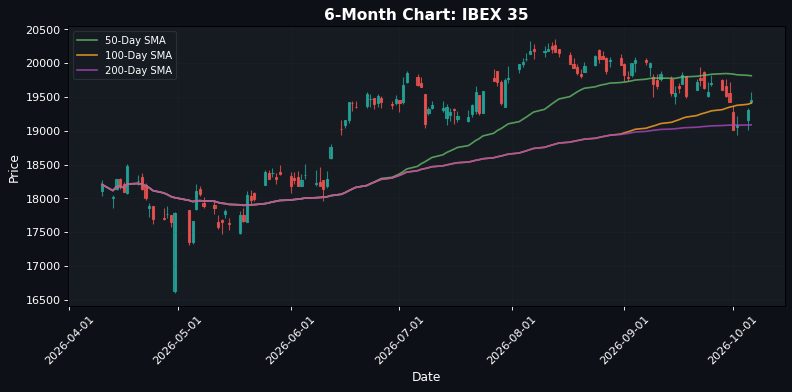
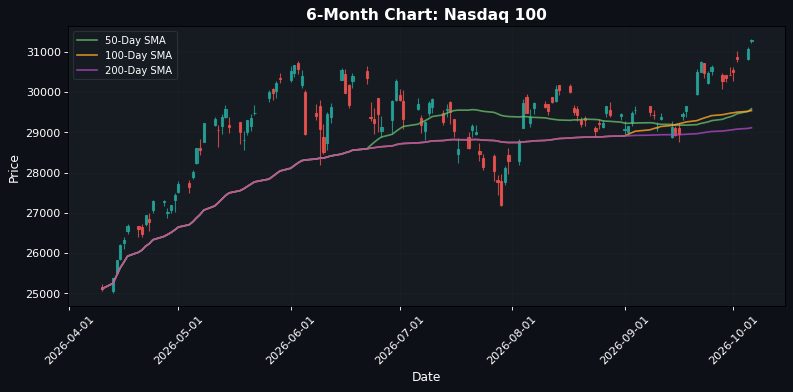
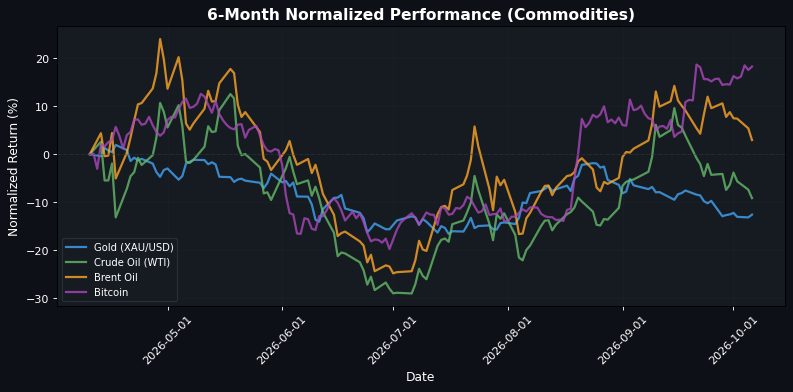
**European Markets Rally as US Indices Gain Momentum Amid Mixed Commodity Signals** European indices are closing on a high note, with the EuroStoxx 50 up +0.40% at 6267.15, reflecting a broad-based rally across the continent. The DAX gained +0.54% to 25390.14, while the FTSE MIB led the pack with a +0.55% increase to 51095.55. The IBEX 35 also showed strength, rising +0.77% to 19448.60. This upward momentum is mirrored in the US markets, where the S&P 500 is up +0.69% at 7827.86, and the Nasdaq 100 has advanced +0.72% to 31299.97. The Dow Jones follows closely with a +0.68% increase to 51617.61. The positive sentiment in equities contrasts sharply with the commodity markets, where crude oil prices are under pressure. WTI crude has dropped -1.90% to $87.73, and Brent oil is down -2.31% to $98.00. This divergence suggests that while equity investors are optimistic, they may be underpricing the potential impact of declining oil prices on inflation and economic growth. In the FX markets, the euro is appreciating against the dollar, with EUR/USD up +0.26% at 1.1254, while GBP/USD is also up +0.35% at 1.3268. This strengthening of the euro and pound indicates a potential shift in investor sentiment towards European assets. Looking ahead, the upcoming US employment data release will be a critical catalyst. A stronger-than-expected jobs report could further bolster equity markets, while a weaker report might reignite concerns over economic growth and inflation, impacting both equities and commodities. Investors should prepare for volatility as these figures are released.
🇪🇺 European Markets (Approaching Close)
| Name | Price | Daily (%) |
|---|---|---|
| EuroStoxx 50 | 6267.15 | +0.40% |
| DAX | 25390.14 | +0.54% |
| FTSE 100 | 10520.94 | +0.22% |
| CAC 40 | 7856.43 | +0.29% |
| FTSE MIB | 51095.55 | +0.55% |
| IBEX 35 | 19448.60 | +0.77% |
🇺🇸 US Markets (Currently Active)
| Name | Price | Daily (%) |
|---|---|---|
| S&P 500 | 7827.86 | +0.69% |
| Dow Jones | 51617.61 | +0.68% |
| Nasdaq 100 | 31299.97 | +0.72% |
🌏 Asian Markets
| Name | Price | Daily (%) |
|---|---|---|
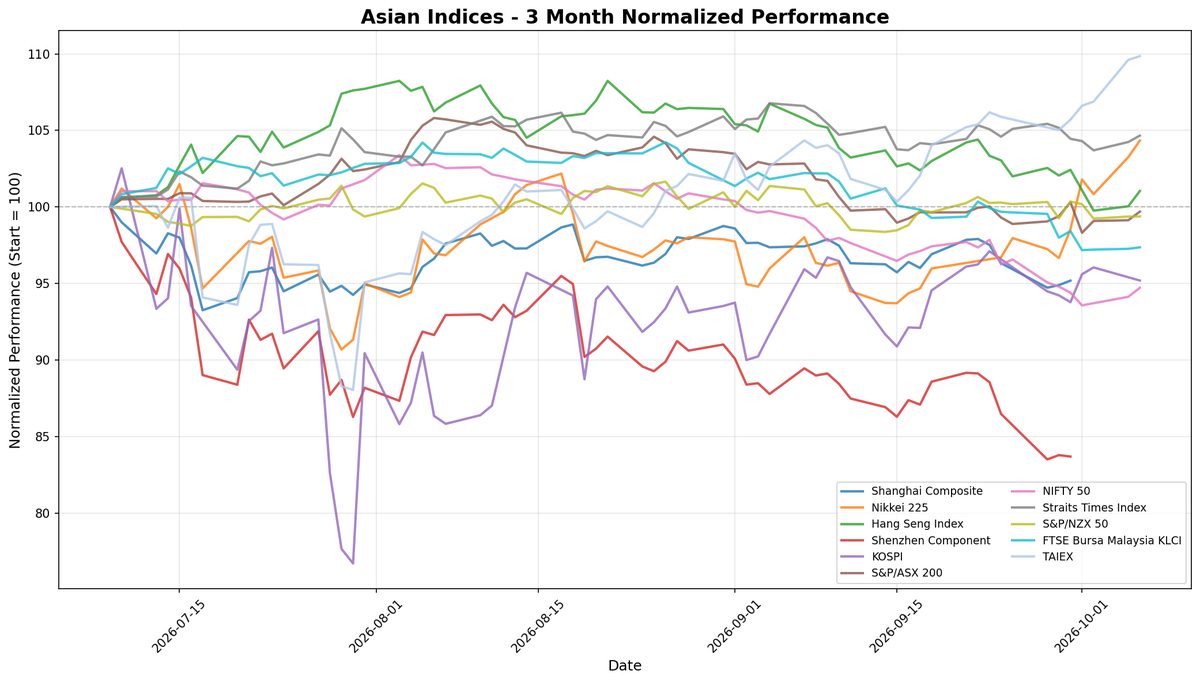
| Nikkei 225 | 70683.98 | +1.05% |
| Shanghai Composite | 3842.20 | +0.31% |
| Hang Seng | 24280.56 | +1.00% |
💱 FX & Commodities
| Name | Price | Daily (%) |
|---|---|---|
| EUR/USD | 1.13 | +0.26% |
| GBP/USD | 1.33 | +0.35% |
| USD/JPY | 158.10 | +0.15% |
| Gold (XAU/USD) | 4184.40 | +0.66% |
| Crude Oil (WTI) | 87.73 | -1.90% |
| Brent Oil | 98.00 | -2.31% |
| Bitcoin | 86294.28 | +0.59% |
🌍 Geopolitics and Market Drivers
Current market dynamics are heavily influenced by several key geopolitical and macroeconomic factors. The ongoing conflict in Ukraine continues to escalate, with recent reports of intensified military actions, raising concerns about energy supply disruptions in Europe. This situation is compounded by the potential for further sanctions against Russia, which could impact global oil prices. Central banks are also in focus, particularly the U.S. Federal Reserve, which signaled a potential pause in interest rate hikes amid mixed economic data. The latest inflation figures showed a slight decrease, but core inflation remains stubbornly high, complicating the Fed's decision-making process. Additionally, the release of U.S. employment data indicated a stronger-than-expected job market, which could lead to renewed speculation about future rate increases. Political developments in the U.S. surrounding the debt ceiling negotiations are creating uncertainty, with potential implications for fiscal policy and market stability. Overall, these factors contribute to heightened volatility, with investors closely monitoring developments for directional cues.
📅 Today's Economic Calendar
All times are in US Eastern Time (ET)
| Time (ET) | Event | Importance |
|---|---|---|
| 02:00 | German Factory Orders (MoM) (Aug) | Medium |
| 04:30 | BoE MPC Member Mann Speaks | Medium |
| 04:30 | S&P Global Construction PMI (Sep) | Medium |
| 07:40 | German Buba Vice President Buch Speaks | Medium |
| 08:14 | ADP Employment Change Weekly | Medium |
| 08:15 | ADP Employment Change Weekly | Medium |
| 08:30 | Exports (Aug) | Medium |
| 08:30 | Imports (Aug) | Medium |
| 08:30 | Trade Balance (Aug) | Medium |
| 08:30 | Trade Balance (Aug) | Medium |
| 09:00 | ECB's Elderson Speaks | Medium |
| 09:05 | FOMC Member Williams Speaks | Medium |
| 10:00 | Ivey PMI (Sep) | Medium |
| 10:45 | FOMC Member Bowman Speaks | Medium |
| 11:30 | Atlanta Fed GDPNow (Q3) | Medium |
| 12:00 | EIA Short-Term Energy Outlook | Medium |
| 13:00 | 3-Year Note Auction | Medium |
| 16:30 | API Weekly Crude Oil Stock | Medium |
| 20:30 | Building Approvals (MoM) (Aug) | Medium |
| 21:05 | FOMC Member Williams Speaks | Medium |
Today's economic events include key indicators such as German Factory Orders and the ADP Employment Change, which could influence market sentiment regarding economic growth and employment trends. Speeches from various central bank officials, including members of the BoE and FOMC, may provide insights into future monetary policy, potentially impacting currency and bond markets. Additionally, trade balance data and construction PMI figures will be closely monitored for their implications on trade dynamics and construction activity, further shaping market expectations.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.