European Markets Decline: EuroStoxx 50 Down 1.09% — Weakness Ahead of US Open
MarketsFN Team
🌍 European Markets Decline: EuroStoxx 50 Down 1.09% — Weakness Ahead of US Open
European markets approaching close (still trading) • US markets actively trading • Analysis based on last 8 hours
📊 Market Overview
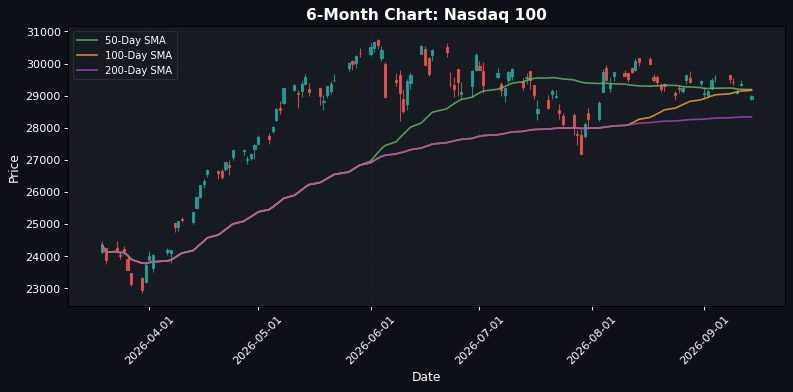
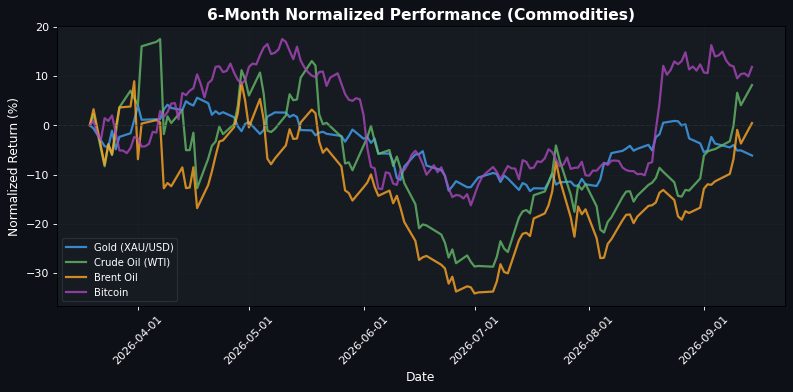
**European Markets Struggle Amidst Broader Risk Aversion; US Indices Follow Suit** As European markets approach the close, a prevailing risk-off sentiment has led to notable declines across major indices. The EuroStoxx 50 is down 1.09% at 6256.25, with the DAX and CAC 40 also reflecting this trend, falling 0.46% to 25450.92 and 0.75% to 8118.74, respectively. The FTSE 100 stands out with a modest gain of 0.59% at 10713.17, likely buoyed by strength in commodity-linked stocks as crude oil prices surge. In the US, the S&P 500 is down 0.56% at 7614.45, while the Nasdaq 100 experiences a sharper decline of 1.26% to 28997.36. This aligns with the broader theme of risk aversion, as investors digest mixed economic signals and geopolitical tensions. The Dow Jones is faring slightly better, down just 0.27% at 52432.74. In the FX markets, the euro is trading at 1.1529 against the dollar, down 0.62%, reflecting the overall bearish sentiment in European equities. Meanwhile, commodities are experiencing a divergence; crude oil prices are up significantly, with WTI gaining 3.93% to $103.98 and Brent oil up 4.32% to $109.13, likely driven by supply concerns and geopolitical factors. The market appears to be underpricing the potential for further volatility in energy prices, which could have cascading effects across sectors reliant on stable energy costs. A key forward-looking catalyst will be the upcoming US employment data, which could either reinforce or challenge the current market sentiment, influencing both equity and commodity prices significantly.
🇪🇺 European Markets (Approaching Close)
| Name | Price | Daily (%) |
|---|---|---|
| EuroStoxx 50 | 6256.25 | -1.09% |
| DAX | 25450.92 | -0.46% |
| FTSE 100 | 10713.17 | +0.59% |
| CAC 40 | 8118.74 | -0.75% |
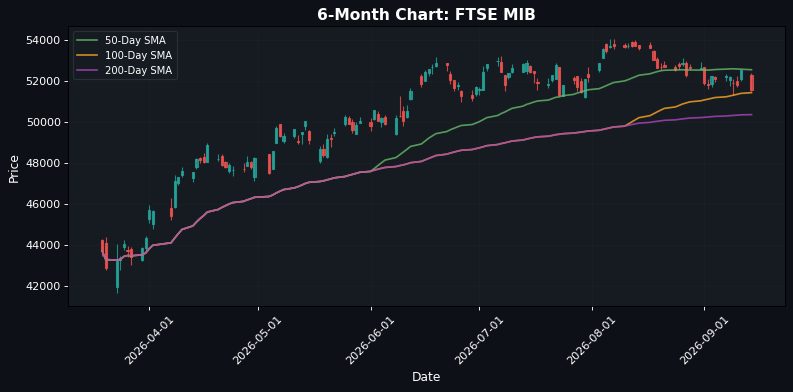
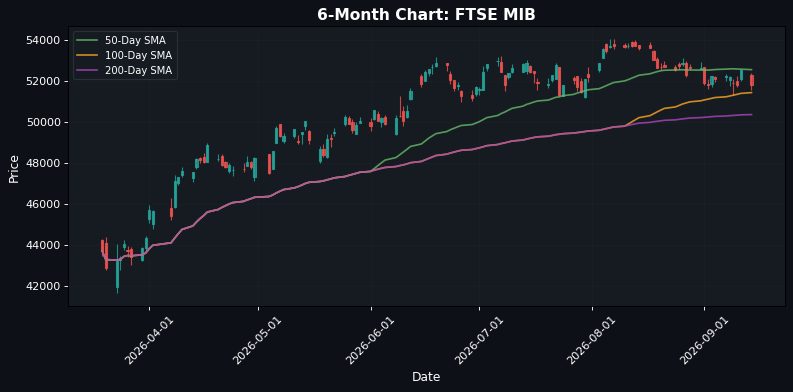
| FTSE MIB | 51794.85 | -1.37% |
| IBEX 35 | 19628.70 | -1.06% |
🇺🇸 US Markets (Currently Active)
| Name | Price | Daily (%) |
|---|---|---|
| S&P 500 | 7614.45 | -0.56% |
| Dow Jones | 52432.74 | -0.27% |
| Nasdaq 100 | 28997.36 | -1.26% |
🌏 Asian Markets
| Name | Price | Daily (%) |
|---|---|---|
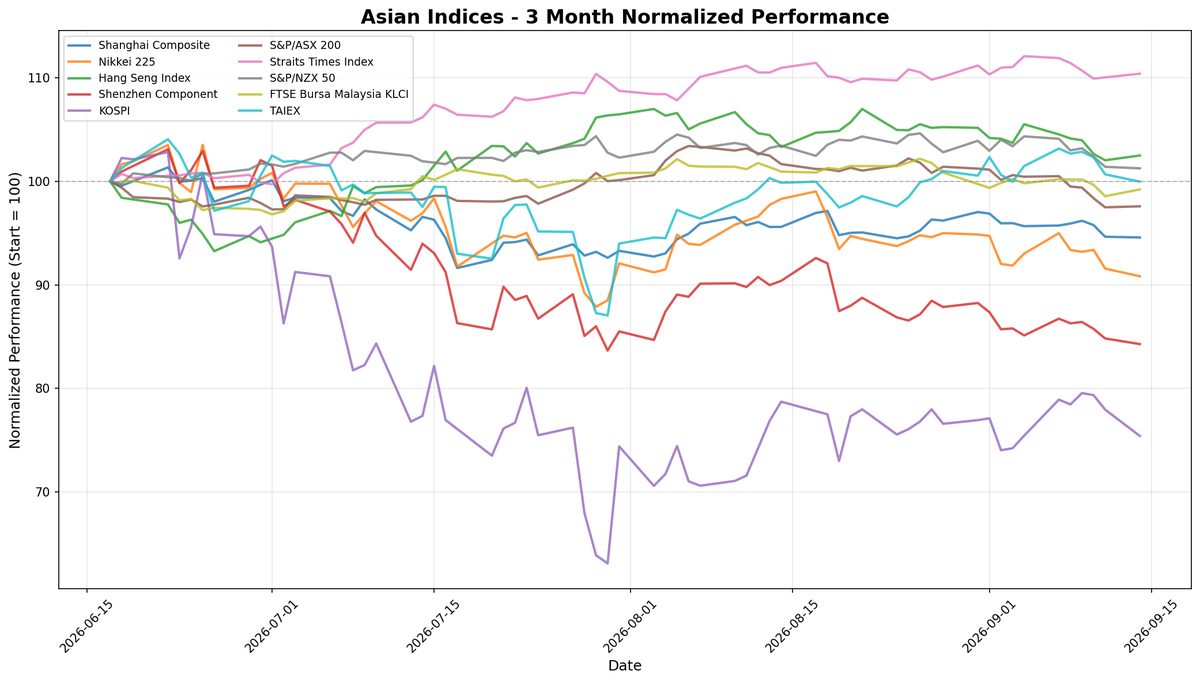
| Nikkei 225 | 63492.99 | -0.81% |
| Shanghai Composite | 3885.33 | -0.07% |
| Hang Seng | 24917.60 | +0.45% |
💱 FX & Commodities
| Name | Price | Daily (%) |
|---|---|---|
| EUR/USD | 1.15 | -0.62% |
| GBP/USD | 1.35 | -0.42% |
| USD/JPY | 154.93 | +0.90% |
| Gold (XAU/USD) | 4317.90 | -1.11% |
| Crude Oil (WTI) | 103.98 | +3.93% |
| Brent Oil | 109.13 | +4.32% |
| Bitcoin | 78189.64 | +1.76% |
🌍 Geopolitics and Market Drivers
Recent geopolitical tensions are primarily driven by escalating conflicts in Eastern Europe and the Middle East. The ongoing war in Ukraine continues to impact energy prices and supply chains, with European nations grappling with energy security as winter approaches. Additionally, the Israel-Hamas conflict has raised concerns about regional stability, potentially affecting oil prices and global markets. On the macroeconomic front, central banks are signaling a cautious approach. The Federal Reserve's recent statements indicate a potential pause in interest rate hikes, reflecting concerns over economic growth and inflation. Meanwhile, the European Central Bank is also navigating a delicate balance between combating inflation and supporting economic recovery. Recent economic data releases show mixed signals; U.S. job growth remains robust, but inflationary pressures persist, complicating the Fed's policy decisions. In contrast, China's economic recovery is slower than expected, raising questions about global demand. These factors collectively create a volatile market environment, with investors closely monitoring geopolitical developments and central bank actions for directional cues.
📅 Today's Economic Calendar
All times are in US Eastern Time (ET)
| Time (ET) | Event | Importance |
|---|---|---|
| 00:30 | Industrial Production (MoM) (Jul) | Medium |
| 02:30 | PPI (MoM) (Aug) | Medium |
| 02:30 | WPI Inflation (YoY) (Aug) | Medium |
| 04:00 | New Loans (Aug) | Medium |
| 05:15 | ECB's Schnabel Speaks | Medium |
| 06:30 | CPI (YoY) (Aug) | Medium |
| 08:30 | Core CPI (YoY) (Aug) | Medium |
| 08:30 | Core CPI (MoM) (Aug) | Medium |
| 08:30 | CPI (MoM) (Aug) | Medium |
| 11:15 | ECB President Lagarde Speaks | Medium |
| 18:45 | Electronic Card Retail Sales (MoM) (Aug) | Medium |
| 22:00 | Fixed Asset Investment (YoY) (Aug) | Medium |
| 22:00 | Industrial Production (YoY) (Aug) | Medium |
| 22:00 | Chinese Industrial Production YTD (YoY) (Aug) | Medium |
| 22:00 | Chinese Unemployment Rate (Aug) | Medium |
| 22:00 | NBS Press Conference | Medium |
A series of significant economic indicators will be released, including industrial production, PPI, CPI, and new loans, which are likely to provide insights into inflationary pressures and overall economic health. The speeches from ECB officials, particularly President Lagarde, may influence market sentiment regarding future monetary policy. Additionally, China's economic data, including fixed asset investment and unemployment rates, will be closely monitored for signs of recovery or weakness, potentially impacting global markets.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.