European Markets Decline: EuroStoxx 50 Down 0.86% — Bearish Sentiment Prevails.
MarketsFN Team
🌍 European Markets Decline: EuroStoxx 50 Down 0.86% — Bearish Sentiment Prevails.
European markets approaching close (still trading) • US markets actively trading • Analysis based on last 8 hours
📊 Market Overview
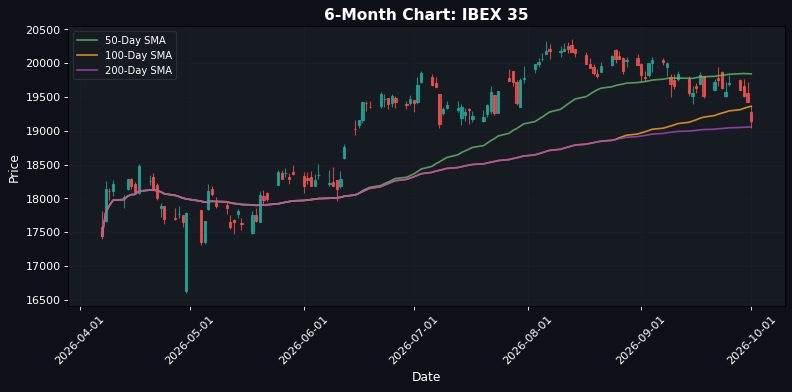
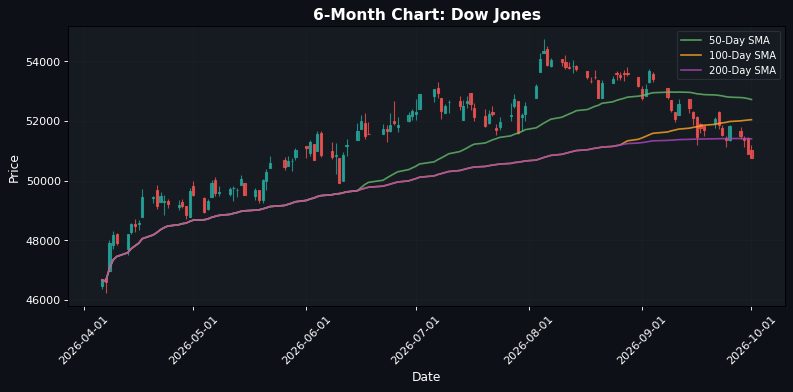
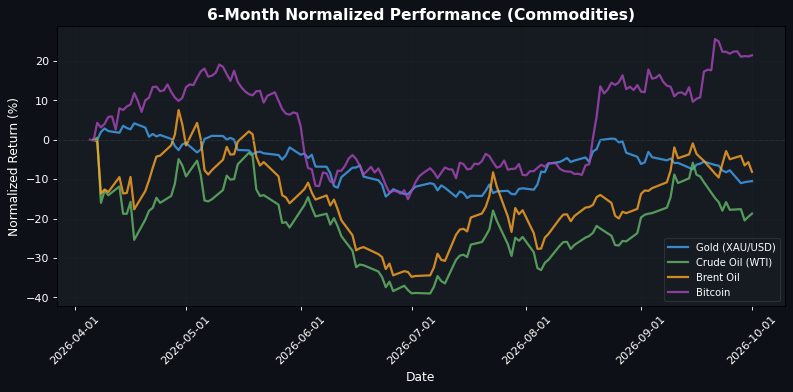
**European Markets Under Pressure as US Indices Show Divergence** European indices are closing the day on a negative note, with the EuroStoxx 50 down by 0.86% at 6214.88, reflecting broader concerns over economic stability. The DAX fell 0.47% to 25081.53, while the FTSE 100 experienced a sharper decline of 1.37%, settling at 10460.70. The CAC 40 and FTSE MIB also faced losses, down 1.21% and 1.44% respectively, indicating a pervasive bearish sentiment across the continent. In contrast, the IBEX 35 saw a decline of 1.45%, highlighting the challenges faced by European markets amid rising inflationary pressures and geopolitical tensions. Across the Atlantic, US indices are showing a mixed performance. The S&P 500 is slightly down by 0.05% at 7647.80, while the Dow Jones has dipped 0.30% to 50752.51. Notably, the Nasdaq 100 is bucking the trend with a modest gain of 0.16%, reaching 30458.12, suggesting a potential rotation into tech stocks as investors seek refuge from broader market volatility. In the FX and commodities space, the EUR/USD pair is trading at 1.1299, down 0.29%, reflecting the euro's weakness against the dollar. Meanwhile, crude oil prices are showing resilience, with WTI up 1.00% at 91.3200, despite Brent oil falling 2.63% to 100.8100. This divergence in oil prices could signal underlying supply concerns that may impact inflation trajectories. Looking ahead, the market will be closely watching upcoming economic data releases, particularly the US inflation figures, which could provide clarity on the Federal Reserve's monetary policy direction and further influence market sentiment.
🇪🇺 European Markets (Approaching Close)
| Name | Price | Daily (%) |
|---|---|---|
| EuroStoxx 50 | 6214.88 | -0.86% |
| DAX | 25081.53 | -0.47% |
| FTSE 100 | 10460.70 | -1.37% |
| CAC 40 | 7868.38 | -1.21% |
| FTSE MIB | 50631.40 | -1.44% |
| IBEX 35 | 19143.70 | -1.45% |
🇺🇸 US Markets (Currently Active)
| Name | Price | Daily (%) |
|---|---|---|
| S&P 500 | 7647.80 | -0.05% |
| Dow Jones | 50752.51 | -0.30% |
| Nasdaq 100 | 30458.12 | +0.16% |
🌏 Asian Markets
| Name | Price | Daily (%) |
|---|---|---|
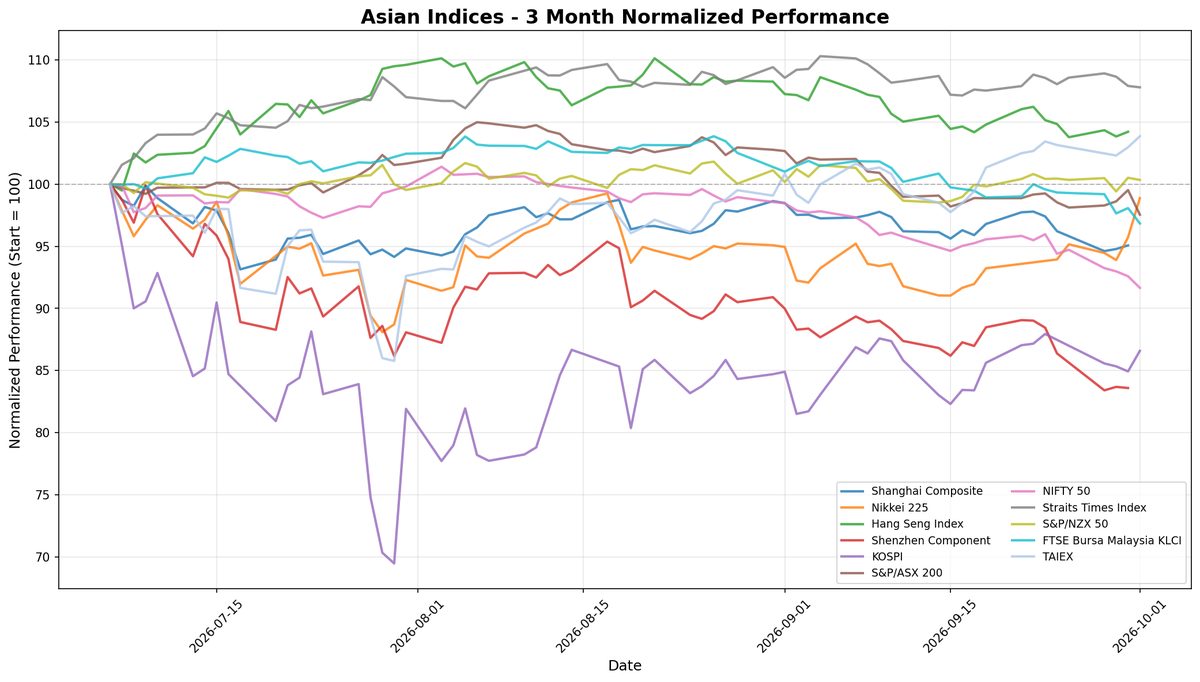
| Nikkei 225 | 68956.72 | +3.30% |
| Shanghai Composite | 3842.20 | +0.31% |
| Hang Seng | 24613.27 | +0.37% |
💱 FX & Commodities
| Name | Price | Daily (%) |
|---|---|---|
| EUR/USD | 1.13 | -0.29% |
| GBP/USD | 1.32 | -0.24% |
| USD/JPY | 158.02 | +0.44% |
| Gold (XAU/USD) | 4192.30 | +0.13% |
| Crude Oil (WTI) | 91.32 | +1.00% |
| Brent Oil | 100.81 | -2.63% |
| Bitcoin | 83759.01 | +0.25% |
🌍 Geopolitics and Market Drivers
Recent geopolitical tensions, particularly the ongoing conflict in Ukraine and escalating tensions in the South China Sea, are creating uncertainty in global markets. The U.S. has reaffirmed its support for Ukraine, which may lead to further sanctions against Russia, impacting energy prices and supply chains. On the macroeconomic front, the Federal Reserve's recent signals indicate a potential pause in interest rate hikes, with officials emphasizing the need to assess the economic impact of previous increases. This dovish stance has led to a rally in equity markets as investors anticipate a more accommodative monetary policy. Additionally, the latest economic data releases show mixed signals: while U.S. job growth remains robust, inflation continues to be a concern, with the Consumer Price Index showing persistent upward pressure. Political developments, including the upcoming U.S. elections, are also influencing market sentiment, as uncertainty around fiscal policies and regulatory changes looms. Overall, these factors contribute to heightened volatility and cautious investor sentiment in the markets.
📅 Today's Economic Calendar
All times are in US Eastern Time (ET)
| Time (ET) | Event | Importance |
|---|---|---|
| 02:00 | Nationwide HPI (MoM) (Sep) | Medium |
| 02:00 | Nationwide HPI (YoY) (Sep) | Medium |
| 02:30 | CPI (MoM) (Sep) | Medium |
| 03:15 | HCOB Spain Manufacturing PMI (Sep) | Medium |
| 03:30 | procure.ch Manufacturing PMI (Sep) | Medium |
| 03:45 | HCOB Italy Manufacturing PMI (Sep) | Medium |
| 03:50 | HCOB France Manufacturing PMI (Sep) | Medium |
| 03:55 | HCOB Germany Manufacturing PMI (Sep) | Medium |
| 04:00 | BoE Gov Bailey Speaks | Medium |
| 04:00 | HCOB Eurozone Manufacturing PMI (Sep) | Medium |
| 04:30 | S&P Global Manufacturing PMI (Sep) | Medium |
| 05:00 | Unemployment Rate (Aug) | Medium |
| 06:35 | German Buba President Nagel Speaks | Medium |
| 08:00 | BoE MPC Member Mann Speaks | Medium |
| 08:30 | BoE MPC Member Pill Speaks | Medium |
| 08:30 | Continuing Jobless Claims | Medium |
| 08:30 | Initial Jobless Claims | High |
| 09:30 | ECB President Lagarde Speaks | Medium |
| 09:45 | S&P Global Manufacturing PMI (Sep) | High |
| 10:00 | Construction Spending (MoM) (Aug) | Medium |
| 10:00 | Fed Waller Speaks | Medium |
| 10:00 | ISM Manufacturing Employment (Sep) | Medium |
| 10:00 | ISM Manufacturing PMI (Sep) | High |
| 10:00 | ISM Manufacturing Prices (Sep) | High |
| 11:30 | Atlanta Fed GDPNow (Q3) | Medium |
| 11:30 | ECB's Schnabel Speaks | Medium |
| 15:00 | FOMC Member Bowman Speaks | Medium |
| 15:05 | BoC Senior Deputy Governor Rogers Speaks | Medium |
| 15:30 | FOMC Member Williams Speaks | Medium |
| 16:30 | Fed's Balance Sheet | Medium |
| 19:30 | Tokyo Core CPI (YoY) (Sep) | Medium |
A series of economic indicators and speeches from key financial figures are set to be released, including the Nationwide House Price Index (HPI), Consumer Price Index (CPI), and various Manufacturing PMIs across Europe, which could influence market sentiment regarding inflation and economic growth. The outcomes of these reports, especially the CPI and ISM Manufacturing PMI, will likely affect investor expectations for monetary policy adjustments by central banks, potentially leading to volatility in equity and bond markets. Additionally, speeches from central bank officials may provide further insight into future policy directions, impacting currency markets as well.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.