European Markets Decline: EuroStoxx 50 Down 0.63% — US Indices Show Strength Amidst Losses.
MarketsFN Team
🌍 European Markets Decline: EuroStoxx 50 Down 0.63% — US Indices Show Strength Amidst Losses.
European markets approaching close (still trading) • US markets actively trading • Analysis based on last 8 hours
📊 Market Overview
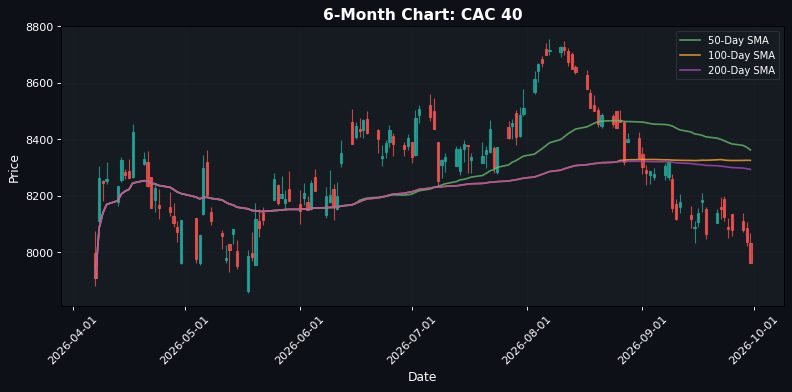
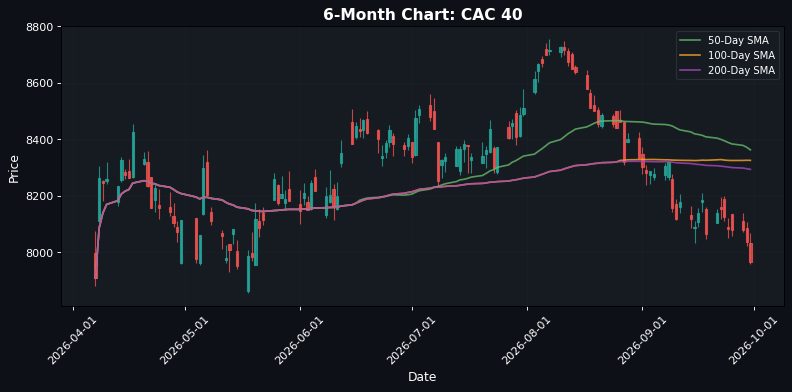
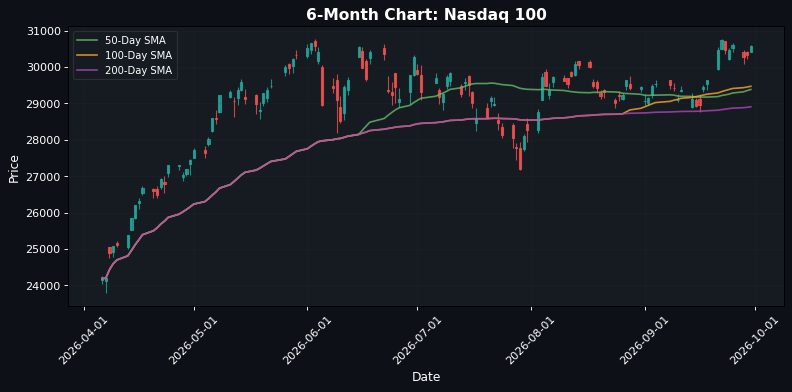
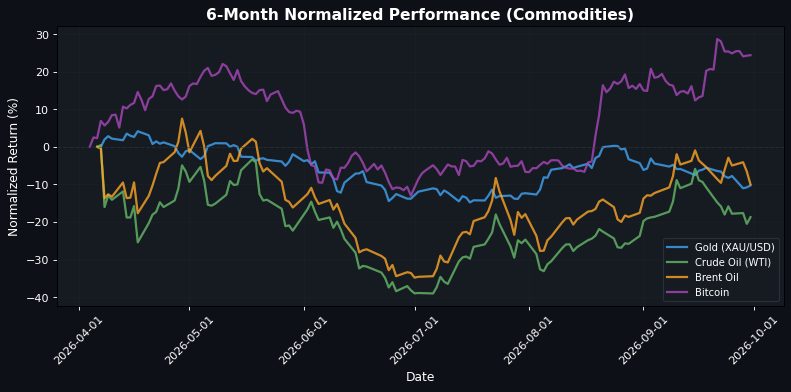
**European Markets Under Pressure Amid Mixed US Performance** As European markets approach the close, a prevailing sense of caution is evident, with the EuroStoxx 50 down 0.63% at 6280.33, reflecting broader regional weakness. The DAX and CAC 40 are also in the red, down 0.58% and 0.85%, respectively. This decline contrasts sharply with the US markets, where the S&P 500 is up 0.57% at 7714.28, indicating a divergence in sentiment across the Atlantic. The mixed performance in the US, particularly the Nasdaq 100's 0.78% gain at 30575.53, suggests that investors are selectively optimistic, possibly driven by tech sector resilience. However, the Dow Jones is only marginally higher, up 0.06% at 51383.15, indicating that broader economic concerns may be weighing on investor sentiment. In the FX markets, the EUR/USD pair is slightly up by 0.12% at 1.1361, while the GBP/USD has gained 0.42% to 1.3285, reflecting a modest strengthening of European currencies against the dollar. Commodities are showing mixed signals; while WTI crude oil has surged by 2.25% to 91.3900, Brent oil has dropped 3.67% to 98.8300, highlighting volatility in energy markets. The market may be underpricing the potential impact of upcoming economic data releases, particularly the US employment figures due later this week. A stronger-than-expected jobs report could further bolster US equities and shift sentiment in European markets, potentially reversing current trends. Investors should closely watch this catalyst as it could significantly influence market dynamics moving forward.
🇪🇺 European Markets (Approaching Close)
| Name | Price | Daily (%) |
|---|---|---|
| EuroStoxx 50 | 6280.33 | -0.63% |
| DAX | 25252.00 | -0.58% |
| FTSE 100 | 10622.75 | -0.13% |
| CAC 40 | 7967.40 | -0.85% |
| FTSE MIB | 51386.47 | -0.81% |
| IBEX 35 | 19476.20 | -0.21% |
🇺🇸 US Markets (Currently Active)
| Name | Price | Daily (%) |
|---|---|---|
| S&P 500 | 7714.28 | +0.57% |
| Dow Jones | 51383.15 | +0.06% |
| Nasdaq 100 | 30575.53 | +0.78% |
🌏 Asian Markets
| Name | Price | Daily (%) |
|---|---|---|
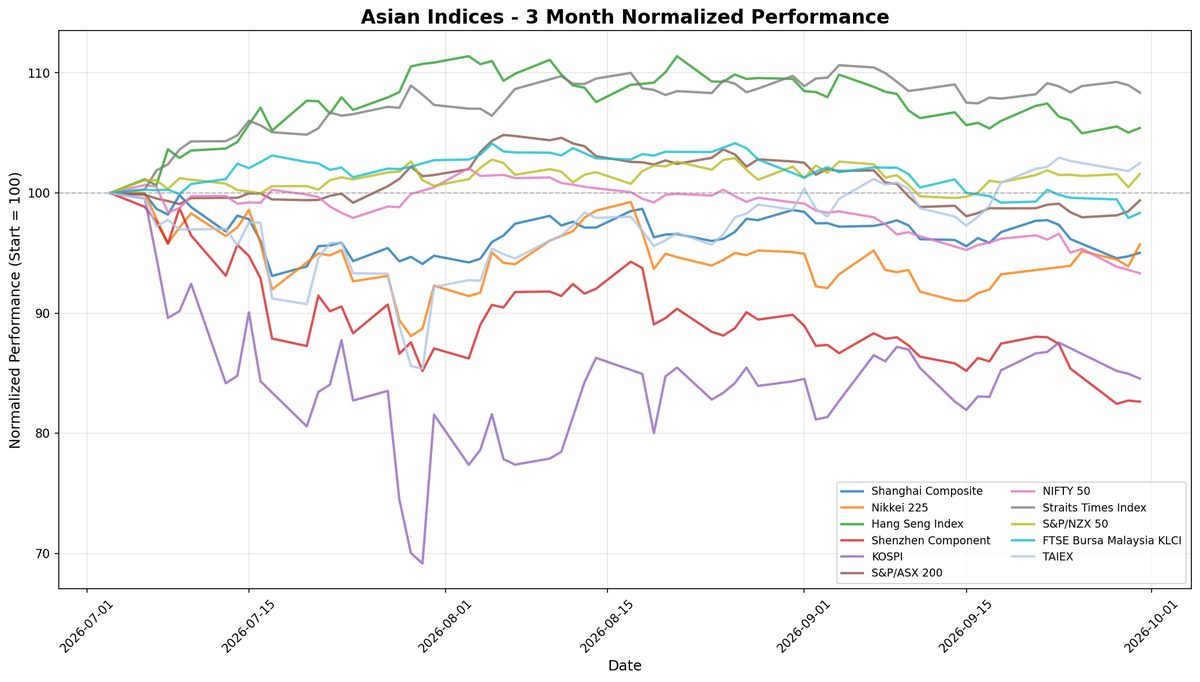
| Nikkei 225 | 65481.27 | -0.60% |
| Shanghai Composite | 3842.19 | +0.31% |
| Hang Seng | 24613.27 | +0.37% |
💱 FX & Commodities
| Name | Price | Daily (%) |
|---|---|---|
| EUR/USD | 1.14 | +0.12% |
| GBP/USD | 1.33 | +0.42% |
| USD/JPY | 157.11 | -0.09% |
| Gold (XAU/USD) | 4203.50 | +0.57% |
| Crude Oil (WTI) | 91.39 | +2.25% |
| Brent Oil | 98.83 | -3.67% |
| Bitcoin | 83714.64 | +0.11% |
🌍 Geopolitics and Market Drivers
Current market dynamics are heavily influenced by several key geopolitical and macroeconomic factors. Firstly, the ongoing conflict in Ukraine continues to create uncertainty, particularly with energy prices and supply chains, as Western nations maintain sanctions against Russia. This situation is exacerbated by rising tensions in the Middle East, particularly with Israel's military actions, which could disrupt oil supplies and further elevate prices. On the central bank front, the Federal Reserve's recent signals indicate a potential pause in interest rate hikes, as inflation shows signs of stabilizing. This dovish stance could support equity markets, but investors remain cautious about the implications of prolonged high rates on economic growth. Economic data releases have shown mixed signals, with recent employment figures indicating resilience in the labor market, while consumer spending appears to be slowing. This divergence raises concerns about future economic momentum. Politically, the U.S. debt ceiling discussions are heating up, with potential implications for fiscal policy and market stability. Overall, these factors create a complex landscape that investors must navigate carefully.
📅 Today's Economic Calendar
All times are in US Eastern Time (ET)
| Time (ET) | Event | Importance |
|---|---|---|
| 02:00 | Business Investment (QoQ) (Q2) | Medium |
| 02:00 | Current Account (Q2) | Medium |
| 02:00 | GDP (QoQ) (Q2) | High |
| 02:00 | GDP (YoY) (Q2) | High |
| 02:00 | German Retail Sales (MoM) (Aug) | Medium |
| 02:45 | French Consumer Spending (MoM) (Aug) | Medium |
| 02:45 | French CPI (MoM) (Sep) | Medium |
| 02:45 | French HICP (MoM) (Sep) | Medium |
| 03:00 | European Central Bank Non-monetary Policy Meeting | Medium |
| 03:55 | German Unemployment Change (Sep) | Medium |
| 03:55 | German Unemployment Rate (Sep) | Medium |
| 05:30 | German 10-Year Bund Auction | Medium |
| 07:30 | Gross Debt-to-GDP ratio (MoM) (Aug) | Medium |
| 08:00 | German CPI (MoM) (Sep) | High |
| 08:00 | German CPI (YoY) (Sep) | Medium |
| 08:15 | ADP Nonfarm Employment Change (Sep) | High |
| 08:30 | Core PCE Price Index (MoM) (Aug) | High |
| 08:30 | Core PCE Price Index (YoY) (Aug) | High |
| 08:30 | Core PCE Prices (Q2) | Medium |
| 08:30 | GDP (QoQ) (Q2) | High |
| 08:30 | GDP Price Index (QoQ) (Q2) | Medium |
| 08:30 | Goods Trade Balance (Aug) | Medium |
| 08:30 | PCE price index (MoM) (Aug) | Medium |
| 08:30 | PCE Price index (YoY) (Aug) | Medium |
| 08:30 | Personal Spending (MoM) (Aug) | Medium |
| 08:30 | Retail Inventories Ex Auto (Aug) | Medium |
| 09:45 | Chicago PMI (Sep) | High |
| 10:30 | Atlanta Fed GDPNow (Q3) | Medium |
| 10:30 | Crude Oil Inventories | High |
| 10:30 | Cushing Crude Oil Inventories | Medium |
| 11:45 | ECB's Schnabel Speaks | Medium |
| 12:00 | Retail Sales (YoY) (Aug) | Medium |
| 12:00 | Unemployment Rate (Aug) | Medium |
| 15:30 | U.S. President Trump Speaks | High |
| 18:00 | FOMC Member Kashkari Speaks | Medium |
| 19:50 | Tankan All Big Industry CAPEX (Q3) | Medium |
| 19:50 | Tankan Big Manufacturing Outlook Index (Q3) | Medium |
| 19:50 | Tankan Large Manufacturers Index (Q3) | Medium |
| 19:50 | Tankan Large Non-Manufacturers Index (Q3) | Medium |
A series of significant economic indicators are set to be released, including GDP figures for Q2, which will provide insights into economic growth and could influence market sentiment. Additionally, data on business investment, consumer spending, and inflation metrics from Germany and France will be closely monitored, as they may affect the European Central Bank's policy stance. The outcomes of these reports, particularly regarding inflation and employment, are likely to impact investor confidence and market volatility.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.