European Indices Rise: EuroStoxx 50 Up 1.25% — Positive Momentum Ahead of US Trading
MarketsFN Team
European markets approaching close (still trading) • US markets actively trading • Analysis based on last 8 hours
📊 Market Overview
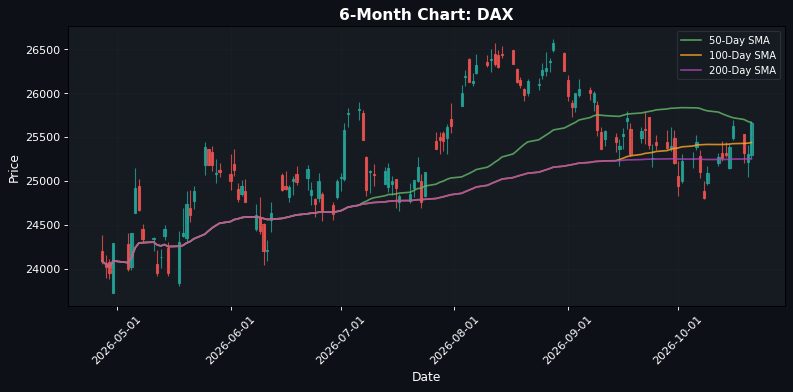
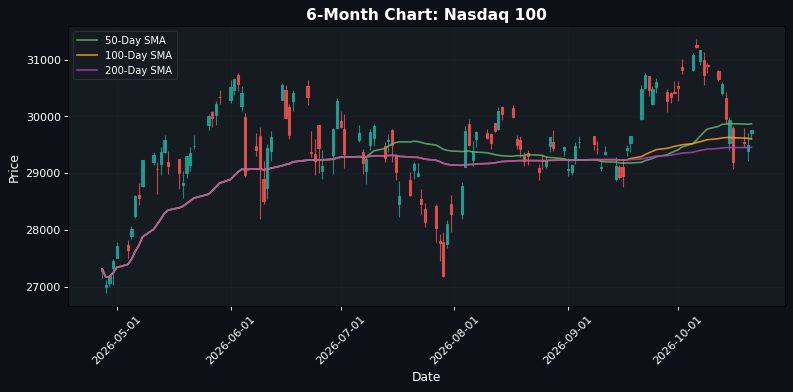
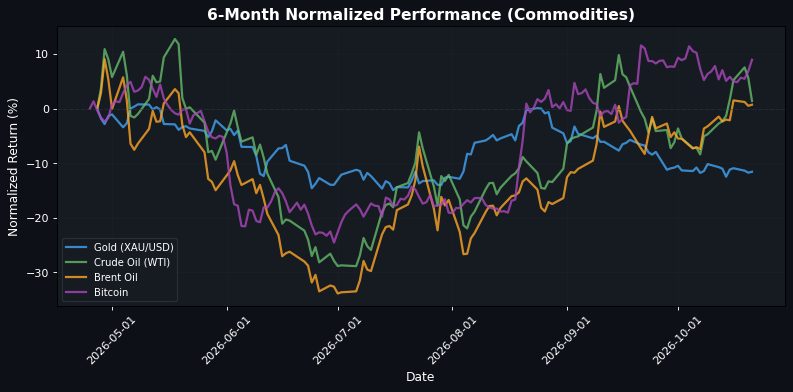
**European Indices Surge as US Markets Show Mixed Signals Amid Commodity Volatility** European markets are closing on a high note, with the EuroStoxx 50 up +1.25% at 6198.15, reflecting strong investor sentiment across the continent. The DAX gained +1.26% to 25624.46, while the CAC 40 and FTSE MIB rose +0.98% and +1.06%, respectively. This upward momentum is largely driven by positive earnings reports and a rebound in consumer confidence, signaling resilience in the face of economic headwinds. In contrast, US markets are experiencing a more subdued session. The S&P 500 is up +0.31% at 7736.60, while the Dow Jones barely moved, gaining just +0.02% to 52504.67. The Nasdaq 100, however, is showing strength with a +0.88% increase to 29751.19, suggesting a rotation into tech stocks as investors seek growth amid uncertainty. The FX landscape is mixed, with the EUR/USD down -0.12% at 1.1227, indicating a slight dollar strength that may be impacting European exports. Meanwhile, crude oil prices are under pressure, with WTI down -3.99% at 97.7300, reflecting concerns over demand amid rising global supply. This decline in oil prices could have broader implications for inflation and consumer spending. Looking ahead, the market is poised for potential volatility as investors await the upcoming US inflation data release. This key indicator will provide insights into the Federal Reserve's monetary policy trajectory and could either validate the current market optimism or trigger a reassessment of risk. The interplay between inflation expectations and commodity prices will be crucial in shaping market sentiment in the coming days.
🇪🇺 European Markets (Approaching Close)
| Name | Price | Daily (%) |
|---|---|---|
| EuroStoxx 50 | 6198.15 | +1.25% |
| DAX | 25624.46 | +1.26% |
| FTSE 100 | 10751.14 | +0.17% |
| CAC 40 | 7915.10 | +0.98% |
| FTSE MIB | 49593.09 | +1.06% |
| IBEX 35 | 19286.50 | +1.02% |
🇺🇸 US Markets (Currently Active)
| Name | Price | Daily (%) |
|---|---|---|
| S&P 500 | 7736.60 | +0.31% |
| Dow Jones | 52504.67 | +0.02% |
| Nasdaq 100 | 29751.19 | +0.88% |
🌏 Asian Markets
| Name | Price | Daily (%) |
|---|---|---|
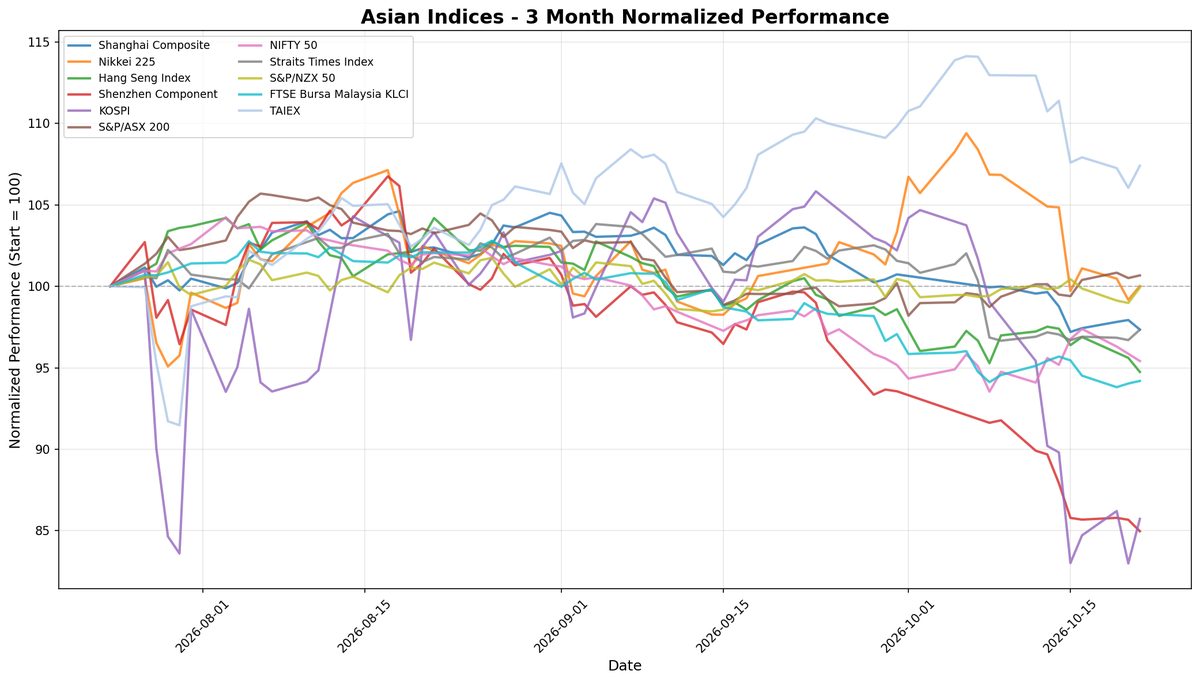
| Nikkei 225 | 64075.42 | -1.30% |
| Shanghai Composite | 3713.03 | -0.60% |
| Hang Seng | 23651.87 | -0.90% |
💱 FX & Commodities
| Name | Price | Daily (%) |
|---|---|---|
| EUR/USD | 1.12 | -0.12% |
| GBP/USD | 1.34 | +0.05% |
| USD/JPY | 158.12 | -0.01% |
| Gold (XAU/USD) | 4150.80 | +0.20% |
| Crude Oil (WTI) | 97.73 | -3.99% |
| Brent Oil | 109.01 | +0.20% |
| Bitcoin | 84564.55 | +1.96% |
🌍 Geopolitics and Market Drivers
Current market dynamics are significantly influenced by several geopolitical and macroeconomic factors. The ongoing conflict in Ukraine continues to escalate, with recent reports of increased military support from Western nations, which could prolong instability in Europe and impact energy prices. In Asia, tensions surrounding Taiwan remain high, particularly with China's military maneuvers, raising concerns about supply chain disruptions. On the central bank front, the Federal Reserve's recent signals indicate a potential pause in interest rate hikes, as inflation shows signs of moderating. This has led to a more optimistic outlook for equities, although market participants remain cautious about the implications of prolonged high rates on economic growth. Economic data releases have shown mixed signals; while the U.S. labor market remains robust, recent consumer spending figures indicate a slowdown, suggesting potential headwinds for growth. Additionally, political developments in the U.S. regarding the debt ceiling negotiations could create volatility, as any failure to reach an agreement may lead to a government shutdown, further impacting market sentiment. Overall, these factors create a complex landscape for investors, necessitating close monitoring of geopolitical tensions and economic indicators.
📅 Today's Economic Calendar
All times are in US Eastern Time (ET)
| Time (ET) | Event | Importance |
|---|---|---|
| 00:15 | ECB's Lane Speaks | Medium |
| 02:00 | CPI (YoY) (Sep) | High |
| 02:00 | CPI (MoM) (Sep) | Medium |
| 02:00 | PPI Input (MoM) (Sep) | Medium |
| 02:30 | Interest Rate Decision | Medium |
| 03:15 | German Buba President Nagel Speaks | Medium |
| 07:30 | RBI MPC Meeting Minutes | Medium |
| 09:00 | BoE Gov Bailey Speaks | Medium |
| 09:15 | German Buba Mauderer Speaks | Medium |
| 10:30 | Crude Oil Inventories | High |
| 10:30 | Cushing Crude Oil Inventories | Medium |
| 12:00 | ECB President Lagarde Speaks | Medium |
| 13:00 | 20-Year Bond Auction | Medium |
| 17:45 | CPI (QoQ) (Q3) | Medium |
| 17:45 | CPI (YoY) (Q3) | Medium |
Today's economic events are likely to create significant market volatility, particularly with the release of the Consumer Price Index (CPI) data and the European Central Bank's (ECB) interest rate decision, both of which are critical for assessing inflation and monetary policy direction. Additionally, speeches from key figures such as ECB President Lagarde and BoE Governor Bailey may further influence market sentiment and expectations regarding interest rates. The crude oil inventories report could also impact energy markets, especially given its potential implications for supply and pricing.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.