Global Commodities — US Session: RBOB Gasoline Slides 5.71%
MarketsFN Commodities Desk
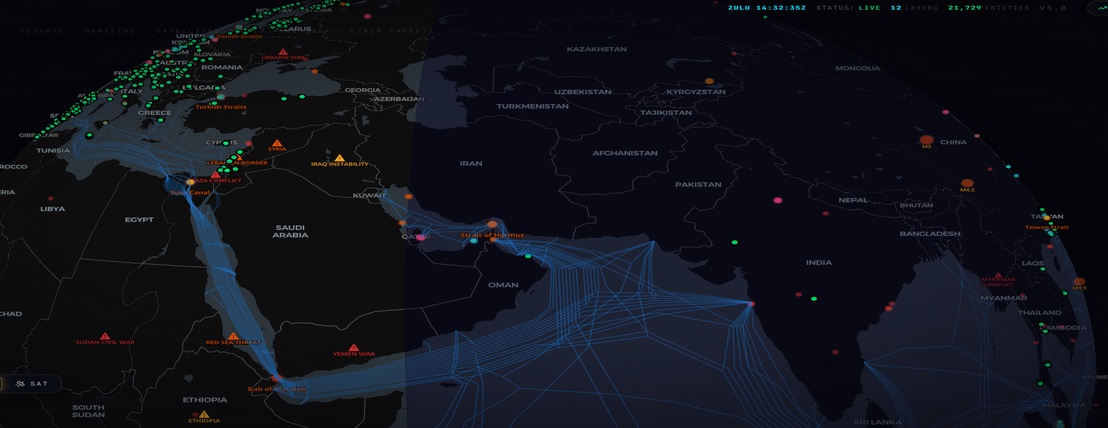
Commodity markets enter the US session on Monday 28 September 2026 as COMEX opens and New York liquidity adds depth to price discovery. Top movers at this hour: Sugar #11 (+6.11%), RBOB Gasoline (-5.71%), Brent Crude Oil (-4.77%). Energies are declining (avg -2.69%) — the NYMEX WTI floor is now active and any intraday EIA inventory surprise, SPR news, or OPEC delegate commentary will move the market with outsized volume. Precious metals are retreating (avg -3.55%) into the second London PM fix window, with Fed speakers and US data releases the primary dollar-move catalyst.
Agricultural futures (avg +1.23%) open the CBOT afternoon pit session, where grain and soft commodity traders absorb any USDA export sales data released earlier this morning. Large managed-money positions in grains mean macro USD moves can trigger outsized technical reactions. Equity risk tone from the S&P 500 open also feeds back into risk-sensitive commodities like copper and crude oil.
All commodities below carry live pivot levels from yesterday's full OHLC, 65-bar candlestick charts with SMA20, SMA50 and Bollinger Bands, and US session forward analysis for Mon 28 Sep 2026.
Today's Economic Calendar
| Time (UTC) | Event | CCY | Previous | Forecast | Actual |
|---|---|---|---|---|---|
| 09:30 | ● ECB's Elderson Speaks | EUR | — | — | — |
| 10:00 | ● MPC Member Ramsden Speaks | GBP | — | — | — |
| 12:15 | ● FOMC Member Bowman Speaks | USD | — | — | — |
| 13:30 | ● ECB President Lagarde Speaks | EUR | — | — | — |
Precious Metals
Gold
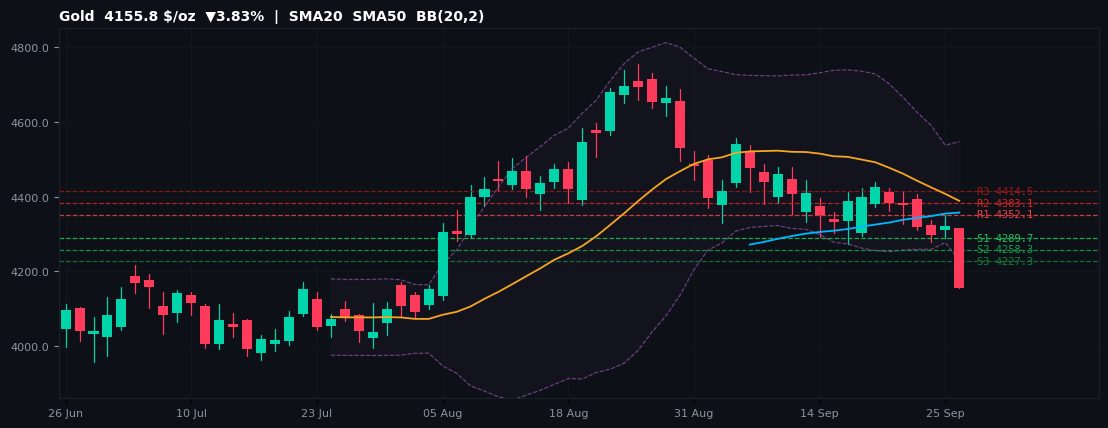
4155.8 $/oz ▼3.83% Session H 4315.6 / L 4155.1 52W 3764.0–5586.2
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 4414.5 | 4383.1 | 4352.1 | 4320.7 | 4289.7 | 4258.3 | 4227.3 |
Gold trades at 4155.8 $/oz (-3.83% vs. prior close) as the US session gets underway, at the 22th percentile of its 3764.0–5586.2 $/oz 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 4320.7 $/oz. The 52-week range of 3764.0–5586.2 places this commodity at the 22th percentile — price remains in the lower half of its annual range, reflecting structural headwinds.
Key drivers for COMEX gold: Federal Reserve policy expectations, real yields, USD strength, and central bank reserve buying. Resistance: R1 4352.1, R2 4383.1, R3 4414.5. Support: S1 4289.7, S2 4258.3, S3 4227.3 $/oz. The R1–S1 corridor (4352.1–4289.7) marks the most probable us intraday band.
GoldPrecious MetalsBearishBelow S1
Silver
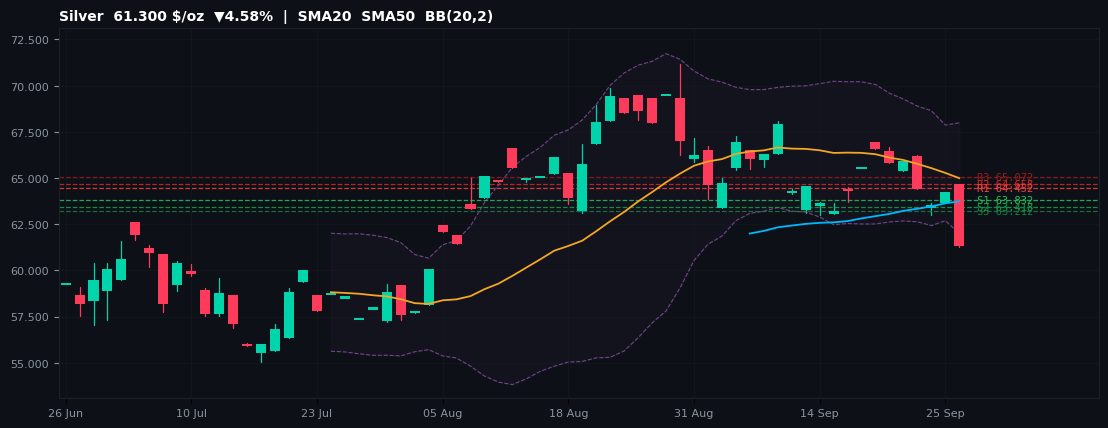
61.300 $/oz ▼4.58% Session H 64.660 / L 61.250 52W 44.870–121.300
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 65.072 | 64.658 | 64.452 | 64.038 | 63.832 | 63.418 | 63.212 |
Silver trades at 61.300 $/oz (-4.58% vs. prior close) as the US session gets underway, at the 21th percentile of its 44.870–121.300 $/oz 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 64.038 $/oz. The 52-week range of 44.870–121.300 places this commodity at the 21th percentile — price remains in the lower half of its annual range, reflecting structural headwinds.
Key drivers for COMEX silver: industrial demand from solar/EV manufacturing, monetary premium vs gold (Gold:Silver Ratio), and mine supply. Resistance: R1 64.452, R2 64.658, R3 65.072. Support: S1 63.832, S2 63.418, S3 63.212 $/oz. The R1–S1 corridor (64.452–63.832) marks the most probable us intraday band.
SilverPrecious MetalsBearishBelow S1
Platinum
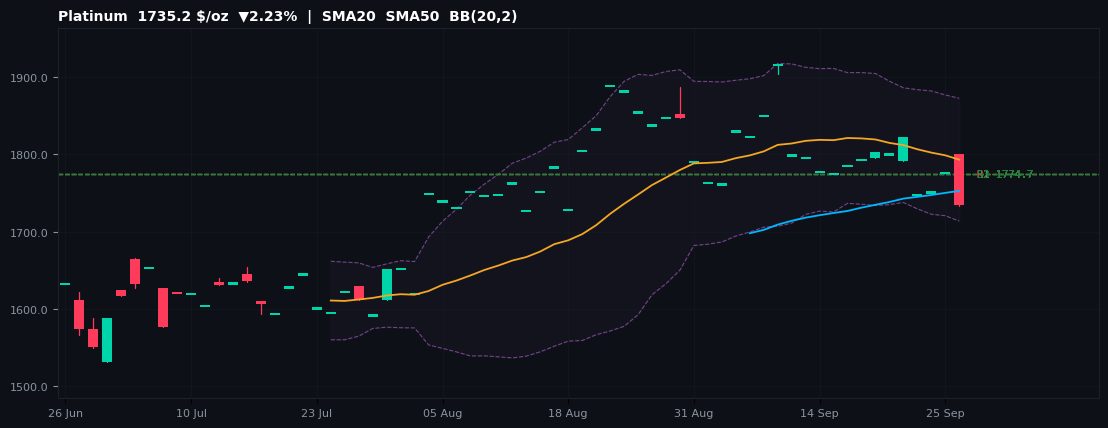
1735.2 $/oz ▼2.23% Session H 1800.9 / L 1733.4 52W 1477.1–2852.4
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 1774.7 | 1774.7 | 1774.7 | 1774.7 | 1774.7 | 1774.7 | 1774.7 |
Platinum trades at 1735.2 $/oz (-2.23% vs. prior close) as the US session gets underway, at the 19th percentile of its 1477.1–2852.4 $/oz 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 1774.7 $/oz. The 52-week range of 1477.1–2852.4 places this commodity at the 19th percentile — price remains in the lower half of its annual range, reflecting structural headwinds.
Key drivers for NYMEX platinum: autocatalytic demand from hydrogen/fuel cells, palladium substitution economics, and South African mine supply. Resistance: R1 1774.7, R2 1774.7, R3 1774.7. Support: S1 1774.7, S2 1774.7, S3 1774.7 $/oz. The R1–S1 corridor (1774.7–1774.7) marks the most probable us intraday band.
PlatinumPrecious MetalsBearishBelow S1
Palladium
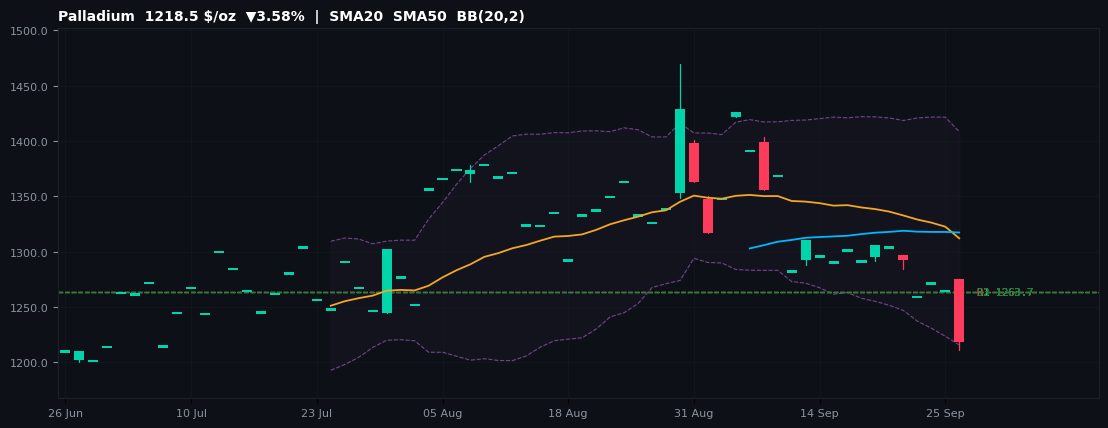
1218.5 $/oz ▼3.58% Session H 1275.0 / L 1211.5 52W 1161.3–2169.9
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 1263.7 | 1263.7 | 1263.7 | 1263.7 | 1263.7 | 1263.7 | 1263.7 |
Palladium trades at 1218.5 $/oz (-3.58% vs. prior close) as the US session gets underway, at the 6th percentile of its 1161.3–2169.9 $/oz 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 1263.7 $/oz. The 52-week range of 1161.3–2169.9 places this commodity at the 6th percentile — price remains in the lower half of its annual range, reflecting structural headwinds.
Key drivers for NYMEX palladium: automotive gasoline catalytic demand, EV transition headwinds, and Russian supply constraints. Resistance: R1 1263.7, R2 1263.7, R3 1263.7. Support: S1 1263.7, S2 1263.7, S3 1263.7 $/oz. The R1–S1 corridor (1263.7–1263.7) marks the most probable us intraday band.
PalladiumPrecious MetalsBearishBelow S1
Energies
WTI Crude Oil
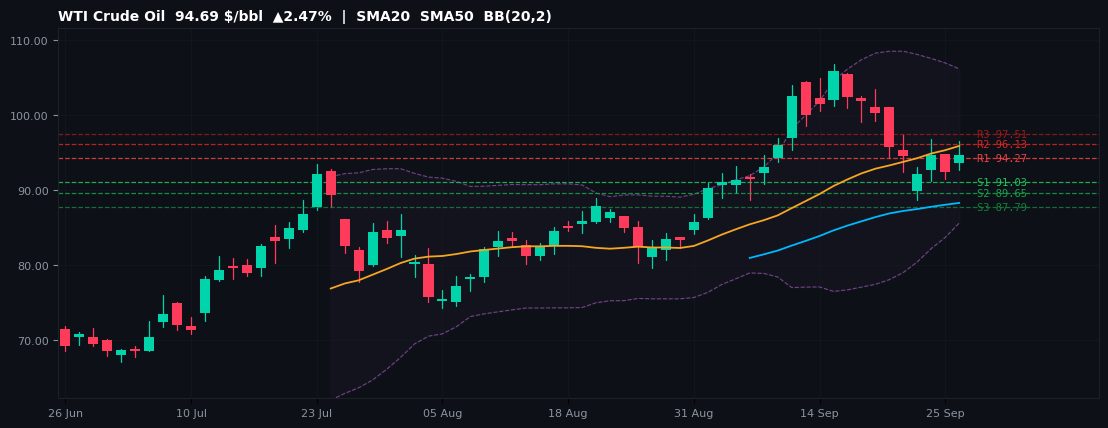
94.69 $/bbl ▲2.47% Session H 96.54 / L 92.68 52W 54.98–119.48
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 97.51 | 96.13 | 94.27 | 92.89 | 91.03 | 89.65 | 87.79 |
WTI Crude Oil trades at 94.69 $/bbl (+2.47% vs. prior close) as the US session gets underway, at the 62th percentile of its 54.98–119.48 $/bbl 52-week range. Intraday bias tilts bullish while price holds above the daily pivot at 92.89 $/bbl. The 52-week range of 54.98–119.48 places this commodity at the 62th percentile — momentum is broadly constructive within the annual range.
Key drivers for NYMEX WTI crude: OPEC+ production quotas, US EIA weekly inventory builds/draws, and refinery run rates. Resistance: R1 94.27, R2 96.13, R3 97.51. Support: S1 91.03, S2 89.65, S3 87.79 $/bbl. The R1–S1 corridor (94.27–91.03) marks the most probable us intraday band.
WTI Crude OilEnergiesBullishAbove R1
Brent Crude Oil
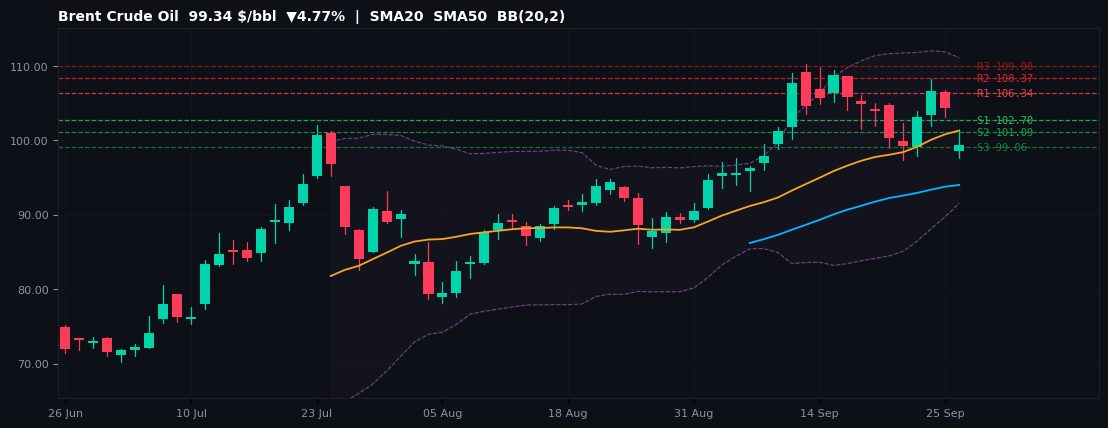
99.34 $/bbl ▼4.77% Session H 101.24 / L 97.63 52W 58.72–126.10
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 109.98 | 108.37 | 106.34 | 104.73 | 102.70 | 101.09 | 99.06 |
Brent Crude Oil trades at 99.34 $/bbl (-4.77% vs. prior close) as the US session gets underway, at the 60th percentile of its 58.72–126.10 $/bbl 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 104.73 $/bbl. The 52-week range of 58.72–126.10 places this commodity at the 60th percentile — momentum is broadly constructive within the annual range.
Key drivers for ICE Brent crude: OPEC+ quota compliance, North Sea loadings, and European and Asian refinery margins. Resistance: R1 106.34, R2 108.37, R3 109.98. Support: S1 102.70, S2 101.09, S3 99.06 $/bbl. The R1–S1 corridor (106.34–102.70) marks the most probable us intraday band.
Brent Crude OilEnergiesBearishBelow S1
Natural Gas
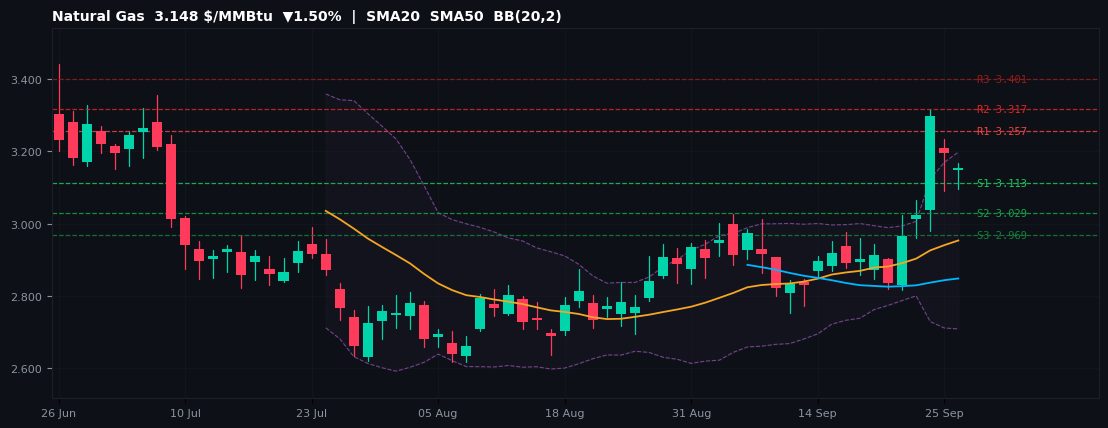
3.148 $/MMBtu ▼1.50% Session H 3.167 / L 3.097 52W 2.483–7.827
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 3.401 | 3.317 | 3.257 | 3.173 | 3.113 | 3.029 | 2.969 |
Natural Gas trades at 3.148 $/MMBtu (-1.50% vs. prior close) as the US session gets underway, at the 12th percentile of its 2.483–7.827 $/MMBtu 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 3.173 $/MMBtu. The 52-week range of 2.483–7.827 places this commodity at the 12th percentile — price remains in the lower half of its annual range, reflecting structural headwinds.
Key drivers for Henry Hub natural gas: US storage draws vs seasonal norms (EIA weekly), weather-driven heating/cooling demand, and LNG export flow. Resistance: R1 3.257, R2 3.317, R3 3.401. Support: S1 3.113, S2 3.029, S3 2.969 $/MMBtu. The R1–S1 corridor (3.257–3.113) marks the most probable us intraday band.
Natural GasEnergiesBearish
RBOB Gasoline
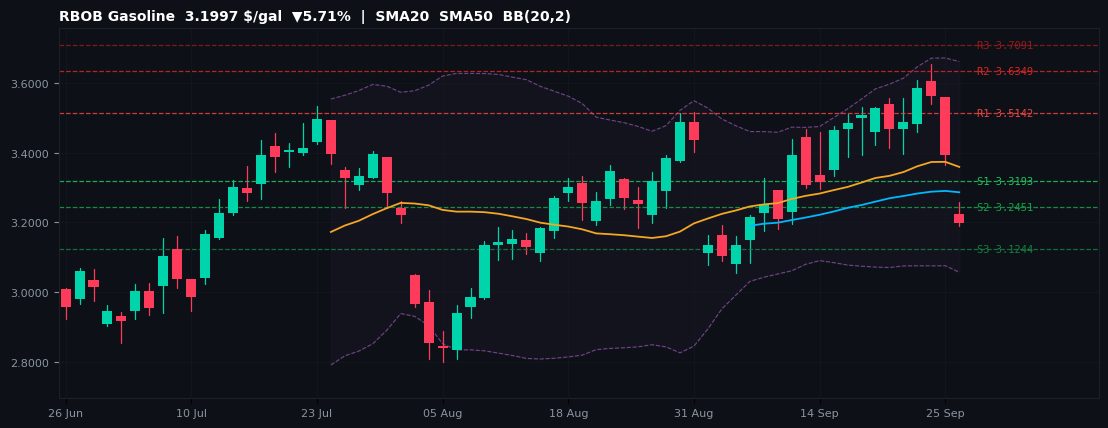
3.1997 $/gal ▼5.71% Session H 3.2581 / L 3.1897 52W 1.6656–3.8232
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 3.7091 | 3.6349 | 3.5142 | 3.4400 | 3.3193 | 3.2451 | 3.1244 |
RBOB Gasoline trades at 3.1997 $/gal (-5.71% vs. prior close) as the US session gets underway, at the 71th percentile of its 1.6656–3.8232 $/gal 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 3.4400 $/gal. The 52-week range of 1.6656–3.8232 places this commodity at the 71th percentile — momentum is broadly constructive within the annual range.
Key drivers for RBOB gasoline: US driving demand, refinery utilisation rates, and crack spread dynamics. Resistance: R1 3.5142, R2 3.6349, R3 3.7091. Support: S1 3.3193, S2 3.2451, S3 3.1244 $/gal. The R1–S1 corridor (3.5142–3.3193) marks the most probable us intraday band.
RBOB GasolineEnergiesBearishBelow S1
Heating Oil
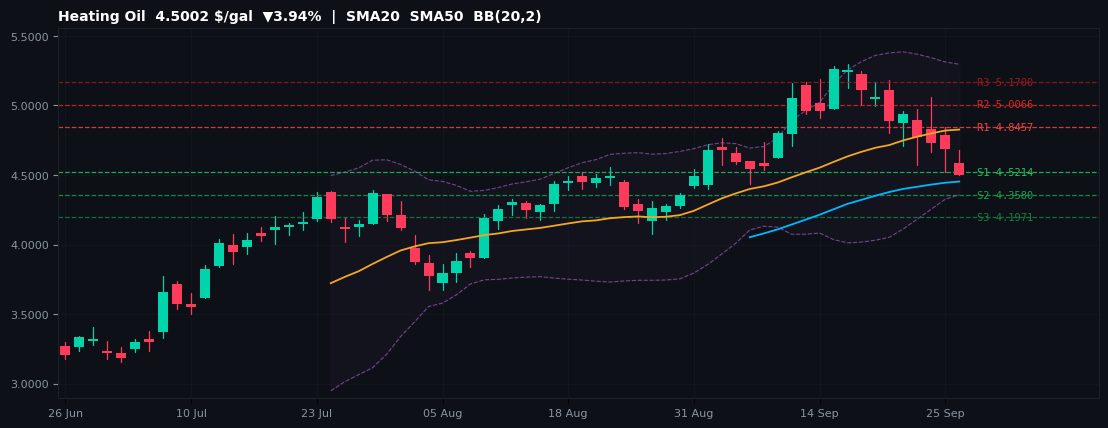
4.5002 $/gal ▼3.94% Session H 4.6805 / L 4.4972 52W 2.0469–5.2968
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 5.1700 | 5.0066 | 4.8457 | 4.6823 | 4.5214 | 4.3580 | 4.1971 |
Heating Oil trades at 4.5002 $/gal (-3.94% vs. prior close) as the US session gets underway, at the 75th percentile of its 2.0469–5.2968 $/gal 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 4.6823 $/gal. The 52-week range of 2.0469–5.2968 places this commodity at the 75th percentile — momentum is broadly constructive within the annual range.
Key drivers for ULSD heating oil: Northern Hemisphere heating demand, distillate inventory levels, and refinery run margins. Resistance: R1 4.8457, R2 5.0066, R3 5.1700. Support: S1 4.5214, S2 4.3580, S3 4.1971 $/gal. The R1–S1 corridor (4.8457–4.5214) marks the most probable us intraday band.
Heating OilEnergiesBearishBelow S1
△ OPEC+ Monitoring
OPEC+ Production Quota Update
Track the latest OPEC+ production cuts, quota allocations and compliance data. Monthly output figures, ministerial meeting outcomes and spare capacity estimates — the key drivers behind crude oil prices.
Latest OPEC coverage →Agricultural Commodities
Today's featured selection: Sugar #11, Wheat, Coffee, Soybeans — comprising the session's top riser, top faller, and two additional picks.
Sugar #11
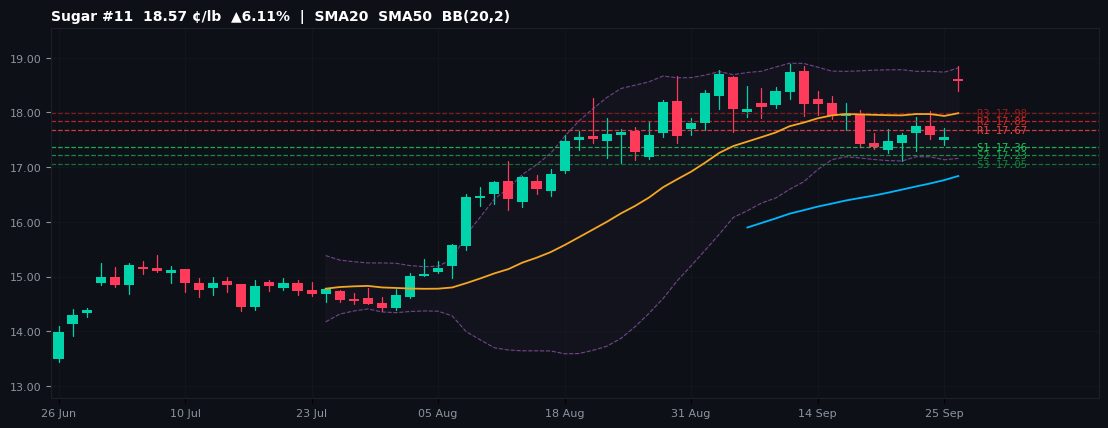
18.57 ¢/lb ▲6.11% Session H 18.84 / L 18.39 52W 13.22–18.88
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 17.98 | 17.85 | 17.67 | 17.54 | 17.36 | 17.23 | 17.05 |
Sugar #11 trades at 18.57 ¢/lb (+6.11% vs. prior close) as the US session gets underway, at the 95th percentile of its 13.22–18.88 ¢/lb 52-week range. Intraday bias tilts bullish while price holds above the daily pivot at 17.54 ¢/lb. The 52-week range of 13.22–18.88 places this commodity at the 95th percentile — momentum is broadly constructive within the annual range.
Key drivers for ICE Sugar #11: Brazilian Center-South harvest pace, Indian/Thai export policies, and ethanol economics linkage. Resistance: R1 17.67, R2 17.85, R3 17.98. Support: S1 17.36, S2 17.23, S3 17.05 ¢/lb. The R1–S1 corridor (17.67–17.36) marks the most probable us intraday band.
Sugar #11AgriculturalBullishAbove R1
Wheat
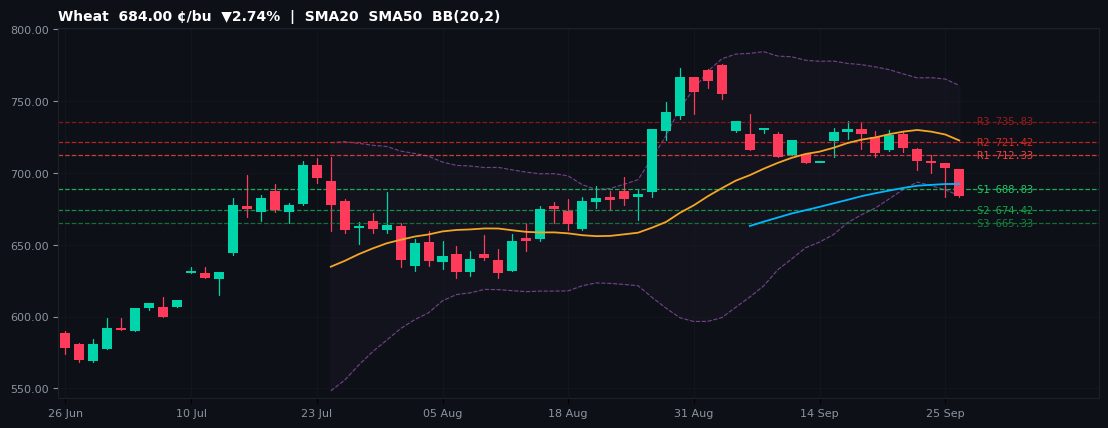
684.00 ¢/bu ▼2.74% Session H 703.00 / L 683.50 52W 492.25–775.75
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 735.83 | 721.42 | 712.33 | 697.92 | 688.83 | 674.42 | 665.33 |
Wheat trades at 684.00 ¢/bu (-2.74% vs. prior close) as the US session gets underway, at the 68th percentile of its 492.25–775.75 ¢/bu 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 697.92 ¢/bu. The 52-week range of 492.25–775.75 places this commodity at the 68th percentile — momentum is broadly constructive within the annual range.
Key drivers for CBOT wheat: Black Sea/Ukraine export flows, Australian and Canadian harvest prospects, and global food security premia. Resistance: R1 712.33, R2 721.42, R3 735.83. Support: S1 688.83, S2 674.42, S3 665.33 ¢/bu. The R1–S1 corridor (712.33–688.83) marks the most probable us intraday band.
WheatAgriculturalBearishBelow S1
Coffee
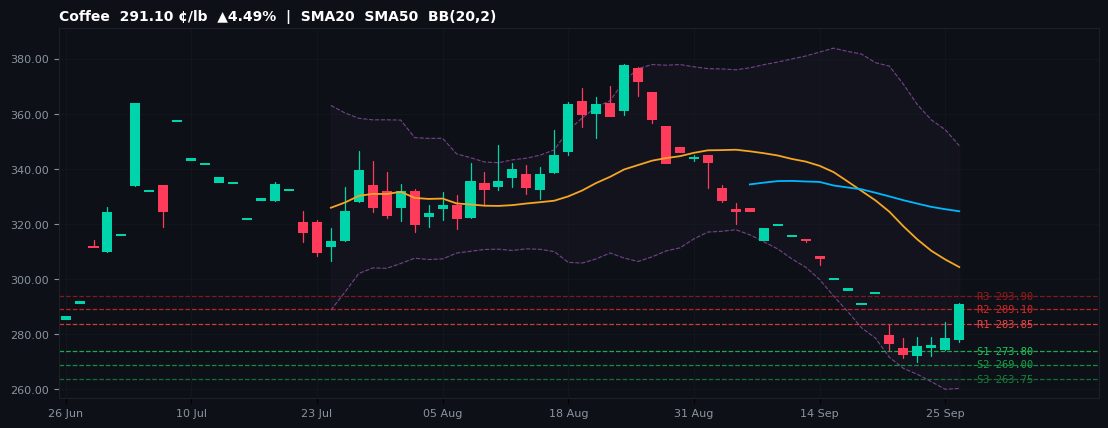
291.10 ¢/lb ▲4.49% Session H 291.40 / L 277.05 52W 242.70–437.95
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 293.90 | 289.10 | 283.85 | 279.05 | 273.80 | 269.00 | 263.75 |
Coffee trades at 291.10 ¢/lb (+4.49% vs. prior close) as the US session gets underway, at the 25th percentile of its 242.70–437.95 ¢/lb 52-week range. Intraday bias tilts bullish while price holds above the daily pivot at 279.05 ¢/lb. The 52-week range of 242.70–437.95 places this commodity at the 25th percentile — price remains in the lower half of its annual range, reflecting structural headwinds.
Key drivers for ICE Arabica coffee: Brazilian and Vietnamese crop conditions, seasonal frost risk, and managed-money positioning. Resistance: R1 283.85, R2 289.10, R3 293.90. Support: S1 273.80, S2 269.00, S3 263.75 ¢/lb. The R1–S1 corridor (283.85–273.80) marks the most probable us intraday band.
CoffeeAgriculturalBullishAbove R1
Soybeans
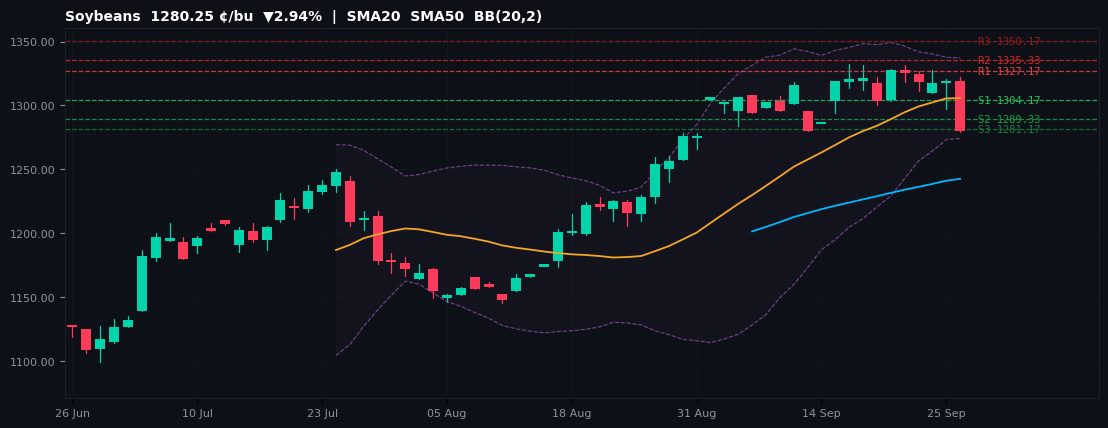
1280.25 ¢/bu ▼2.94% Session H 1322.50 / L 1279.25 52W 993.75–1332.25
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 1350.17 | 1335.33 | 1327.17 | 1312.33 | 1304.17 | 1289.33 | 1281.17 |
Soybeans trades at 1280.25 ¢/bu (-2.94% vs. prior close) as the US session gets underway, at the 85th percentile of its 993.75–1332.25 ¢/bu 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 1312.33 ¢/bu. The 52-week range of 993.75–1332.25 places this commodity at the 85th percentile — momentum is broadly constructive within the annual range.
Key drivers for CBOT soybeans: Chinese crusher demand, South American production competition, and USDA weekly export inspections. Resistance: R1 1327.17, R2 1335.33, R3 1350.17. Support: S1 1304.17, S2 1289.33, S3 1281.17 ¢/bu. The R1–S1 corridor (1327.17–1304.17) marks the most probable us intraday band.
SoybeansAgriculturalBearishBelow S1
🌿 Agricultural Markets
Understanding WASDE Reports and Grain Markets
The USDA WASDE (World Agricultural Supply and Demand Estimates) is published monthly and is the single most important data release for grain futures. Learn how to read supply/demand tables, ending stocks, and what weather models mean for crop prices.
Explore commodities →For informational purposes only — not investment advice. Pivot levels computed from the previous session's OHLC via the classic floor-pivot formula. Price data sourced from Yahoo Finance (front-month futures) as of the US session, Monday 28 September 2026. Futures prices are subject to roll effects near contract expiry. Past performance is not indicative of future results.