Global Commodities — European Session: Gold +0.09%, WTI -0.74%, Sugar #11 +4.32%
MarketsFN Commodities Desk
Global commodity markets open the European session on Monday 05 October 2026 with the top movers across asset classes: Sugar #11 (+4.32%), Cocoa (+3.35%), Platinum (+1.96%). Energies are mixed (avg -0.15%) as London trading begins and traders monitor OPEC+ compliance data and the mid-week EIA inventory outlook. Precious metals are firm (avg +1.13%) as COMEX overnight positioning crosses into the London fix window.
The London Metals Exchange sets the global benchmark for industrial pricing, while the COMEX open adds North American liquidity from 14:20 UTC. Agricultural futures (avg +2.30%) track overnight CBOT closes and any pre-market weather model revisions from the US Plains and South American growing regions. Key European macro risk today: ECB speaker schedule and any German data releases that could move EUR/USD and indirectly pressure USD-denominated commodity prices.
All commodities below include pivot levels (R1 R2 R3 / PP / S1 S2 S3) from the prior session's OHLC, 65-bar candlestick charts with SMA20, SMA50 and Bollinger Bands (20,2), and session-specific analysis for Mon 05 Oct 2026.
Today's Economic Calendar
| Time (UTC) | Event | CCY | Previous | Forecast | Actual |
|---|---|---|---|---|---|
| 00:30 | ● S&P Global Services PMI (Sep) | JPY | 52.5 | 51.6 | 51.3 |
| 06:00 | ● S&P Global Services PMI (Sep) | RUB | 51.3 | — | 51.3 |
| 07:00 | ● CPI (MoM) (Sep) | TRY | 1.84% | 2.30% | 1.84% |
| 07:00 | ● CPI (YoY) (Sep) | TRY | 31.51% | 30.30% | 29.73% |
| 07:15 | ● HCOB Spain Services PMI (Sep) | EUR | 57.8 | 57.1 | 58.3 |
| 07:45 | ● HCOB Italy Services PMI (Sep) | EUR | 55.2 | 54.6 | 51.7 |
| 07:45 | ● German Buba President Nagel Speaks | EUR | — | — | — |
| 07:50 | ● HCOB France Services PMI (Sep) | EUR | 48.0 | 51.4 | 51.2 |
| 07:55 | ● HCOB Germany Services PMI (Sep) | EUR | 49.7 | 52.9 | 52.9 |
| 08:00 | ● ECB's Lane Speaks | EUR | — | — | — |
| 08:00 | ● HCOB Eurozone Composite PMI (Sep) | EUR | 52.0 | 53.1 | 53.1 |
| 08:00 | ● HCOB Eurozone Services PMI (Sep) | EUR | 51.6 | 53.0 | 53.0 |
| 08:30 | ● S&P Global Composite PMI (Sep) | GBP | 52.5 | 51.7 | 52.0 |
| 08:30 | ● S&P Global Services PMI (Sep) | GBP | 52.5 | 51.7 | 52.1 |
| 09:00 | ● ECB's Schnabel Speaks | EUR | — | — | — |
| 13:45 | ● S&P Global Composite PMI (Sep) | USD | 58.4 | 58.4 | 58.4 |
| 13:45 | ● S&P Global Services PMI (Sep) | USD | 58.7 | 58.7 | 58.8 |
| 14:00 | ● ISM Non-Manufacturing Employment (Sep) | USD | 47.8 | 48.8 | 50.1 |
| 14:00 | ● ISM Non-Manufacturing PMI (Sep) | USD | 55.4 | 55.1 | 54.9 |
| 14:00 | ● ISM Non-Manufacturing Prices (Sep) | USD | 72.6 | 73.3 | 74.0 |
| 21:00 | ● NZIER Business Confidence (Q3) | NZD | 8% | — | — |
Precious Metals
Gold
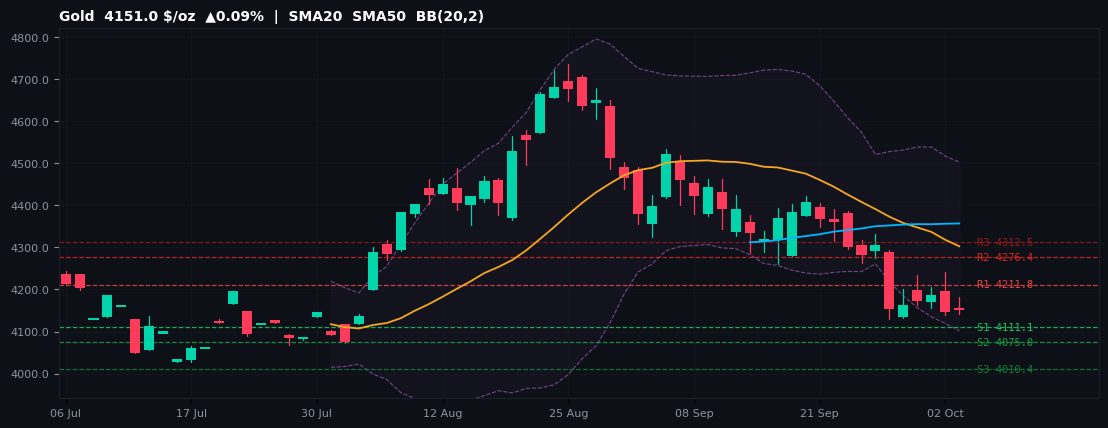
4151.0 $/oz ▲0.09% Session H 4182.8 / L 4141.0 52W 4026.4–5489.4
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 4312.5 | 4276.4 | 4211.8 | 4175.7 | 4111.1 | 4075.0 | 4010.4 |
Gold trades at 4151.0 $/oz (+0.09% vs. prior close) as the European session gets underway, at the 9th percentile of its 4026.4–5489.4 $/oz 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 4175.7 $/oz. The 52-week range of 4026.4–5489.4 places this commodity at the 9th percentile — price remains in the lower half of its annual range, reflecting structural headwinds.
Key drivers for COMEX gold: Federal Reserve policy expectations, real yields, USD strength, and central bank reserve buying. Resistance: R1 4211.8, R2 4276.4, R3 4312.5. Support: S1 4111.1, S2 4075.0, S3 4010.4 $/oz. The R1–S1 corridor (4211.8–4111.1) marks the most probable european intraday band.
GoldPrecious MetalsRangebound
Silver
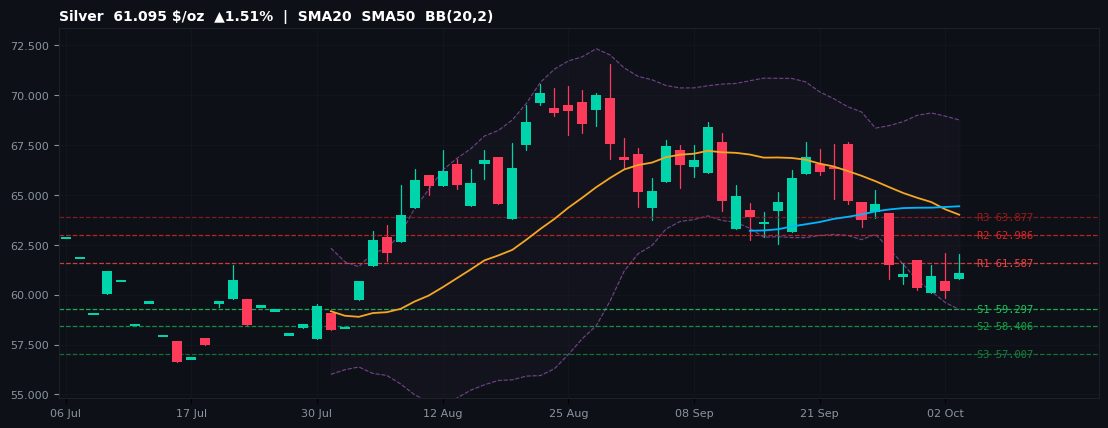
61.095 $/oz ▲1.51% Session H 62.020 / L 60.800 52W 48.666–118.677
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 63.877 | 62.986 | 61.587 | 60.696 | 59.297 | 58.406 | 57.007 |
Silver trades at 61.095 $/oz (+1.51% vs. prior close) as the European session gets underway, at the 18th percentile of its 48.666–118.677 $/oz 52-week range. Intraday bias tilts bullish while price holds above the daily pivot at 60.696 $/oz. The 52-week range of 48.666–118.677 places this commodity at the 18th percentile — price remains in the lower half of its annual range, reflecting structural headwinds.
Key drivers for COMEX silver: industrial demand from solar/EV manufacturing, monetary premium vs gold (Gold:Silver Ratio), and mine supply. Resistance: R1 61.587, R2 62.986, R3 63.877. Support: S1 59.297, S2 58.406, S3 57.007 $/oz. The R1–S1 corridor (61.587–59.297) marks the most probable european intraday band.
SilverPrecious MetalsBullish
Platinum
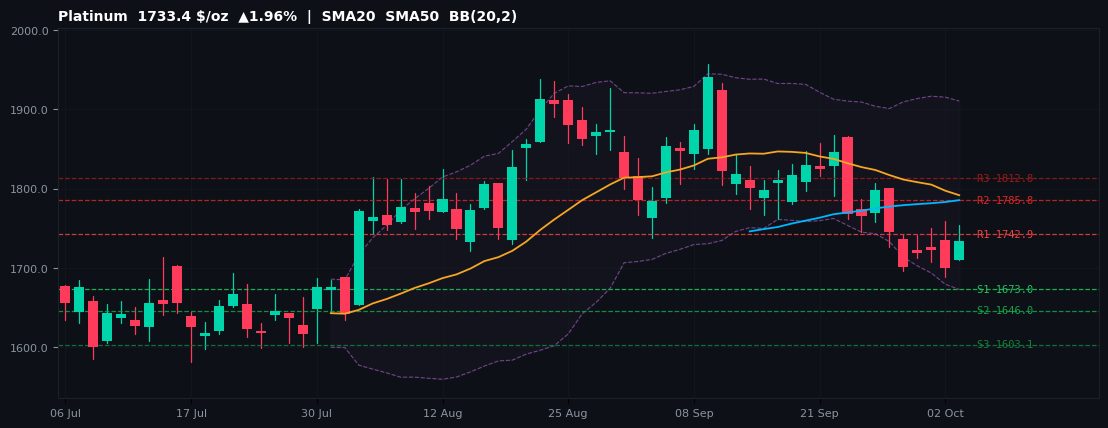
1733.4 $/oz ▲1.96% Session H 1753.7 / L 1709.4 52W 1540.7–2940.0
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 1812.8 | 1785.8 | 1742.9 | 1715.9 | 1673.0 | 1646.0 | 1603.1 |
Platinum trades at 1733.4 $/oz (+1.96% vs. prior close) as the European session gets underway, at the 14th percentile of its 1540.7–2940.0 $/oz 52-week range. Intraday bias tilts bullish while price holds above the daily pivot at 1715.9 $/oz. The 52-week range of 1540.7–2940.0 places this commodity at the 14th percentile — price remains in the lower half of its annual range, reflecting structural headwinds.
Key drivers for NYMEX platinum: autocatalytic demand from hydrogen/fuel cells, palladium substitution economics, and South African mine supply. Resistance: R1 1742.9, R2 1785.8, R3 1812.8. Support: S1 1673.0, S2 1646.0, S3 1603.1 $/oz. The R1–S1 corridor (1742.9–1673.0) marks the most probable european intraday band.
PlatinumPrecious MetalsBullish
Palladium
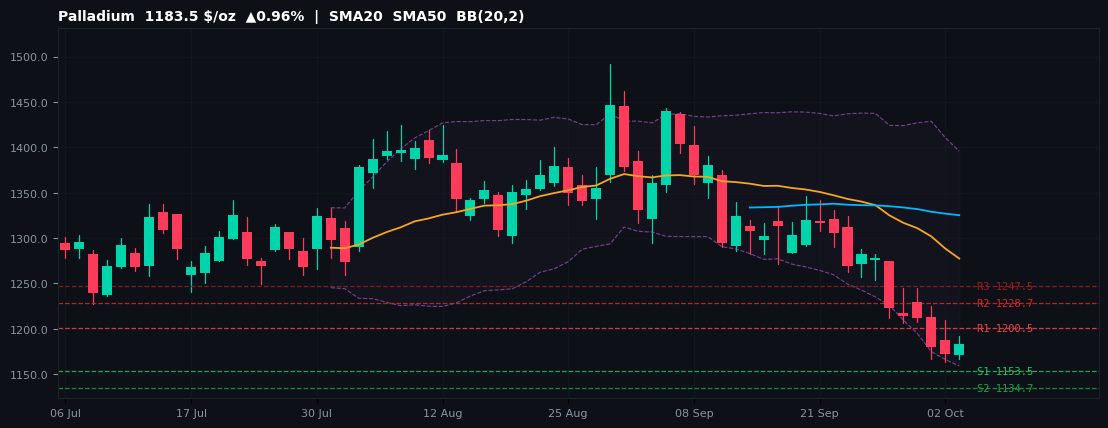
1183.5 $/oz ▲0.96% Session H 1192.0 / L 1167.0 52W 1163.0–2238.7
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 1247.5 | 1228.7 | 1200.5 | 1181.7 | 1153.5 | 1134.7 | 1106.5 |
Palladium trades at 1183.5 $/oz (+0.96% vs. prior close) as the European session gets underway, at the 2th percentile of its 1163.0–2238.7 $/oz 52-week range. Intraday bias tilts bullish while price holds above the daily pivot at 1181.7 $/oz. The 52-week range of 1163.0–2238.7 places this commodity at the 2th percentile — price remains in the lower half of its annual range, reflecting structural headwinds.
Key drivers for NYMEX palladium: automotive gasoline catalytic demand, EV transition headwinds, and Russian supply constraints. Resistance: R1 1200.5, R2 1228.7, R3 1247.5. Support: S1 1153.5, S2 1134.7, S3 1106.5 $/oz. The R1–S1 corridor (1200.5–1153.5) marks the most probable european intraday band.
PalladiumPrecious MetalsBullish
Energies
WTI Crude Oil
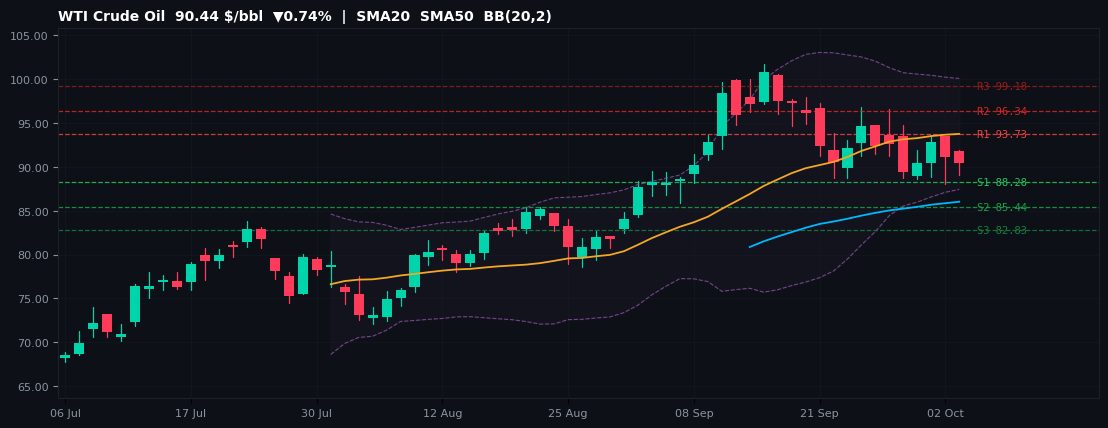
90.44 $/bbl ▼0.74% Session H 91.88 / L 89.11 52W 55.64–101.69
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 99.18 | 96.34 | 93.73 | 90.89 | 88.28 | 85.44 | 82.83 |
WTI Crude Oil trades at 90.44 $/bbl (-0.74% vs. prior close) as the European session gets underway, at the 76th percentile of its 55.64–101.69 $/bbl 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 90.89 $/bbl. The 52-week range of 55.64–101.69 places this commodity at the 76th percentile — momentum is broadly constructive within the annual range.
Key drivers for NYMEX WTI crude: OPEC+ production quotas, US EIA weekly inventory builds/draws, and refinery run rates. Resistance: R1 93.73, R2 96.34, R3 99.18. Support: S1 88.28, S2 85.44, S3 82.83 $/bbl. The R1–S1 corridor (93.73–88.28) marks the most probable european intraday band.
WTI Crude OilEnergiesBearish
Natural Gas
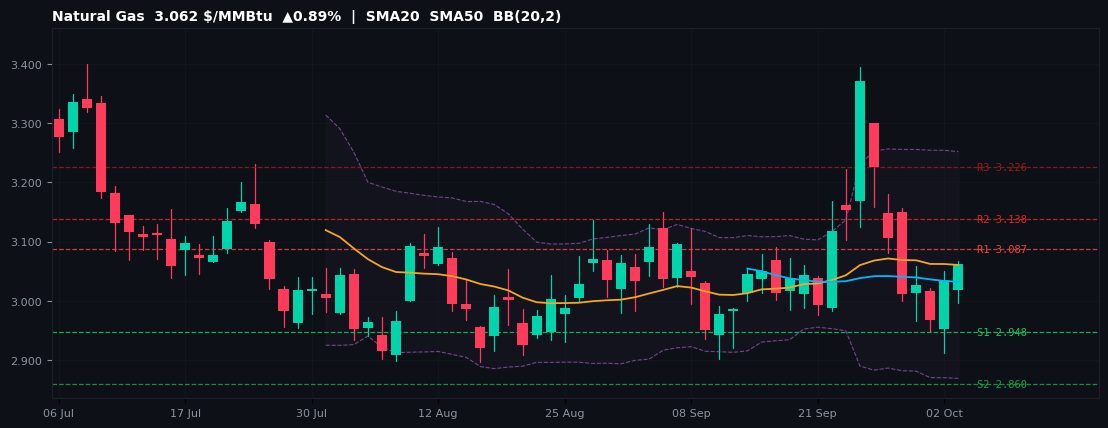
3.062 $/MMBtu ▲0.89% Session H 3.068 / L 2.997 52W 2.896–4.642
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 3.226 | 3.138 | 3.087 | 2.999 | 2.948 | 2.860 | 2.809 |
Natural Gas trades at 3.062 $/MMBtu (+0.89% vs. prior close) as the European session gets underway, at the 10th percentile of its 2.896–4.642 $/MMBtu 52-week range. Intraday bias tilts bullish while price holds above the daily pivot at 2.999 $/MMBtu. The 52-week range of 2.896–4.642 places this commodity at the 10th percentile — price remains in the lower half of its annual range, reflecting structural headwinds.
Key drivers for Henry Hub natural gas: US storage draws vs seasonal norms (EIA weekly), weather-driven heating/cooling demand, and LNG export flow. Resistance: R1 3.087, R2 3.138, R3 3.226. Support: S1 2.948, S2 2.860, S3 2.809 $/MMBtu. The R1–S1 corridor (3.087–2.948) marks the most probable european intraday band.
Natural GasEnergiesBullish
RBOB Gasoline
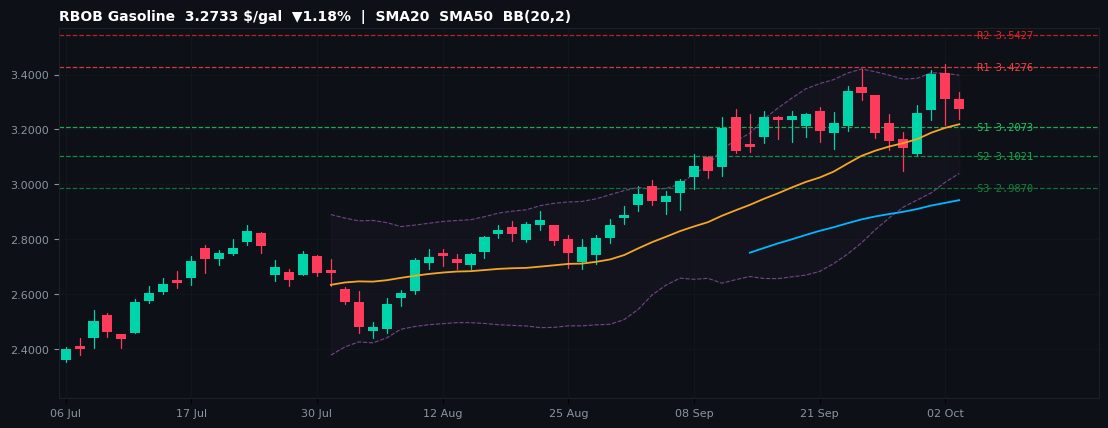
3.2733 $/gal ▼1.18% Session H 3.3363 / L 3.2374 52W 1.6502–3.4376
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 3.6479 | 3.5427 | 3.4276 | 3.3224 | 3.2073 | 3.1021 | 2.9870 |
RBOB Gasoline trades at 3.2733 $/gal (-1.18% vs. prior close) as the European session gets underway, at the 91th percentile of its 1.6502–3.4376 $/gal 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 3.3224 $/gal. The 52-week range of 1.6502–3.4376 places this commodity at the 91th percentile — momentum is broadly constructive within the annual range.
Key drivers for RBOB gasoline: US driving demand, refinery utilisation rates, and crack spread dynamics. Resistance: R1 3.4276, R2 3.5427, R3 3.6479. Support: S1 3.2073, S2 3.1021, S3 2.9870 $/gal. The R1–S1 corridor (3.4276–3.2073) marks the most probable european intraday band.
RBOB GasolineEnergiesBearish
Heating Oil
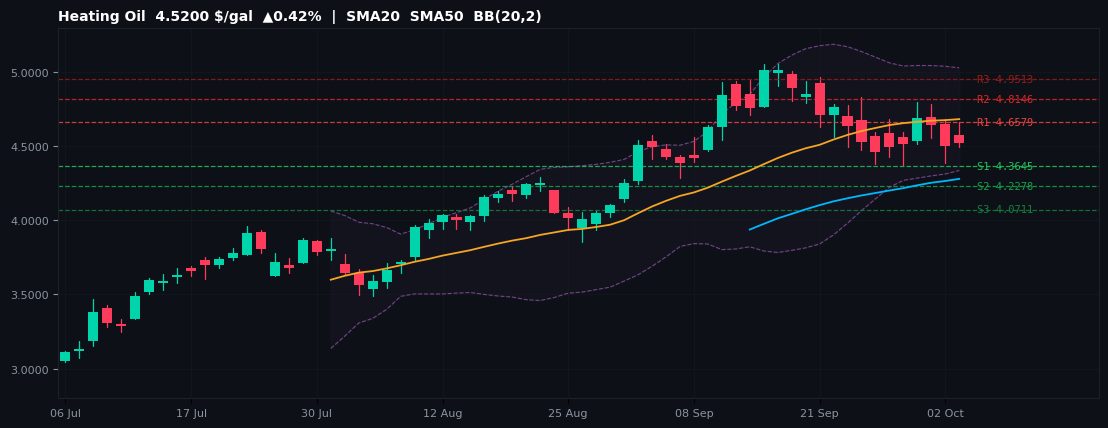
4.5200 $/gal ▲0.42% Session H 4.6578 / L 4.4930 52W 2.0326–5.0499
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 4.9513 | 4.8146 | 4.6579 | 4.5212 | 4.3645 | 4.2278 | 4.0711 |
Heating Oil trades at 4.5200 $/gal (+0.42% vs. prior close) as the European session gets underway, at the 82th percentile of its 2.0326–5.0499 $/gal 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 4.5212 $/gal. The 52-week range of 2.0326–5.0499 places this commodity at the 82th percentile — momentum is broadly constructive within the annual range.
Key drivers for ULSD heating oil: Northern Hemisphere heating demand, distillate inventory levels, and refinery run margins. Resistance: R1 4.6579, R2 4.8146, R3 4.9513. Support: S1 4.3645, S2 4.2278, S3 4.0711 $/gal. The R1–S1 corridor (4.6579–4.3645) marks the most probable european intraday band.
Heating OilEnergiesRangebound
△ OPEC+ Monitoring
OPEC+ Production Quota Update
Track the latest OPEC+ production cuts, quota allocations and compliance data. Monthly output figures, ministerial meeting outcomes and spare capacity estimates — the key drivers behind crude oil prices.
Latest OPEC coverage →Agricultural Commodities
Today's featured selection: Sugar #11, Cocoa, Coffee, Corn — comprising the session's top riser, top faller, and two additional picks.
Sugar #11
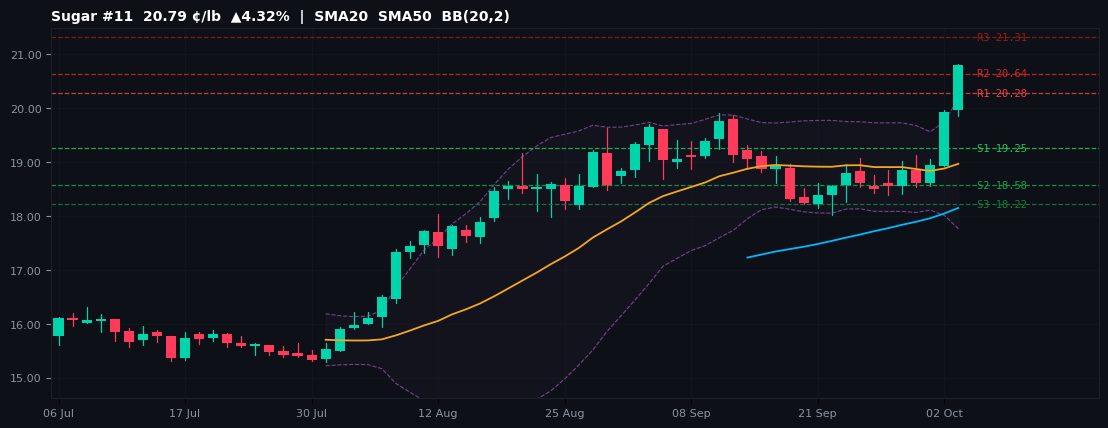
20.79 ¢/lb ▲4.32% Session H 20.81 / L 19.85 52W 14.42–20.81
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 21.31 | 20.64 | 20.28 | 19.61 | 19.25 | 18.58 | 18.22 |
Sugar #11 trades at 20.79 ¢/lb (+4.32% vs. prior close) as the European session gets underway, just 0.10% below its 52-week high of 20.81 ¢/lb. Intraday bias tilts bullish while price holds above the daily pivot at 19.61 ¢/lb. The 52-week range of 14.42–20.81 places this commodity at the 100th percentile — upside momentum is intact; a break above the 52W high would signal trend extension.
Key drivers for ICE Sugar #11: Brazilian Center-South harvest pace, Indian/Thai export policies, and ethanol economics linkage. Resistance: R1 20.28, R2 20.64, R3 21.31. Support: S1 19.25, S2 18.58, S3 18.22 ¢/lb. The R1–S1 corridor (20.28–19.25) marks the most probable european intraday band.
Sugar #11AgriculturalBullishAbove R1Near 52W High
Cocoa
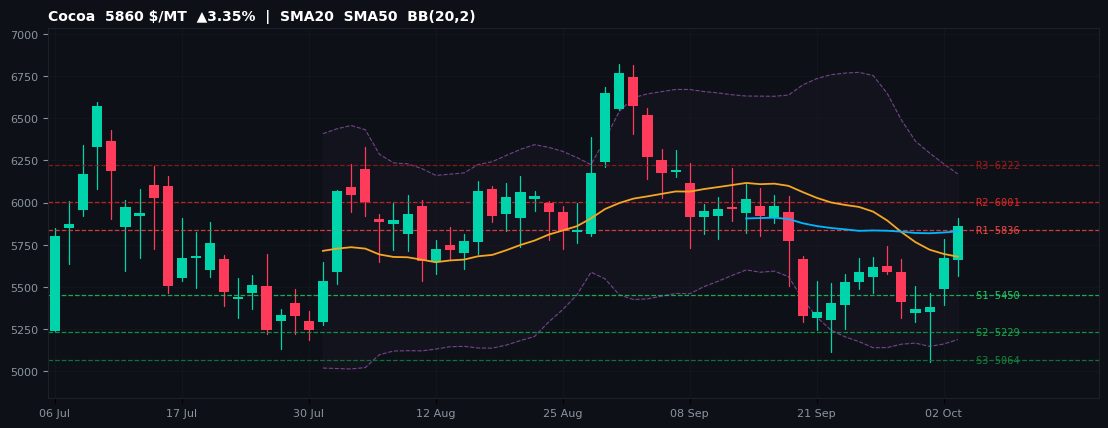
5860 $/MT ▲3.35% Session H 5908 / L 5567 52W 3061–6821
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 6222 | 6001 | 5836 | 5615 | 5450 | 5229 | 5064 |
Cocoa trades at 5860 $/MT (+3.35% vs. prior close) as the European session gets underway, at the 74th percentile of its 3061–6821 $/MT 52-week range. Intraday bias tilts bullish while price holds above the daily pivot at 5615 $/MT. The 52-week range of 3061–6821 places this commodity at the 74th percentile — momentum is broadly constructive within the annual range.
Key drivers for ICE cocoa: West African main crop arrivals (Ghana/Ivory Coast), mid-crop estimates, and European grindings data. Resistance: R1 5836, R2 6001, R3 6222. Support: S1 5450, S2 5229, S3 5064 $/MT. The R1–S1 corridor (5836–5450) marks the most probable european intraday band.
CocoaAgriculturalBullishAbove R1
Coffee
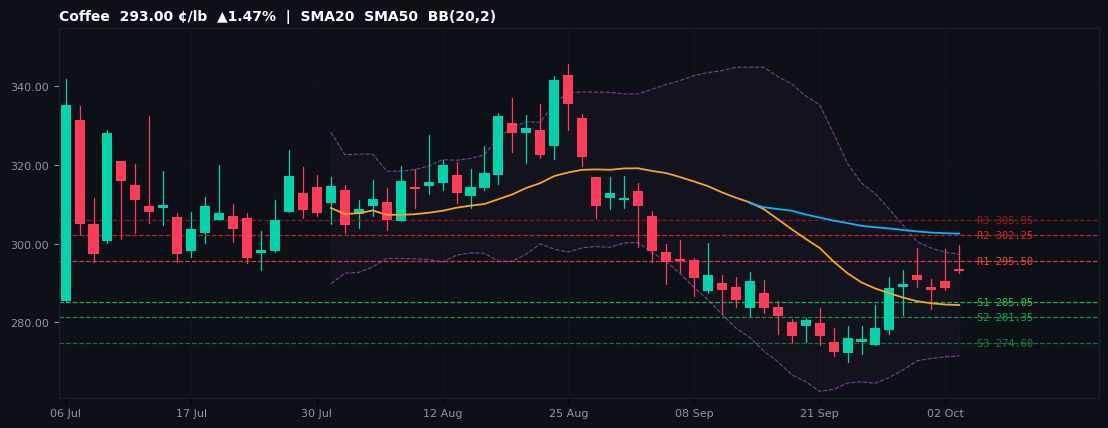
293.00 ¢/lb ▲1.47% Session H 299.60 / L 292.50 52W 231.80–348.40
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 305.95 | 302.25 | 295.50 | 291.80 | 285.05 | 281.35 | 274.60 |
Coffee trades at 293.00 ¢/lb (+1.47% vs. prior close) as the European session gets underway, at the 52th percentile of its 231.80–348.40 ¢/lb 52-week range. Intraday bias tilts bullish while price holds above the daily pivot at 291.80 ¢/lb. The 52-week range of 231.80–348.40 places this commodity at the 52th percentile — momentum is broadly constructive within the annual range.
Key drivers for ICE Arabica coffee: Brazilian and Vietnamese crop conditions, seasonal frost risk, and managed-money positioning. Resistance: R1 295.50, R2 302.25, R3 305.95. Support: S1 285.05, S2 281.35, S3 274.60 ¢/lb. The R1–S1 corridor (295.50–285.05) marks the most probable european intraday band.
CoffeeAgriculturalBullish
Corn
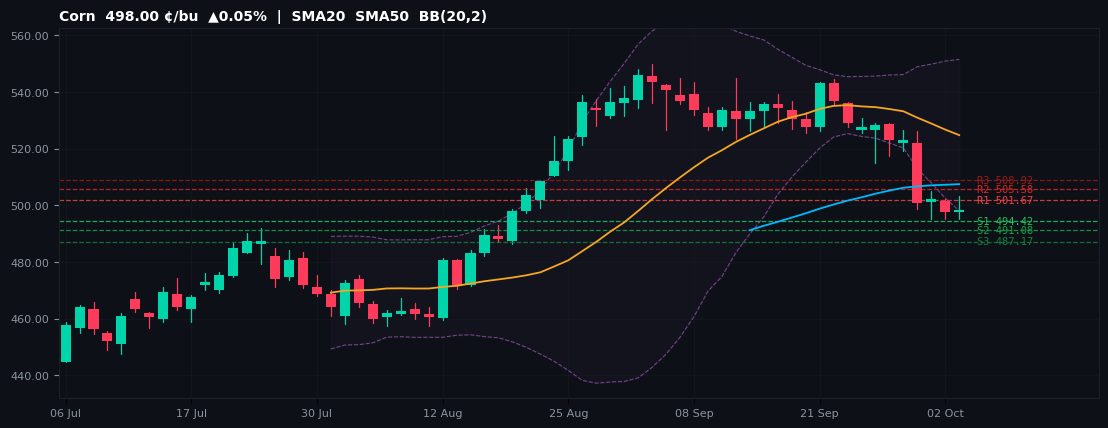
498.00 ¢/bu ▲0.05% Session H 503.25 / L 495.00 52W 425.75–549.75
| R3 | R2 | R1 | PP | S1 | S2 | S3 |
|---|---|---|---|---|---|---|
| 508.92 | 505.58 | 501.67 | 498.33 | 494.42 | 491.08 | 487.17 |
Corn trades at 498.00 ¢/bu (+0.05% vs. prior close) as the European session gets underway, at the 58th percentile of its 425.75–549.75 ¢/bu 52-week range. Intraday bias neutral-to-bearish while price holds below the daily pivot at 498.33 ¢/bu. The 52-week range of 425.75–549.75 places this commodity at the 58th percentile — momentum is broadly constructive within the annual range.
Key drivers for CBOT corn: USDA WASDE supply/demand balance, US/Brazilian crop ratings, and ethanol blend mandates. Resistance: R1 501.67, R2 505.58, R3 508.92. Support: S1 494.42, S2 491.08, S3 487.17 ¢/bu. The R1–S1 corridor (501.67–494.42) marks the most probable european intraday band.
CornAgriculturalRangebound
🌿 Agricultural Markets
Understanding WASDE Reports and Grain Markets
The USDA WASDE (World Agricultural Supply and Demand Estimates) is published monthly and is the single most important data release for grain futures. Learn how to read supply/demand tables, ending stocks, and what weather models mean for crop prices.
Explore commodities →For informational purposes only — not investment advice. Pivot levels computed from the previous session's OHLC via the classic floor-pivot formula. Price data sourced from Yahoo Finance (front-month futures) as of the European session, Monday 05 October 2026. Futures prices are subject to roll effects near contract expiry. Past performance is not indicative of future results.