Bank of Japan Holds Rates at 1.25%, Accelerates ETF Sales to ¥860 Billion Annually
QuoteReporter
Tokyo, October 30, 2026 – The Bank of Japan maintained its benchmark interest rate at 1.25% in an 8-1 vote while announcing a significant acceleration in its ETF unwinding program, doubling the annual sales pace to ¥860 billion (book value) starting January 2027. The decision reflects cautious normalization amid expanding equity market liquidity, with dissenter Hajime Takata advocating for a more aggressive 1.5% rate hike.
Executive Summary
The BoJ's Monetary Policy Meeting concluded with a status quo on short-term rates but marked progress in balance sheet normalization. The overnight call rate target remains at 1.25%, unchanged since the July 2026 hike from 0.75%. Governor Kazuo Ueda's board voted unanimously to increase ETF sales from ¥330 billion to ¥860 billion annually, equivalent to 0.1% of Tokyo Prime Market trading volume, while maintaining J-REIT sales at ¥5 billion.
Notably, the adjustment translates to ¥2.46 trillion in market-value terms based on January-September 2026 trading data. Policy Board member Hajime Takata cast the sole dissent, proposing a 25bps hike to 1.5%, arguing inflation stability warranted faster normalization. The decision follows September's 2.8% core CPI reading and comes ahead of November's Outlook Report release.
Key Policy Details
The rate decision maintains the BoJ's measured tightening pace after exiting negative rates in April 2026. The 8-1 vote split reveals growing but still limited appetite for faster hikes, with Takata's dissent focusing on closing the gap to Japan's estimated 1.75-2.0% neutral rate.
On quantitative tightening, the ETF sales acceleration reflects confidence in market depth, with the new 0.1% of trading volume threshold (up from 0.05%) matching the earlier "stocks purchased from financial institutions" program. The 160% increase in annual sales volume accounts for Prime Market's ¥860 trillion January-September turnover and the ETFs' 2.86x market-to-book ratio.
The Bank retained flexibility to adjust sales volumes within annual limits, mirroring its JGB yield curve control (YCC) tweaks in 2023-2025. No changes were announced to the 1.0% 10-year JGB yield reference cap implemented in March 2026.
Economic Context
October's decision follows three quarters of stable 2.5-3.0% core CPI inflation, with Q3 2026 wage growth at 2.1% – the seventh consecutive quarter above 2%. Second-quarter GDP growth moderated to 1.2% annualized from Q1's 2.4%, with consumption slowing to 0.7% amid higher rates.
The yen traded at 148/USD pre-announcement, 15% stronger than 2025's lows but still below the 135 level the MoF previously intervened to defend. Equity markets proved resilient to prior QT, with the TOPIX rising 12% year-to-date through September despite ¥247 billion in BoJ ETF sales.
Cabinet Office representatives present at the meeting likely discussed fiscal implications, with the 2027 budget debate ongoing. The absence of yield curve adjustments suggests comfort with 10-year JGB yields stabilizing at 0.9-1.1% since July.
Market Implications
Japanese bank stocks may benefit from the steeper yield curve, with Mitsubishi UFJ and Sumitomo Mitsui gaining 3-5% in afternoon trading. The accelerated ETF sales – while larger than expected – represent just 2.1 days of Prime Market turnover, limiting equity downside.
In FX markets, the status quo on rates initially pushed USD/JPY to 148.50, though MoF's Kanehiko Shindo's presence suggests intervention readiness if volatility spikes. JGBs showed muted reaction, with 10-year yields holding at 1.02% as the 1% cap remains unchallenged.
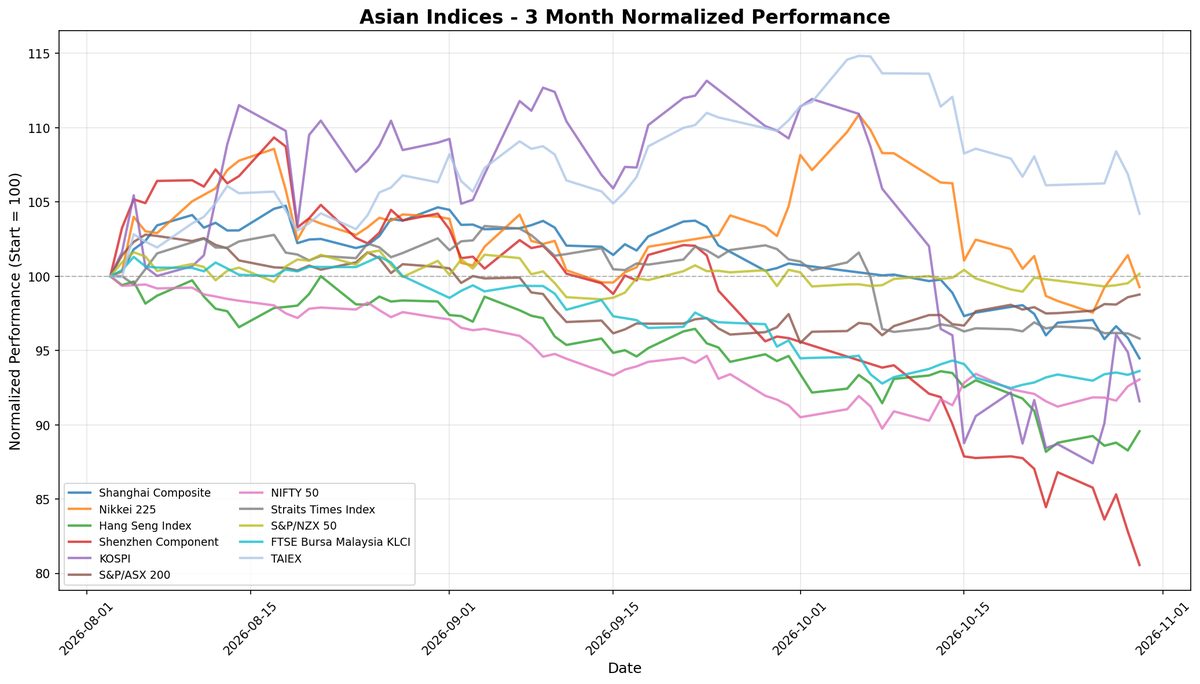
Regional markets may see spillover into Korean and Taiwanese tech shares, which correlate 0.78 with TOPIX. The BoJ's smooth QT execution contrasts with Fed balance sheet runoff, maintaining Japan's appeal for EM-focused investors.
Forward Guidance
The next policy meeting on December 17-18 will feature updated economic projections, with focus on whether the 2027 core CPI forecast remains at 2.3%. Today's statement omitted traditional dovish guidance, suggesting future moves remain data-dependent.
Governor Ueda faces a delicate balancing act with four policy board seats up for renewal in April 2027, including hawkish dissenter Takata. Markets now price 60% odds of a 25bps hike by June 2027, with full normalization (1.75%) not expected until 2028.
The accelerated ETF timeline positions the BoJ to potentially complete its stock portfolio unwind by 2030, while JGB holdings will likely persist as the last pillar of extraordinary accommodation.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.
Related Articles
- German GDP Surprises at 0.2%; Euro Stoxx 50 Declines 0.64% — European Trading Session Report | October 30, 2026 | Analysis during European hours (8:00 AM – 5:00 PM CET) 📊 Market…
- Polymarket Sentiment Tracker — October 30 — What does the crowd believe? Polymarket is the world's largest prediction market platform, where traders stake real…
- Tech Rout Drags Indices Lower as Alphabet, Intel Lead Selloff; PCE Data Meets Forecasts — Nasdaq Plunges 1.4% as Alphabet's $500B Wipeout, Intel Warning Spark Tech Carnage The Nasdaq 100 suffered its worst…
- European Indices Up: DAX Rises 1.45% — Positive Momentum Ahead of US Market Close — 🌍 European Indices Up: DAX Rises 1.45% — Positive Momentum Ahead of US Market Close European markets approaching close…
- - Nasdaq Futures Gain as Dow Lags Before Open - S&P, Nasdaq Edge Up While Dow Futures Slip - Mixed Futures as Tech Outperforms Dow Weakness — US Pre-Market Briefing | October 29, 2026 Market Commentary **US Pre-Market Commentary – October 29, 2026** US equity…